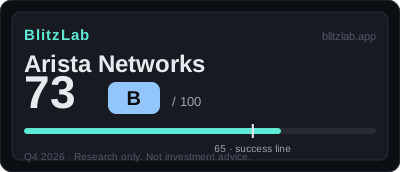
Arista Networks — Blitz Index 73 (B)
The nervous system of the AI factory — 40% growth with 43% operating margins.
Last re-scored: November 3, 2026.
Confidence: High · S&P 500 · Category: ai-infra
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 20 / 25 | Q3 2026 $3.66B (+58.5% YoY, highest since IPO); 13 straight YoY growth quarters; FY2026 guide ~$12.6B (+40%) |
| B · Moat | 42 / 60 | EOS single OS + 150M ports shipped; NPS 89; MSFT 26% + Meta 16% = 42% concentration |
| C · Creative destruction | 11 / 15 | Ethernet displacing InfiniBand in AI backend fabric; $6.9B deferred revenue |
| D · BlitzFailing | −0 | No triggers — zero debt, $13.3B cash, single-class shares |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 70 · Speed 80 · Creative 73.
Watch item
Gates: G1 pass · G2 pass (conditional, estimated). 8 above threshold — first-ever score, Q3 2026 rescore (A1 9→10). Mid-blitz, not between blitzes.
Strengths
- Q3 2026 revenue $3.66B (+58.5% YoY, highest since IPO) — 13 straight YoY growth quarters
- AI center networking $1.5B → $3.5–3.6B target for 2026 — the second blitz taking shape
- GAAP gross margin 61.9–65.2% band for 12 quarters; op margin 42.8% at 40% growth
- Zero debt, $13.3B cash — the rare blitzer that never sacrificed efficiency
Concerns
- MSFT 26% + Meta 16% = 42% of revenue — two customers, one of them also the rival
- NVIDIA Spectrum-X at 11.6% DC Ethernet penetration (+167.7% YoY) — biggest partner becoming biggest threat
- Large-customer mix dilutes margins (Q1 2026 GM fell to 61.9%, tariffs compounded)
- $9.7B purchase commitments (92% of TTM revenue) — supply-chain shock exposure
Research notes
1. Current Position
Arista Networks, Inc. (NYSE: ANET) scores 73 out of 100, Grade B, on the BlitzLab v1.0 model in the 2026Q4 scoring round, first assessed 11 October 2026 and re-scored 3 November 2026 on third-quarter 2026 results. The arithmetic is straightforward and worth stating plainly at the outset, because the rest of this assessment is an attempt to explain how those parts add up: Speed contributes 20 of 25 points, Moat contributes 42 of 60, Creative Destruction contributes 11 of 15, and Demerits subtract nothing, so 20 plus 42 plus 11 minus 0 equals 73. On the radar axes that BlitzLab derives from those sections, the picture is unusually even for a company at this scale: Moat stands at 70.0 on a 100-point conversion, Speed at 80.0, and Creative Destruction at 73.3. There is no single axis carrying the score and no single axis dragging it down. The company is classified as mature, with trailing-twelve-month revenue of about 10.5 billion dollars, precisely 10.541 billion dollars in the score file, and it clears both gates. It also clears the 65-point threshold that BlitzLab uses as its success line, by eight points, and it carries no FLAG, since demerits of zero sit well below the 15-point FLAG trigger. In the language of the score file, this is not a company between blitzes, waiting for a second curve to arrive. It is a company in the middle of its first blitz, with two second curves still at the stage of stated numerical targets rather than proven results. Third-quarter 2026 revenue, reported 3 November 2026, was $3.66 billion, up 58.5 percent year on year — the highest growth rate since the initial public offering and above the company's own guidance of about $3.3 billion — and that result lifts the growth item, A1, from 9 to a full 10 and the total from 72 to 73.
That framing matters because it changes how the growth figures should be read. Arista has grown year on year for thirteen consecutive quarters, from the third quarter of 2023 through the third quarter of 2026, with growth rates in that run ranging from 15.9 percent to 58.5 percent. The most recent four quarters in the file show not merely persistence but re-acceleration, from 27.5 percent to 28.9 percent, then to 35.1 percent, then to 37.7 percent. The second quarter of 2026 was the first quarter above 3 billion dollars, at 3.036 billion dollars. Full-year 2025 revenue reached 9.006 billion dollars, up 28.6 percent, and guidance for fiscal 2026 stood at about 12.6 billion dollars, up about 40 percent, after three upward revisions within the year. The chief executive described the third quarter of 2025 as the nineteenth consecutive record quarter, a claim the score file records as a company statement. The score file's own summary of this position is that supply, rather than demand, appears to be the binding constraint, and the numbers are consistent with that reading: a company already above 10 billion dollars in trailing revenue accelerating into the high thirty percent range is not coasting on a small base. That acceleration is the reason the growth item, A1, now scores a full 10 of 10 rather than 9: third-quarter 2026 revenue of $3.66 billion, up 58.5 percent year on year, is the highest growth rate since the initial public offering and came in above guidance of about $3.3 billion. Fourth-quarter guidance of $3.9–4.0 billion implies quarter-on-quarter growth of 7–9 percent, a normalisation, so the full mark is on this quarter's basis.
The second curves are stated with unusual numerical clarity, which is itself part of the assessment. Artificial intelligence centre networking is presented as growing from 1.5 billion dollars in 2025 to a 2026 target of 3.5 to 3.6 billion dollars, more than doubling in a single year. The campus business is presented as having exceeded 0.8 billion dollars in 2025 and targeting 1.25 billion dollars in 2026, strengthened by the 300 million dollar acquisition of VeloCloud for software-defined wide-area networking. These are targets, not results, and the score file is careful to keep that distinction. Gate G1, which asks whether growth is sustained or a second growth curve exists, is marked as a confirmed pass on the strength of the twelve-quarter run alone, with the two second curves as supporting evidence. Gate G2, which asks whether the ten-year ceiling of a new market reaches at least ten times current revenue, is marked as a conditional pass, on estimates, and the conditions deserve attention because they reveal how much of the long-term case still rests on judgement rather than measurement.
2. Moat: A Hardware Company Earning Software-Like Margins
The Moat section, at 42 of 60, is the largest block of the score and also the most instructive, because it shows how a hardware company can build a defensible position without relying on the classic network effect of a consumer platform. The first item, B1 on network effects, scores 12 of 18. The evidence is a stack rather than a single product: a single operating system, EOS, carried across the product range; a cumulative installed base of more than 150 million ports shipped; and a management and intelligence layer comprising CloudVision, NetDL, and AVA. Customer satisfaction is recorded at a net promoter score of 89, with 94 percent strongly positive, and the score file cites large customers making what it calls decisive standardising declarations, backed by ten to fifteen years of joint engineering. The score is deliberately not higher, and the reasoning is important. More customers do not directly make another customer's switch better in the way that more users make a social network better. What Arista has is closer to a standardisation moat: the more an organisation builds its operations, automation, and engineering familiarity around one operating system and one management stack, the more expensive it becomes to leave. The score file places this in the upper part of a 10 to 14 band, at 12, precisely because the switching cost is structural even though the network effect is indirect.
The second moat item, B2 on distribution scalability, scores 9 of 18, and the tension inside that score is one of the central tensions of the whole assessment. On efficiency, the distribution machine is extreme: sales and marketing expense was just 3.6 percent of revenue in the second quarter of 2026, at 109.8 million dollars. Very few companies of this scale distribute so cheaply, and the reason is direct selling to a small number of very large customers. That same concentration is the constraint. Two customers, Microsoft and Meta, accounted for about 42 percent of 2025 revenue, at about 26 percent and 16 percent respectively, and the score file notes that the larger the customer, the more favourable the pricing terms it can demand, with a consequent dilution of gross margin that the company's quarterly filing names explicitly as a risk factor. There is also little viral element in this distribution model: hyperscale operators do not adopt a networking platform because a neighbouring company recommended it over lunch. They adopt it after long engineering evaluation, and they standardise on it after years of joint work. The score therefore sits at the top of a 5 to 9 band rather than higher, not because distribution is weak, but because it is narrow. It is deep rather than broad, and depth has a price.
The third moat item, B3 on market size, scores 10 of 12. The chief executive's stated total addressable market of more than 100 billion dollars, together with a research firm's estimate of 103 billion dollars for data-centre networking by 2030, and the two second curves in artificial intelligence centres and campus networking, support a high score. The two points withheld are explicitly conditional: the full 12 points arrive, in the score file's terms, when artificial intelligence centre revenue proves the 3.5 billion dollar target in reported results rather than in guidance. That conditionality is consistent across the assessment. Arista is repeatedly given credit for direction and for targets that are specific enough to be tested, but not yet for the test itself.
The fourth moat item, B4 on gross margin, scores 11 of 12, and it is the clearest evidence for the score file's characterisation of Arista as a software-margin hardware company. Generally accepted accounting principles gross margin held in a 61.9 to 65.2 percent band across twelve quarters, with fiscal 2025 at 64.1 percent. Operating margin reached 42.8 percent in fiscal 2025, up from 38.5 percent in fiscal 2023, net margin stood at 39.0 percent, and the second quarter of 2026 recorded a generally accepted accounting principles operating margin of 45.4 percent. For a company that ships physical switches, those are exceptional figures, and they are the economic foundation of everything else in the assessment: the ability to fund supply-chain investment from operating cash flow, to return capital through repurchases, and to absorb pricing pressure from large customers without the business model breaking. The single point withheld reflects a comparison the score file makes explicitly: these margins, however strong for hardware, do not reach the 70 percent range associated with pure software businesses. That is a statement about category, not about failure.
3. Speed: Capital Discipline as a Form of Velocity
The Speed section, at 20 of 25, describes a company that moves fast without behaving like a company that is burning resources to do so. The growth item, A1 at 10 of 10, has already been described. The capital velocity item, A2 at 4 of 5, records that Arista has raised no new equity since its initial public offering in 2014, carries no borrowings, executed 1.6 billion dollars of share repurchases in fiscal 2025, received authorisation for a further 1.5 billion dollars in May 2025, and recorded its largest single quarter of repurchases at 787 million dollars in the first quarter of 2025. Market capitalisation of about 238 billion dollars as of August 2026 is cited as evidence of first-rate access to capital, should it ever be needed. The point withheld is a matter of evidence rather than performance: the twelve-quarter trend in quarter-end market capitalisation could not be confirmed from the sources available to the scorer, so the score stops at 4 on a conservative principle. That conservatism recurs throughout the file and is worth noting as a feature of the method, not a criticism of the company.
The hiring and productivity item, A3 at 3 of 5, follows the same pattern. Headcount stood at about 5,115 employees at the end of fiscal 2025, and revenue per employee reached 1.76 million dollars, a high figure by hardware standards. The historical headcount series could not be confirmed, so the score again stops at 3 on a conservative principle. A reader should not mistake that 3 for a finding of weak productivity. It is a finding of incomplete time-series evidence, and the single-year productivity figure points in the opposite direction. The distinction between a low score caused by poor performance and a low score caused by missing history is one the score file maintains carefully, and it matters for how the next scoring round should treat this item: a confirmed headcount series, in either direction, would be more informative than the current placeholder.
The share velocity item, A4 at 3 of 5, is the most genuinely contested of the Speed items. IDC data cited in the score file put Arista's share of data-centre Ethernet switching at 19.2 percent in the third quarter of 2025, on revenue of 1.9 billion dollars, up 29.1 percent year on year. Cisco remained first overall at 29.8 percent. The reason the score is only 3, despite a strong share position and strong growth in the segment, is competitive: NVIDIA had penetrated data-centre Ethernet to 11.6 percent, growing 167.7 percent year on year. Share itself looks solid; the competitive structure around that share looks worse than it did. The score file also flags, as a candidate for future model refinement, that share definitions in this market vary: the IDC segment figure of 19.2 percent sits alongside a claim of 21.5 percent for data-centre switching leadership under a different definition. Until the model standardises which definition governs A4, this item will remain partly a matter of which yardstick is chosen, and readers should treat the 3 as an estimate in that sense.
4. Creative Destruction: Replacing the Fabric, Not Just Selling Into It
The Creative Destruction section, at 11 of 15, is where Arista's claim to be a blitzscaling company, rather than merely a successful incumbent supplier, is tested. The first item, C1 on the order being replaced, scores 4 of 5. The order in question is the interconnect fabric inside artificial intelligence clusters, where Ethernet is displacing InfiniBand as the backend fabric, and Arista is positioned at the front of that shift with its EtherLink AI offering, its 7800 spine platform, and 1.6-terabit products. The point withheld reflects a complication that runs through the entire assessment: NVIDIA's Spectrum-X competes inside the same Ethernet camp. The destruction is real, but the spoils are dispersed among companies that share the same technological direction. Arista is destroying an old order without monopolising the new one, which is the classic Schumpeterian pattern and also the reason the score stops at 4.
The second item, C2 on irreversible behavioural change, also scores 4 of 5. The evidence is the standardisation of Ethernet inside hyperscale artificial intelligence clusters, which is described as under way rather than complete, and a forward indicator that gives the claim financial shape: deferred revenue rose from 6.2 billion dollars in the first quarter of 2026 to 6.9 billion dollars in the second quarter of 2026, split between 5.1 billion dollars short-term and 1.8 billion dollars long-term. Deferred revenue of that kind is not merely a backlog figure. It represents customer commitments structured over time, and its growth alongside the standardisation narrative suggests that the behavioural change, once made, is costly to reverse. The score stops at 4 because the process is still in progress. Standardisation that is under way is not yet standardisation that is finished, and the score file refuses to award full marks for a transition still being negotiated with the largest customers in the world.
The third item, C3 on cost-structure change, scores 3 of 5, and here the limitation is evidential rather than conceptual. The company has launched a 1.6-terabit artificial intelligence fabric and has described its XPO modular system as reducing rack requirements by up to 75 percent and floor area by up to 44 percent. Those are striking claims, but the score file records that all of them are company claims without independent measurement, and therefore holds the score at 3. This is the correct posture for a scholar's assessment. A cost-structure revolution that has only been asserted by its beneficiary is a hypothesis awaiting verification, not a verified fact, and the assessment says so plainly rather than dressing the assertion up as a finding.
5. Deductions and Risks: Zero Demerits, and Why That Is Not the Whole Story
The Demerits section scores zero across all four items, and that zero is as informative as any positive score, provided it is read correctly. The debt item, D1, records no borrowings and cash of 13.3 billion dollars against purchase commitments of 9.7 billion dollars. The commitments amount to 92 percent of trailing-twelve-month revenue, a figure that would alarm in many contexts, but the score file judges it within the normal range for securing hardware supply, and therefore records no trigger. The revenue-quality item, D2, records no confirmed history of revenue restatement, while noting as a concern that the auditor and audit opinion were not cross-checked against the full annual filing. The governance item, D3, records a single class of common stock with one vote per share, with the Bechtolsheim Family Trust holding 14.6 percent on exactly that one-vote-per-share basis, and insider sales executed entirely under pre-arranged 10b5-1 plans, including 300,000 shares by Bechtolsheim, about 340 million dollars by Ullal, 43,000 shares by Duda, and 5,000 shares by director Templeton. Those sales are explicitly not treated as a demerit. The regulatory and social-cost item, D4, records no confirmed material ongoing litigation, while noting that the full litigation section of the annual filing was not checked, and that tariffs appear as a risk factor in the quarterly filing even though second-quarter 2026 tariff refunds restored gross margin by 100 basis points quarter on quarter. Short interest of about 1.0 percent, down 35.6 percent during July, is also recorded under this item.
A zero in demerits should not be mistaken for an absence of risk. The score file itself lists five concerns that sit outside the demerit items or beneath their triggers, and they are more consequential than the clean demerit sheet suggests. First, customer concentration is deepening, not merely high: Microsoft's share rose from 20 percent in 2024 to an estimated 26 percent in 2025, and Meta's from 15 percent to 16 percent. Second, the large-customer mix erodes margin by structure, and the first quarter of 2026, when generally accepted accounting principles gross margin fell to 61.9 percent with tariffs overlapping, shows how that structure interacts with external shocks. Third, NVIDIA's Spectrum-X penetration, at 11.6 percent of data-centre Ethernet and growing 167.7 percent year on year, is simultaneously a competitive threat and a relationship complication, since NVIDIA is also a central figure in the ecosystem Arista serves. Fourth, purchase commitments of 9.7 billion dollars, up from 8.9 billion dollars, with inventory of 2.38 billion dollars, represent a supply-chain bet placed ahead of confirmed demand; if demand falters, that bet becomes inventory and cash pressure. Fifth, insider selling has continued, and local Form 4 records from 2021 to 2022 also showed no purchases, even though all sales were pre-planned. None of these triggers a demerit under the frozen v1.0 model, and the score file proposes, as a candidate for a future model version, that extreme customer concentration of this kind, with two customers above 40 percent, should be formalised as its own trigger, since the current model has no place to put it. That proposal is itself a useful disclosure: the model knows where its blind spot is.
6. Blitzscaling Lens: Speed Without Sacrificing Efficiency
Read through the lens of blitzscaling theory, Arista is a platform-plus-performance blitzer, and the most interesting thing about it is how it departs from the textbook. The main growth lever is platform: a single operating system across the product range, with the score file's formulation of one operating system, one data lake, and one management layer binding customers through standardisation. Hardware sales are the vehicle; platform standardisation is the blitz itself. The secondary lever is high performance: the progression from 800 gigabits to 1.6 terabits gives hyperscale operators a reason to choose Arista first, so that performance functions as distribution. The weak lever is the classic network effect, for the reasons already described: more customers do not directly improve another customer's product, and the nearest equivalent is the indirect network effect of standardisation, where a widening standard raises the cost of leaving.
The textbook blitzscaling trade-off, speed first and efficiency later, is also visibly modified here. Arista grew about 40 percent on guidance while maintaining a fiscal 2025 operating margin of 42.8 percent, which is not the profile of a company abandoning efficiency for speed. The explanation lies in the distribution efficiency already noted, at 3.6 percent sales and marketing expense, combined with direct selling to large customers, and in a distinctive variant of the efficiency-later principle: pre-investment in the supply chain. Purchase commitments rising from 8.9 billion dollars to 9.7 billion dollars, with inventory of 2.38 billion dollars, represent efficiency deferred in a specific place, the balance sheet, rather than in the operating margin. Cash of 13.3 billion dollars is what makes that deferral affordable. The third element of the trade-off is margin exchanged for share: the company offers large customers more favourable terms and accepts gross margin dilution in return for standardisation, a trade-off its own quarterly filing names. That is blitzscaling logic, but priced in margin points rather than in losses, which is a luxury few blitzers enjoy.
In terms of stage, the score file places the core data-centre business in a high-growth phase, still chasing Cisco from a 19.2 percent share, while the artificial intelligence centre and campus businesses are in the nascent phase of a second blitz, still at the target stage. The overall judgement is that Arista sits in the middle of its first blitz, and the score file contrasts this explicitly with a company such as Tesla, assessed as sitting between blitzes. The practical consequence is upside that is defined rather than vague: if the second curves prove themselves in reported results, the score file identifies room for the market-size item to reach its full 12 points; the growth item has already reached its full 10 on third-quarter 2026 results. The current 73, in other words, is a mid-blitz score with identified headroom, not a mature score with nowhere to go.
7. Competitive Landscape: The Rival Who Is Also the Ecosystem
The competitive landscape divides into the named rival, the structural rival, and the rival who is also a partner, and it is the third category that dominates. The named rival is Cisco, which retains first place overall at 29.8 percent against Arista's 19.2 percent in the IDC data-centre Ethernet segment. That is a conventional chase narrative: a challenger with a unified software platform pursuing an incumbent with broader scale. The structural shift is larger than any single rival: the replacement of InfiniBand by Ethernet inside artificial intelligence fabrics expands the contested ground beyond the traditional data-centre switching market and into the infrastructure of artificial intelligence itself, which is why the market-size and creative-destruction scores reach as high as they do.
The dominant competitive fact, however, is NVIDIA. The score file's single most pointed judgement is that the greatest risk is the largest customer becoming the largest competitor, and NVIDIA embodies that judgement in its most acute form. NVIDIA is the company whose graphics processing units define the artificial intelligence clusters that Arista's fabrics connect, which makes it an ecosystem partner of the first importance. It is also, through Spectrum-X, a direct competitor in data-centre Ethernet, already at 11.6 percent and growing 167.7 percent year on year. The score file proposes, as another candidate for a future model version, a specific anchor for this coopetition case, where an ecosystem partner converts into a direct competitor, with consequences for how the creative-destruction and moat items should be adjusted. That proposal has not been adopted, so the current score reflects the tension only through the moderate A4 and the withheld point in C1. A reader who wants to understand the fragility of the 73 should start here: the fuel of the blitz, standardisation inside large customers' artificial intelligence infrastructure, and the threat to the blitz, an alternative fabric from the company that defines those clusters, come from the same neighbourhood.
Customer concentration sharpens the point. With Microsoft and Meta together at about 42 percent of revenue, the standardisation decisions of two organisations carry disproportionate weight. If either were to shift a meaningful share of its fabric toward an alternative supplier, the effect would register not only in revenue but in the standardisation narrative itself, since the next large customer takes its cue in part from what the largest customers have already chosen. The score file does not predict such a shift, and this draft does not either. It records the structure: a moat built on standardisation is strong precisely because standardisation decisions are sticky, and vulnerable precisely because the number of decision-makers who matter is small.
8. What to Watch: The Tests That Will Move the Score
Third-quarter 2026 results, published 3 November 2026, are now reflected in this score: revenue of $3.66 billion, up 58.5 percent year on year, lifted the growth item to a full 10 and the total to 73. The first watch item is therefore the next report: fourth-quarter guidance of $3.9–4.0 billion implies quarter-on-quarter growth of 7–9 percent, a normalisation, so the test is whether growth holds near that level, whether the second quarter's 45.4 percent operating margin holds, and whether deferred revenue continues its rise from 6.9 billion dollars. Beyond that single report, the score file implies a compact checklist that a reader can apply quarter by quarter without needing any new theory.
First, the artificial intelligence centre target: does reported artificial intelligence networking revenue move convincingly toward the 3.5 to 3.6 billion dollar 2026 target from the 1.5 billion dollar 2025 base, and does the campus business move toward its 1.25 billion dollar target from above 0.8 billion dollars? Those two numbers are the stated conditions for the market-size item reaching its full score and for the second curves graduating from targets to results. Second, the concentration figures: do Microsoft and Meta remain at about 26 percent and 16 percent, rise further, or begin to dilute as the campus and artificial intelligence businesses broaden the customer base? The direction of that concentration matters more than any single quarter's level, because the score file's concern is deepening, not merely height. Third, the margin structure: does gross margin stay within or above its twelve-quarter 61.9 to 65.2 percent band, and does the large-customer discount mechanism continue to pressure it, particularly if tariff effects recur? The first quarter of 2026 showed that the bottom of the band can be reached when margin dilution and tariffs coincide. Fourth, the competitive figures: does NVIDIA's data-centre Ethernet share continue its rapid climb from 11.6 percent, and does Arista's 19.2 percent share advance toward Cisco's 29.8 percent or stall? Fifth, the supply-chain bet: do purchase commitments remain near 9.7 billion dollars, and does inventory near 2.38 billion dollars convert into revenue or accumulate? Sixth, the verification gap in cost structure: does any independent measurement emerge for the XPO claims of up to 75 percent fewer racks and up to 44 percent less floor area, which would allow the C3 score to move beyond its current evidence-limited 3?
Two further watch items concern evidence quality rather than performance. The score file is transparent that its confidence is high but not complete: it rests on company releases and secondary citations of annual and quarterly filings, because the SEC EDGAR JSON interface returned access refusals in the collection environment and primary texts could not be cross-checked for every item. The auditor and audit opinion, the full litigation section of the annual filing, the twelve-quarter market capitalisation trend, and the historical headcount series are all recorded as unconfirmed. A future scoring round that closes those gaps would strengthen the assessment even if no score changed. Similarly, the valuation note in the score file, recording market capitalisation rising from about 238 billion dollars in August 2026 to about 273 billion dollars around 10 October 2026, with a trailing price-to-sales ratio of about 23 times, is explicitly excluded from the score, following the lesson drawn from earlier testing that a business score does not look at price. It is recorded here for the same reason: to keep the boundary between assessing the business and assessing its market valuation visible.
9. One-Line Risk
If the blitz has a single point of failure, it is this: the standardisation that powers Arista's moat is decided by a handful of very large customers, inside an ecosystem defined by a partner that is also becoming a direct competitor, so the source of the company's speed and the source of its potential reversal are located in the same place.
More AI Infra companies
Other AI Infra names on the Blitz Index, highest score first: NVIDIA (87/A), Advanced Micro Devices (62/B), Astera Labs (61/B).
Next earnings
Q4 2026 · Expected
Coverage
As of November 2026 · Model v1.0 (frozen) · Confidence: High (listed, SEC filings) · Not investment advice — a scholar's assessment.
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.