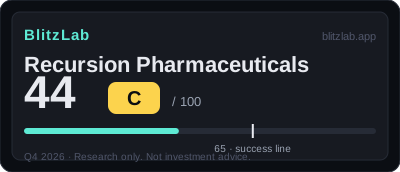
Recursion Pharmaceuticals — Blitz Index 44 (C)
Partnership-routed PMF — the second case after CRISPR — where partner cash is real and realized gross margin is 5%.
Last re-scored: October 20, 2026.
Confidence: High · Category: frontier
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 15 / 25 | Milestone-driven revenue is lumpy ($5–36M quarters); Sanofi exercised its first candidate option on Oct 15, 2026 |
| B · Moat | 24 / 60 | A ~60PB proprietary data moat, but a realized gross margin of 5% — revenue is closer to cost reimbursement |
| C · Creative destruction | 9 / 15 | AI-first drug discovery reached its first pharma-pipeline adoption; TUPELO cut polyp burden (median −47%) |
| D · BlitzFailing | −4 | Near-zero debt, but a ~$90–95M quarterly burn funded by repeated dilution |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 40 · Speed 60 · Creative 60.
Watch item
Gates: G1 ✓ (partnership-routed PMF, CRSP precedent) · G2 ✓ (borderline). Bar ≈ $549M on TTM collaboration revenue; milestone potential is a contract ceiling, not a market, and was excluded.
Strengths
- Sanofi's first option exercise (Oct 15, 2026) — a platform asset entered a major pharma pipeline; $300M+ more in milestones plus double-digit royalties
- TUPELO (REC-4881, FAP): polyp burden fell in 87% of patients (median −47%), no Grade 3+ treatment events; registrational trial planned 2H 2027
- Partner cash in exceeds $500M cumulative (Roche $213M, Sanofi $144M) — repeat purchases by four large pharmas
- A $200M raise extended the runway into 2029, with essentially no debt
Concerns
- Product revenue is $0 and realized gross margin is 5.0% — revenue reimburses costs more than it sells output
- Quarterly revenue swings $5.2M–$35.5M — a single milestone makes or breaks a quarter
- Net loss of $644.8M (FY2025) and a $2.3B accumulated deficit — dilution is structural, not episodic
- 100% of revenue depends on four partners' priorities (10-K risk factors)
Research notes
Thesis: a platform waiting for translation
Recursion Pharmaceuticals, Inc. is a clinical-stage technology and biotechnology company, founded in 2013, whose central claim is that drug discovery can be compressed into an integrated platform. The company calls that platform Recursion OS. It combines phenomics data, multi-omic data, and patient-derived data with generative precision chemistry, added through the acquisition of Exscientia, completed in November 2024, and with AI ClinTech, described in the score file as an integrated feedback loop. The score for the fourth quarter of 2026, assessed as of 20 October 2026, is 44 out of 100, grade C, made up of 15 points for Speed, 24 points for Moat, 9 points for Creative Destruction, and minus 4 points in deductions. That total sits 21 points below the 65-point threshold used in the BlitzLab model, so the company is recorded as below that threshold. The score is not a judgment about a share price. It is a judgment about the business, measured against the frozen BlitzLab version 1.0 model, and the most important thing to understand about it is the gap between inputs and outputs.
On the input side, Recursion has contracts, data, capital, and partners. On the output side, it has no approved product and no product revenue. Every dollar of revenue reported to date in the score file is collaboration research and development service revenue, recognised under ASC 606 in proportion to costs incurred, rather than revenue from a product that patients or clinicians have purchased through a commercial channel. Total trailing-twelve-month revenue to the assessment date was about 54.9 million dollars, built from 5.2 million dollars in the third quarter of 2025, 35.5 million dollars in the fourth quarter of 2025, 6.5 million dollars in the first quarter of 2026, and 7.7 million dollars in the second quarter of 2026. Annual revenue rose from 44.6 million dollars in fiscal 2023 to 58.8 million dollars in fiscal 2024, an increase of 32.0 percent, and then to 74.7 million dollars in fiscal 2025, an increase of 26.9 percent. Those figures are confirmed from Securities and Exchange Commission filings. The growth is real in the accounting sense, and it is also uneven in a way that matters for interpretation. The fourth quarter of 2025 alone contained a 30 million dollar acceptance fee from Roche, so a single milestone event shaped an entire quarter. The ordinary quarterly run rate implied by the first two quarters of 2026 was roughly 6 to 8 million dollars per quarter, below the fiscal 2025 annual level when annualised in that rough way, and the score file discounts growth quality for exactly that reason. Growth here is, in the score file's phrase, a function of partner research spending and milestone timing, not a smooth ramp of product demand.
That distinction runs through both gates in the assessment. Gate 1, product-market fit, is recorded as a pass, but explicitly as a borderline pass. The reasoning is careful and worth stating in full, because it is the decision on which the rest of the score depends. If product-market fit is asked as whether a product is being sold, the answer for Recursion is not yet yes. If it is asked as whether platform demand repeatedly draws payment, the answer is yes. The score file applies the same standard used for CRISPR Therapeutics, where commercialisation through a partnership was recognised as a form of product-market fit, while also recording how far Recursion sits from that precedent. CRISPR had an approved product, paying patients, a joint-venture level quarterly revenue ramp of 76 million dollars, and a 40 percent share of economics. Recursion had none of those four elements. It had no approved product, no product revenue, no equivalent ramp, and only royalty options rather than shared product economics. It was also clearly distinct from the failed-gate precedent of Joby, which had no commercial revenue, was pre-certification, and had no quantified backlog. Recursion, by contrast, could point to repeated cash inflows from partners, to organic revenue growth across fiscal 2023 to fiscal 2025, and, most importantly, to a partner taking a platform-derived asset into its own pipeline.
The partner evidence is substantial in cash terms. Cumulative cash inflows from four partners exceeded 500 million dollars, according to the fiscal 2025 Form 10-K. Roche and Genentech together contributed 213 million dollars in cumulative cash, comprising a 150 million dollar upfront payment and two Phenomap acceptance fees of 30 million dollars each, in September 2024 and October 2025. Sanofi contributed a cumulative 144 million dollars, comprising a 100 million dollar upfront payment, milestone payments of about 37 million dollars, and a 10 million dollar option exercise on 15 October 2026. Bayer's relationship showed repetition over time, beginning with a contract in 2020, expanding in 2021, and being amended and restated in 2023. The fourth partner named in the score file is Merck KGaA. The score file is equally clear about the limit of this evidence. Because revenue is recognised in proportion to costs incurred, it resembles reimbursement of costs incurred more than it resembles a price set by demand. Fiscal 2025 cost of revenue was 71.0 million dollars against revenue of 74.7 million dollars. That is why the score file calls this revenue an indirect indicator of product-market fit rather than product-market fit itself, and why the limitation is carried as a discount in the growth and gross-margin items rather than being used to overturn the gate.
Gate 2, the new-market test, is also recorded as a pass, also borderline, and also on an estimated basis. The test in the model is whether the ten-year ceiling of a new market is at least ten times current revenue. The score file declares its basis before applying it, rejecting two alternative definitions. It rejects treating the contractual milestone ceilings in partner agreements, which exceed 20 billion dollars in total potential, as a market, on the grounds that a contract ceiling is not a market. It also rejects applying the product-economics standard used for CRISPR directly, on the grounds that Recursion has no approved product and therefore no attributable product economics to measure. The adopted basis is trailing-twelve-month collaboration and service revenue of 54.9 million dollars, giving a bar of approximately 549 million dollars. A fiscal 2025 revenue basis of 74.7 million dollars would give a bar of 747 million dollars, and the score file notes that the conclusion is the same on either basis. The substantive evidence for passing the bar comes from a single indication. The target market for REC-4881 in familial adenomatous polyposis, covering the United States and the five largest European markets, is stated as 15 billion dollars on a press-reported basis. That is about 27 times the 549 million dollar bar, and the score file notes that a penetration rate of only 4 percent would reach the bar. The rest of the ceiling is option value, not demonstrated market capture: Sanofi collaboration milestones of up to 1.8 billion dollars plus high-single-digit to mid-teens royalties, and Roche Phenomap economics of more than 250 million dollars for 16 maps received, more than 250 million dollars for an external-use option, and up to 40 programmes in total. Those are recorded as upside options only, not as passing evidence, because the adopted definition excludes contract ceilings. The borderline character of the pass follows directly. Most of the ceiling depends on pipeline options, and there is no commercialised asset. The score file also notes that a market capitalisation of about 1.87 billion dollars, on a press-reported basis, is already 3.4 times the bar, which it reads as evidence that the market has already priced a substantial part of this option value, not as evidence that the ceiling has been demonstrated.
Moat: data, partners, and a monetised map
The Moat section totals 24 points out of 60, the weakest of the three positive sections when expressed as a share of its maximum, and that pattern is informative. The strongest Moat item is market size, at 8 out of 12, and the weakest is gross margin, at 2 out of 12. Network effects and distribution each score 7, on scales of 18. The picture is a company whose potential market and partner reach look larger than its demonstrated economics.
Network effects score 7 out of 18, in the anchor range of 5 to 9 for data and ecosystem effects. Recursion OS is described as a loop in which phenomics, multi-omic, and patient-derived data, including a proprietary dataset of about 60 petabytes on a press-reported basis, feed generative precision chemistry and AI ClinTech, and partner programmes feed learning back into the system. The concrete monetisation of that loop is Phenomap. Roche paid 30 million dollars per acceptance, twice, for a data product itself. That is a step more concrete than the network-effect evidence recorded for CRISPR, which scored 6, and the score file credits Recursion with one additional point for that reason. The limit is equally specific. No quantitative indicator has been disclosed for the claim that more programmes make the model better, such as a hit rate or a cycle-time reduction, and the company's own clinical proof of concept is REC-4881, its first. The score therefore sits in the middle of its anchor range, reflecting a flywheel that has been paid for in a specific instance but has not yet been measured in the way a mature data advantage would be.
Distribution scores 7 out of 18, the same as CRISPR, for a structurally similar reason. Distribution, for Recursion, is partner pipeline adoption itself. Sanofi takes responsibility for development, manufacturing, and commercialisation of the candidate it optioned, while Recursion concentrates on design and optimisation. Roche has an option for up to 40 programmes built on Phenomap. That is a repeatable model for riding large pharmaceutical distribution networks without building a commercial organisation of the company's own. The discount is the mirror image of the advantage. Recursion has no commercial organisation of its own, so control of distribution rests entirely with partners, and a change in a partner's priorities would mean an interruption in revenue, a risk stated in the Form 10-K risk factors. The anchor description for the 5 to 9 range, covering paid or sales-dependent distribution that can still expand repeatedly, fits this structure, and the score sits at the upper end of that range because the partner model has repeated.
Market size scores 8 out of 12, the same as CRISPR and AbCellera, each of which also scored 8. The reasoning follows Gate 2. The familial adenomatous polyposis market of 15 billion dollars on a press-reported basis, taken alone, is 27 times the bar, but the ceiling the company can actually capture is a function of pipeline success probabilities. There is no commercialised asset and only one asset approaching a registrational trial, REC-4881, with that trial planned for the second half of 2027. Expansion into Sanofi immunology indications, Roche neuroscience, and other areas is upside, but all of it is option value. The score file states the condition for a full score plainly: a score of 12 would require commercialisation evidence from at least one asset in the company's own pipeline. Until then, 8 records a large addressable ceiling discounted for the absence of a commercial proof point.
Gross margin scores 2 out of 12, and the reasoning is the most disciplined in the file. Realised margin is effectively absent. Fiscal 2025 revenue of 74.7 million dollars minus cost of revenue of 71.0 million dollars leaves gross profit of about 3.7 million dollars, a margin of 5.0 percent, calculated from confirmed filings. The cost-proportional recognition structure means service margin is thin by design. Future margin from royalties, including double-digit royalties from Sanofi if successful, is option value, not realised margin, and the score file applies the anchor principle of scoring an estimated item one range lower. Recursion scores below CRISPR, which scored 3, for a reason that is worth noting because it reverses the usual intuition. CRISPR's margin could not be measured, while Recursion's margin could be measured, and the measured result was 5.0 percent. A low measured number is treated as weaker evidence than an unmeasured but theoretically high margin. That is a strict standard, and it is applied consistently.
Speed: capital access is fast, and expensive
The Speed section totals 15 points out of 25. Growth scores 5 out of 10, capital velocity scores 4 out of 5, hiring and productivity scores 3 out of 5, and share-of-market speed scores 3 out of 5. The section reads as a company that can raise capital and attract partners quickly, but whose revenue engine is lumpy and whose organisation has recently been contracting rather than expanding in headcount.
Growth, at 5 out of 10, has already been described in substance. Annual revenue growth of 32.0 percent and then 26.9 percent is a real record, and it is placed between two comparators in the score file. It is stronger in annual revenue substance than CRISPR, which scored 4 on the strength of a joint-venture product ramp, and weaker in headline terms than AbCellera, which scored 6 on a 160 percent increase driven by a one-time royalty. The middle score reflects that ordering, together with the discounts for milestone timing, cost-proportional recognition, and the absence of product revenue growth, which remains zero.
Capital velocity scores 4 out of 5, the highest Speed item, and the evidence is a repeated demonstration of access to capital. Ordinary share financings since 2023 totalled 957.1 million dollars on a confirmed basis. An at-the-market programme in the third quarter of 2026 raised net proceeds of about 86 million dollars. On 15 October 2026, the company completed a 200 million dollar offering of 61.54 million shares at 3.25 dollars per share, described as oversubscribed, with Goldman Sachs, Morgan Stanley, Leerink, and Evercore as underwriters. After that offering, cash was about 561 million dollars on a preliminary 30 September basis plus about 200 million dollars from the offering, supporting a company-stated runway into 2029. The discount is price, not access. The offering price of 3.25 dollars was about one tenth of the initial public offering price of 31.30 dollars, and the share price fell 16.7 percent after the announcement. The score file draws the distinction cleanly. The speed of raising capital was fast, but the price was poor, and the cost of that dilution is carried in the debt and dilution deduction rather than in this item.
Hiring and productivity scores 3 out of 5. Headcount was close to 600 employees at 31 December 2025, confirmed in the Form 10-K, down from about 800 employees immediately after the Exscientia merger, after a reduction of about 20 percent during 2025 on a press-reported basis. That is a restructuring phase, not a blitz-style hiring phase. Revenue per employee was approximately 125,000 dollars on a fiscal 2025 basis, estimated, a figure the score file cautions is unsuitable as a software-style metric for a service-revenue structure and typical of the low productivity of a biotechnology company at this stage. The offsetting evidence is internal adoption of the company's own tools. The score file records, from the Form 10-K, that 91 percent of the technical organisation uses artificial intelligence coding tools, that 35 percent of code is written by artificial intelligence, and that 4.3 hours per person per week are saved. That is presented as evidence of the company applying its own artificial intelligence platform to itself, and it lifts the score one point above CRISPR and AbCellera, which each scored 2.
Share-of-market speed scores 3 out of 5. There is no quantified market share figure, because no quantitative share indicator exists for the artificial intelligence drug discovery market. The proxy evidence is the speed of platform adoption: four partners, cumulative cash inflows above 500 million dollars, two Roche Phenomap acceptances with an option for up to 40 programmes, and the Sanofi option exercise on 15 October 2026. That breadth and repetition is stronger than AbCellera, which scored 2 after its partner programmes fell from 44 to 35, and weaker than CRISPR, which scored 4 with category definition plus an approved product. The score of 3 records adoption that is broad and repeated, but not yet anchored by a commercial product.
Creative destruction: a clear target, an early proof point, and a cost structure that has not yet changed
The Creative Destruction section totals 9 points out of 15. The order being displaced scores 4 out of 5, irreversible behaviour change scores 3 out of 5, and cost-structure change scores 2 out of 5. The shape of the section is consistent with a company that has identified a large incumbent process to replace, has produced an early clinical signal that the replacement can work, but has not yet shown that the replacement is cheaper.
The order being displaced is the traditional drug discovery process, in which hypothesis, molecule, and clinical work are optimised separately, and Recursion proposes to compress that entire process into the integrated Recursion OS platform. The same logic applies to disease areas such as familial adenomatous polyposis, where no approved therapy exists and the available options are surgery and endoscopic surveillance. The score file records translation evidence for this item as well: the TUPELO topline results described below, and Sanofi's adoption of a platform-derived candidate into its own pipeline. The discount is that displacement is not complete without an approved drug, and Recursion has none. CRISPR, which has demonstrated paradigm-level displacement, scored 5. Recursion scores one point below that, and above the anchor of 3 for displacement in progress with limited scope, because the evidence is stronger than that anchor but not yet complete.
Irreversible behaviour change scores 3 out of 5, the anchor for behaviour change in progress. The first piece of evidence is TUPELO, the Phase 1b and Phase 2 trial of REC-4881, a MEK1 and MEK2 inhibitor, in familial adenomatous polyposis. After 12 weeks of treatment, 87 percent of patients showed a reduction in total polyp burden, with a median reduction of 47 percent, and one third showed a reduction of 65 percent or more. After a 12-week treatment-free period, 85 percent remained below baseline. No treatment-related adverse events above Grade 3 were reported. These figures come from a press release filed as an exhibit to the Form 8-K on 15 October 2026, with a data cutoff of 10 September 2026. The score file includes an explicit correction on interpretation that this draft preserves verbatim in substance: the figure is not minus 87 percent, but 87 percent of patients showing a reduction with a median of minus 47 percent, and the asset is REC-4881 in familial adenomatous polyposis, not REC-994. The second piece of evidence is Sanofi's adoption of a platform candidate into its own pipeline, a signal that a large pharmaceutical company's research behaviour, in internalising an external platform asset, has begun to change. The discount is that patient behaviour and standards of care change only after approval, and the trial population is small, at Phase 1b and Phase 2 scale. A score of 3 records change in progress, not change completed.
Cost-structure change scores 2 out of 5, and here the evidence runs against the platform thesis in the near term. Internal productivity evidence exists, in the 4.3 hours saved per person per week from artificial intelligence coding tools, confirmed in the Form 10-K. A single case is also cited on a press-reported basis: REC-1245 was discovered in 18 months after screening 204 compounds. What does not exist is a time series for cost per candidate or failure rate that would show a collapse in the unit cost of drug discovery. The counter-evidence is heavier. Platform research and development costs in fiscal 2025 were 475.3 million dollars, including 232.6 million dollars for the platform itself, a sharp increase on the prior year. Costs are expanding, not collapsing, and no cost-structure change appears in the profit and loss account. The score of 2 reflects that balance: internal productivity gains are real, but the central claim of a collapsing discovery cost structure is not yet measured.
Deductions and risks: no debt, but dilution is the fuel
Total deductions are minus 4 points, well below the minus 15 point threshold that would trigger a FLAG in the model, and the score file records no FLAG. The composition of those 4 points matters more than the total, because it shows where the model's concern actually sits.
Debt scores minus 3 out of a possible minus 10. The company is effectively without borrowings in the conventional sense. Debt is stated as 18.7 million dollars, comprising tenant improvement and supercomputer leases, confirmed from filings, against cash of about 561 million dollars on a preliminary 30 September basis plus about 200 million dollars from the October offering. The deduction is not about borrowings. It is about a dilution-funded financing structure, applying the same standard used for another candidate in the model's version 1.1 notes. Quarterly cash burn is about 90 to 95 million dollars, derived from operating cash flow of minus 371.8 million dollars in fiscal 2025 and minus 187.0 million dollars in the first half of 2026, both confirmed. The fiscal 2025 net loss was minus 644.8 million dollars, and the accumulated deficit was 2.3 billion dollars. Financing has come entirely from equity: 957.1 million dollars since 2023, plus about 86 million dollars from the at-the-market programme, plus 200 million dollars from the October offering, and the share count has more than doubled in three years, to about 540.9 million shares after the offering on a press-reported basis. The runway to 2029 is company-stated, and the structure implies that if the pipeline has not commercialised by then, the same form of financing would need to repeat. The score places this between two comparators. It is lighter than the minus 7 recorded for a company using debt-type financing, and heavier than the minus 2 recorded for CRISPR, which had only a remaining at-the-market channel. The distinction is that Recursion's dilution is already large and repeated, not merely available.
Revenue quality scores 0 out of a possible minus 10, a no-trigger result. There has been no revenue restatement, no auditor change, and no audit opinion issue, and no material weakness is mentioned in the Form 10-K or Form 10-Q as of the assessment date, all confirmed. The lumpiness of quarterly revenue, from 5.2 million dollars to 35.5 million dollars, with the 30 million dollar acceptance concentrated in the fourth quarter of 2025, and the qualitative limit of cost-proportional recognition are real, but they are the disclosed accounting structure itself rather than a quality event, and they have already been discounted in the growth and gross-margin items. The score file applies the same standard used for CRISPR, which scored 0 despite a one-time licence of 10 million dollars, and for AbCellera, which scored 0 with one-time royalty dependence recorded only as a concern.
Governance scores minus 1 out of a possible minus 5. The trigger is narrow and specific. The chief executive at the time of the Form 10-K was Chris Gibson, while the press release of 15 October 2026 describes Najat Khan as President and Chief Executive Officer. The timing and circumstances of that change had no confirmed Securities and Exchange Commission disclosure as of the assessment date, and the score file records that gap as press-reported, with the underlying timing marked unconfirmed. That transparency gap during a leadership transition draws a mild deduction of minus 1. No structural governance issue is recorded: no dual-class voting structure and no related-party transaction issue appear in the Form 10-K, and no unusual insider trading pattern was identified, with Form 4 filings continuing in the ordinary way into early October 2026.
Regulatory and social cost scores 0 out of a possible minus 5, also a no-trigger result. No securities litigation, fine, or clinical halt order is recorded in the disclosure history. The concentration of 100 percent of revenue in four partners is a structural risk, but following the CRISPR precedent, where 100 percent dependence on Vertex was recorded as business risk rather than in this deduction, it is carried as a concern and as a discount in distribution rather than as a deduction here. Two clinical items are recorded as concerns in the same way. The design of the REC-4881 registrational trial is under discussion with the Food and Drug Administration and is unconfirmed, and SYCAMORE, the REC-994 programme, was licensed out in May 2026 after efficacy was not demonstrated, on a press-reported basis, providing a counter-example to the platform hit rate.
The wider risk list in the score file extends beyond the deductions. Product revenue is zero and realised gross margin is 5.0 percent, so revenue resembles cost reimbursement more than product sales. Quarterly revenue volatility means a single milestone can determine an entire quarter. The net loss, accumulated deficit, and quarterly burn make repeated equity financing structural. The company's own clinical proof of concept is REC-4881 alone, with the rest of the pipeline, including REC-617, REC-1245, and REC-3565, at Phase 1 level. Partner concentration means a change in priority at any of the four partners would interrupt revenue. The chief executive transition disclosure gap has already been noted. Set against those concerns, the positive list is also specific. The Sanofi option exercise, the TUPELO topline, cumulative partner inflows above 500 million dollars, a partial response observation for REC-1245 as a single agent in the DAHLIA study, the October offering supporting a runway into 2029 on a company-stated basis, an effectively unlevered balance sheet, a dataset of about 60 petabytes on a press-reported basis, the BioHive-2 supercomputer developed in collaboration with NVIDIA, and the Exscientia chemistry capability together form the integrated stack on which the score rests.
The Blitzscaling fit analysis in the score file makes the same point in strategic language. The primary growth lever is the platform and data flywheel, in which accumulating phenomics data improves discovery, completed by BioHive-2 and Exscientia chemistry. The secondary lever is partnership distribution, riding large pharmaceutical pipelines and commercial organisations instead of building a commercial organisation, a structure shared with CRISPR and Vertex. The fuel lever is capital, and for a company without product revenue, equity issuance is the only fuel that sustains the blitz. The weak levers are genuine network effects, which are data effects rather than user network effects, and speed measured on the company's own revenue rather than on partner activity. The verdict is that Recursion is a platform and data type blitz company, but one that must be measured on inputs, meaning data, capital, and partner contracts, rather than on outputs, meaning revenue and margin. The speed-versus-efficiency trade-off has been resolved in favour of speed, with research and development spending of 475 million dollars per year against revenue of 74.7 million dollars, a ratio of 6.4 times revenue, and with the Exscientia acquisition, valued at 688 million dollars entirely in shares on a press-reported basis, chosen as a way to acquire chemistry capability quickly. The direction changed in 2025, with portfolio pruning, including the discontinuation or partnering of REC-2282, REC-994, and REC-3964, a reduction of about 20 percent in headcount on a press-reported basis, and a slowing in the growth of research and development spending, with first-half 2026 spending of 177.5 million dollars. The score file cautions that the benefit of that shift, in realised cost savings in the profit and loss account, has not yet been demonstrated, and that a headcount reduction is closer to fitness management than to acceleration.
What to watch: two clocks
The score file frames the company's present stage as the verification phase of a first blitz, asking whether the platform becomes medicine. Contract, data, and capital inputs carry the signature of a blitz, while outputs in approved drugs, product revenue, and realised margin are all still zero. TUPELO and the Sanofi option exercise are described as the first interim answers to that test. The file's own summary phrase is that this is a platform blitz awaiting translation, and that the two clinical events of 2027 will determine whether the company is confirmed as an artificial intelligence drug platform or as an expensive research and development service business.
The watch list follows directly from the gate review triggers and the concerns already recorded, and it contains no anticipated outcomes. The first item is the Sanofi candidate, a first-in-class dual-target small molecule in immunology, whose option was exercised on 15 October 2026, with a Phase 1 trial planned for 2027, additional milestones of more than 300 million dollars, and double-digit royalties attached on the terms stated in the score file. Any delay or cancellation of that Phase 1 start would be a trigger for re-examination of Gate 1. The second item is REC-4881, with a registrational trial planned for the second half of 2027, and with the design of that trial still under discussion with the Food and Drug Administration, unconfirmed. Any breakdown in that discussion would be a second trigger. The third item is partner continuity. Termination or reduction of the Roche or Sanofi contracts would be a third trigger, and more generally, an interruption in further partner cash inflows within the company-stated runway to 2029 would be a fourth. The fourth item is the financing clock itself. Quarterly burn of about 90 to 95 million dollars continues whether or not clinical data arrive, while clinical data arrive on a biotechnology timetable set by regulatory discussion, registrational trials, and Phase 1 starts. Each time the gap between those two clocks widens, the gap is filled by equity issuance, as the record of a share count more than doubling in three years already shows. The score file's central risk statement is that partner product-market fit is the only buffer in that race, and that the next decisions by Roche and Sanofi, whether further option exercises or quiet endings, will in effect set the price of the company's next financing.
One further item is recorded as a future marker only, with no anticipated outcome. Third-quarter 2026 results were not published as of the assessment date of 20 October 2026 and are therefore excluded from this score. The date of those results was unconfirmed at the assessment date, with estimates in conflict between 4 November 2026 and 11 November 2026, and with no announcement from investor relations. That item will belong to the next assessment, not to this one, and no outcome is anticipated here. The same discipline applies to the other post-assessment markers in the file. The Sanofi Phase 1 trial in 2027, the REC-4881 registrational trial in the second half of 2027, and the company-stated runway into 2029 are all future markers. They are the points at which the translation question will start to receive answers, and until then the score of 44 out of 100, grade C, records a platform with paid partner demand, a large but option-dependent ceiling, a thin realised margin, and a financing structure that depends on equity, all measured as of 20 October 2026.
More Frontier companies
Other Frontier names on the Blitz Index, highest score first: Rocket Lab (62/B), Tesla (62/B), Illumina, Inc. (61/B).
Next earnings
Q4 2026 · Expected
Coverage
Recursion Pharmaceuticals, Inc. · Q3 2026 reported Nov 2, 2026 (AMC) · Score 44 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.