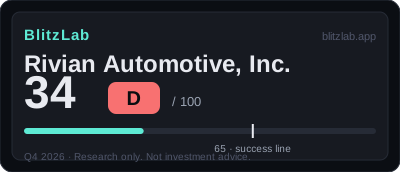
Rivian Automotive, Inc. — Blitz Index 34 (D)
Rivian scores 34 — R2 shipments and a record quarter prove the second curve has started, while negative auto gross margin and a 6-quarter runway cap the score.
Last re-scored: October 29, 2026.
Confidence: Medium · Category: frontier
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 16 / 25 | TTM revenue $5,883M; Q3 deliveries 19,248 (quarterly record, +45.8% YoY) — but 2025 deliveries fell −18.1% |
| B · Moat | 24 / 60 | Direct sales (39 Spaces, 100 service centers), Amazon van channel, VW JV software licensing — but no dealer network and US·Canada consumer sales only |
| C · Creative destruction | 8 / 15 | Adventure EV truck/SUV category creation + Amazon van electrification — small scale vs the whole auto order |
| D · BlitzFailing | −14 | Auto gross margin −4.8% (−12.9% ex-credits); H1 FCF −$1,924M; Class B 10-vote founder control; 3 recalls |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 40 · Speed 64 · Creative 53.3.
Watch item
Gates: G1 ✓ (second-curve evidence — R2 shipments, record quarter, guidance reaffirmed; LCID-distinguished) · G2 ✓ (borderline estimate — narrow US+Canada EV truck/SUV/van wedge). 32 points below the threshold — first score. Demerits −14, one point from the FLAG threshold (15).
Strengths
- R2 in production (Apr 2026) → external deliveries (Jun 9, 2026) → Q3 record 19,248 deliveries — the second curve in physical evidence
- Software + services gross margin +40.1% and 3× revenue (VW JV) — a second engine exists
- Amazon vans 40,000+ and 1B miles; RAN 1,000+ ports — commercial and infrastructure proof
- FY2026 delivery guidance 65,000–70,000 reaffirmed — the company is not retreating
- Conditional capital lines: VW up to $1.5B remaining, Uber up to $950M, DOE $4.5B — externally validated
Concerns
- Auto gross margin −4.8% (−12.9% ex-credits) — manufacturing economics unproven
- H1 FCF −$1,924M burn; 10-Q states additional fundraising is needed; shares +19.4% YoY dilution
- Q4 needs +20–47% over Q3 to hit guidance — R2 mix undisclosed
- 3 recalls (98,828 rear camera; 34,824 EDV seatbelt; 14 R2 battery fasteners) + tariff exposure + $7,500 credit expiry
- Class B 10-vote founder control; CFO resignation (Aug 27, effective Oct 30); controller departure reported
Research notes
Thesis: the second curve is real, and the scale is not yet proven
Rivian Automotive, Inc. (NASDAQ: RIVN) scores 34 out of 100 under BlitzLab v1.0, a grade of D, in its first scoring. The arithmetic is Speed 16 out of 25, Moat 24 out of 60, Creative Destruction 8 out of 15, and Demerits of minus 14, for a total of 16 plus 24 plus 8 minus 14 equals 34. That is 31 points short of the 65-point threshold, and the demerit total of 14 sits one point below the 15-point FLAG threshold, a near miss noted in the same terms as the earlier STUB case. On the three-axis radar conversion, Moat stands at 40.0, Speed at 64.0, and Creative Destruction at 53.3, all on a 100-point scale.
The score tells a story in two acts. The first act, built on the R1 line, stalled and then went into reverse: deliveries fell from 51,579 vehicles in 2024 to 42,247 in 2025, a decline of 18.1 percent, while automotive revenue fell 14.6 percent. The second act, built on the R2, has begun in a way that can be checked against physical evidence rather than promises alone. R2 mass production began in April 2026, deliveries to outside customers began on June 9, 2026, and third-quarter 2026 deliveries reached 19,248 vehicles, a quarterly record and a 45.8 percent increase year over year. Full-year 2026 delivery guidance of 65,000 to 70,000 vehicles was reaffirmed rather than withdrawn. Total revenue, which grew 8.4 percent in 2025 after 12.1 percent in 2024, accelerated to 19.5 percent growth in the first half of 2026 and 27.2 percent in the second quarter alone. The direction of growth has turned, and the score for growth, A1 at 7 out of 10, reflects exactly that mixture: the direction is right, the magnitude is not yet established, and the 2025 reversal plus the uncertainty of meeting full-year guidance hold the number down.
Both gates pass, and the first of them is where this scoring draws its most important distinction. Gate G1, which asks whether growth continues or a second growth curve exists, passes on second-curve evidence that is labelled estimated. The contrast drawn in the score file is with the LCID precedent, where the second curve was judged to be entirely unverified and the gate failed. Rivian differs because R2 has shipped, set a quarterly delivery record, and kept its guidance intact. The file is careful about what this does and does not establish: the curve has entered the verification stage, but its scale is not yet demonstrated. Meeting the full-year guidance requires fourth-quarter deliveries of 23,193 to 28,193 vehicles, which is 20 to 47 percent more than the third quarter delivered. That fourth-quarter test is the single most consequential near-term question for this company, and the score file names it as such: if the R2 ramp bends at this point, the curve logic itself weakens, and the milestones attached to conditional capital slip with it.
Gate G2, which asks whether the ten-year ceiling of a new market is at least ten times current revenue, also passes, again labelled estimated and sensitive to assumptions. The bar is approximately 58.8 billion dollars, ten times trailing-twelve-month revenue of 5,883 million dollars. The range is deliberately kept narrow: the United States and Canadian markets for electric trucks, SUVs, and vans covering the R1T, R1S, R2, and EDV and RCV commercial vans. The global automobile market, on the order of 3 trillion dollars, is explicitly excluded from the range. Today's United States electric vehicle market is approximately 1.275 million vehicles per Cox Automotive's 2025 outlook, cited via reporting, at roughly 55,000 dollars per vehicle, or roughly 70 billion dollars in total, of which Rivian's segment is about two-thirds. The ten-year ceiling assumes only a gradual rise in electric vehicle share: 15 percent of a 16-million-vehicle market is about 2.4 million vehicles at 50,000 dollars, roughly 120 billion dollars, with Rivian's segment at roughly 80 billion dollars, above the bar. The pass is fragile by its own terms: if the United States electric vehicle market stagnates for a decade, it does not pass, and the outcome depends on policy and demand variables. A supporting arithmetic check is offered on capacity: trailing-twelve-month deliveries of 45,505 vehicles times ten equal 455,050 vehicles per year, against expanded Normal capacity of roughly 215,000 vehicles plus an initial 300,000 from the Georgia plant, about 515,000 vehicles per year, which covers the requirement arithmetically but assumes full utilisation and demand.
The classification is GROWTH on trailing-twelve-month revenue of 5,883 million dollars, and confidence in the scoring is rated medium: the second-quarter 2026 Form 10-Q filed with the SEC was reviewed directly, while some fiscal 2025 Form 10-K figures reached the file through secondary summaries and carry a confirmation-needed label. That label is preserved here wherever it applies, as is the confirmation-needed flag on the company's CIK number, 1874178, which was confirmed from an SEC EDGAR archive path rather than a direct lookup of the company tickers file.
Speed: a recovery with a quarterly test attached
Speed totals 15 out of 25, the strongest of the three axes in relative terms, and each of its four items tells a different part of the recovery story. A1 growth, at 7 out of 10, has been covered above: total revenue growth of 8.4 percent in 2025, 19.5 percent in the first half of 2026, and 27.2 percent in the second quarter, with third-quarter deliveries up 45.8 percent year over year to a quarterly record. The score is held back by the 2025 delivery decline of 18.1 percent and by the fourth-quarter delivery requirement of 20 to 47 percent above the third quarter.
A2 capital velocity, at 3 out of 5, measures whether the company can fund its own speed. Cash plus short-term investments stood at 5,310 million dollars at June 30, 2026, and a July offering added approximately 1.3 billion dollars. Beyond that, conditional capital lines exist at scale: up to 1.5 billion dollars remaining from Volkswagen, up to 950 million dollars remaining from Uber, and 4.5 billion dollars from the Department of Energy, with the first draw expected in early 2027 and subject to conditions. The other side of the ledger is stated plainly in the company's own filing: the second-quarter 10-Q says additional fundraising is needed. Shares outstanding rose 19.4 percent year over year, a continuing dilution cost of funding growth with equity. The capital is real, but so is the dependence on capital that has not yet been unlocked.
A3 hiring and productivity, at 3 out of 5, is scored conservatively because the evidence pack contains no headcount or per-employee productivity figures, so those dimensions could not be measured. What can be measured is manufacturing scaling: third-quarter production reached 19,751 vehicles, also a quarterly record, with the R2 line at the Normal plant running. Production and delivery records in the same quarter are the concrete form that scaling evidence takes here, and the absence of workforce data is why the score stops at 3 rather than reaching higher.
A4 share velocity, at 3 out of 5, reflects the same early-stage position. Third-quarter deliveries set a record, the Amazon van fleet exceeds 40,000 vehicles with more than 1 billion miles driven, and the Rivian Adventure Network, or RAN, exceeds 1,000 charging ports. Against that, the United States electric vehicle market share is only about 3.5 percent, calculated as 45,505 trailing-twelve-month deliveries against a 1.275-million-vehicle market. Rivian is still at the beginning of the share game, not in the middle of it, and the score reflects a company winning records from a small base.
Moat: distribution and software against a missing network effect
Moat totals 24 out of 60, the weakest axis in absolute terms, and its composition explains why the total score is a D despite a genuine growth recovery. B1 network effects, at 6 out of 18, starts from a blunt finding: there is no true user network effect here. What exists is a seed. The RAN charging network, with more than 1,000 ports, runs at 98 percent uptime, and 40 percent of its sessions come from non-Rivian vehicles, which is the early shape of an open network. Separately, the Volkswagen joint venture licenses zonal architecture and software, which spreads Rivian's technology into an ecosystem beyond its own vehicles. Both are real, and both are small in revenue contribution, which is why the score is 6 rather than higher. A network that other drivers use and a software stack that another manufacturer licenses are the beginnings of a moat, not the moat itself.
B2 distribution scalability, at 7 out of 18, is the strongest moat item and still less than half its maximum. Rivian sells directly, with 39 Spaces retail locations and 100 service centres, and it has two additional channels that a direct-sales carmaker would not normally possess: the Amazon van channel and software distribution through the Volkswagen joint venture. The discounts are structural. Direct sales without a dealer network constrains how fast service can scale, consumer sales are limited to the United States and Canada, and no schedule for consumer entry into Europe has been disclosed. Distribution can reach the customers Rivian already serves, but it has not yet shown it can reach the next market.
B3 market size, at 8 out of 12, follows directly from the G2 pass on a narrow range, with points withheld because the pass depends on electric vehicle adoption expanding and because Rivian's segment is only part of the total electric vehicle market. The score rewards a ceiling that clears the bar without pretending the ceiling is the whole market.
B4 gross margin, at 3 out of 12, is the single most damaging item in the entire scoring, and it deserves the emphasis the score file gives it. Consolidated gross margin was positive 9.8 percent in the first half of 2026, but automotive gross margin was negative 4.8 percent, and excluding regulatory credits it was negative 12.9 percent. Vehicle manufacturing still loses money. Software and services gross margin of positive 40.1 percent is what holds the consolidated figure above water, and software and services revenue tripled with the Volkswagen joint venture. The structure is therefore a company whose vehicles are sold at a manufacturing loss while a second engine, software and services, carries the consolidated margin. Until vehicle economics are demonstrated, B4 stays at 3, and with it the total score stays low. This is the second of the three key drivers in the score file, stated as plainly as it can be stated: cars are selling, but cars are not making money.
Creative destruction: a new category, a changed last mile, an unproven cost break
Creative Destruction totals 8 out of 15, a middle result that reflects genuine category creation without yet demonstrating irreversible change at scale. C1, the order being replaced, scores 3 out of 5. Rivian pioneered the adventure electric truck and SUV category and is attempting to change the last-mile delivery order through the electrification of Amazon's van fleet. The limit is scale: against the whole automobile industry, Rivian's size is still small, and a category that is new is not yet a category that has displaced the old order.
C2, irreversible behaviour change, also scores 3 out of 5. The evidence on the commercial side is concrete: more than 40,000 Amazon vans covering more than 1 billion miles, plus the RAN charging network and a software stack designed to lock customers in. On the consumer side, the demonstration of behaviour change that cannot easily be reversed is still only partial. A fleet operator that has electrified tens of thousands of vans has changed its operations in a durable way; whether individual consumers have changed in an equally durable way is not yet established by the evidence in the file.
C3, cost-structure change, scores 2 out of 5, the lowest of the three. The claim is that zonal architecture and vertical integration change the cost structure of building a vehicle. The evidence against the claim is the automotive gross margin itself: still negative, which means no cost collapse has been demonstrated. A cost advantage that cannot be seen in unit economics is an assertion, not a result, and the score treats it accordingly.
Taken together, the three items describe a company that has opened a new category and changed one large customer's operations, but has not yet broken the cost structure of its own industry. That is consistent with the Blitzscaling fit analysis in the score file, which places Rivian at the start of a second Blitzscaling act: the first act, built on R1, ended in stagnation, and the second act, built on R2, has only just begun. The score of 34 and grade of D are described in the file as fitting that position, a score for the prologue of a second act, with A1 and B4 identified as the items most likely to move first if the curve proves its scale.
Deductions and risks: cash burn, credit dependence, governance, and recalls
Demerits total minus 14, one point short of FLAG territory, and each of the four items captures a distinct risk. D1 debt, at minus 6 out of a possible minus 10, is the heaviest. Long-term debt of 4,444 million dollars is covered by cash plus short-term investments of 5,310 million dollars, together with the July offering, so the debt itself is not the problem. The problem is the rate at which cash is consumed: free cash flow was minus 1,924 million dollars in the first half of 2026, implying a runway of roughly 5.5 to 6.3 quarters on that burn rate, or around six quarters in the score file's summary phrasing. The company's own filing states that additional fundraising is needed, and the conditional capital of 6.95 billion dollars from Volkswagen, Uber, and the Department of Energy combined only opens when milestones are met. The file notes that this deduction is one point lighter than the NBIS deduction of minus 7, because the debt ratio is lower even though the burn rate is fast. Cash exists and time is short, and that tension is the third key driver.
D2 revenue quality, at minus 3, records no restatement or audit issue, and the file is explicit that this is not an accounting irregularity. The deductions come from three features of reported results. Regulatory credits contributed 106 million dollars in the second quarter, a large part of the improvement in automotive gross margin. Revenue recognition in the Volkswagen joint venture is complex. And the first-quarter net loss was distorted by a one-time gain of positive 506 million dollars from the disposal of Mind Robotics. None of these is fraud; together they mean that headline results flatter underlying vehicle economics, and the score marks that.
D3 governance, at minus 3 out of a possible minus 5, reflects a dual-class structure in which Class B shares carry ten votes each, giving the founder a controlling structure. The scale of founder Scaringe's voting share is labelled confirmation-needed in the score file, and that label is preserved here rather than resolved by assertion. Two additional factors are recorded: the chief financial officer's resignation was announced on August 27, 2026, effective October 30, 2026, as disclosed in a Form 8-K, and the departure of the controller was reported in press coverage, which is labelled press-reported here. Leadership turnover in the finance function during a period of heavy cash consumption is a governance observation, not a conclusion about any individual, and the score keeps it at that level.
D4 regulatory and social cost, at minus 2, gathers the external frictions. Three recalls are recorded: 98,828 vehicles for a rear camera issue, 34,824 EDV vehicles for a seatbelt issue, and 14 R2 vehicles for a battery fastening issue, with over-the-air updates part of the response and recall frequency itself the reason for the deduction. Tariff exposure applies through Section 232 duties of 25 percent plus offsetting measures. The 7,500-dollar tax credit has expired, creating a demand headwind. An IPO class action received final approval in May 2026. Each of these is a cost imposed from outside the company's control, and together they justify a modest deduction rather than a severe one.
The Blitzscaling fit section of the score file adds a structural observation worth carrying into this account. Rivian's main levers are product, in the form of R2 opening a mass market, and capital, in the form of partner funding. Its secondary levers are distribution, through vans and the charging network, and platform, through software licensing. Its weak lever is network effects, where the open RAN is only a seed. The trade of speed for efficiency was paid for with other parties' money: a Volkswagen joint venture on the scale of 5.8 billion dollars, an Uber arrangement on the scale of 1.25 billion dollars, and 4.5 billion dollars from the Department of Energy, building factories with partner capital at the price of dilution and milestone dependence. That is the classic Blitzscaling bargain, and Rivian has taken it in full.
What to watch: the fourth quarter, the margin, and the milestones
Several markers follow directly from the score file, and each is stated here without an anticipated outcome. The third-quarter 2026 financial results were due on October 29, 2026, after the scoring date of October 26, 2026, and are therefore excluded from this scoring; they appear here only as a future marker. Fourth-quarter deliveries will show whether the 65,000-to-70,000-vehicle full-year guidance is met, which requires 23,193 to 28,193 vehicles in the quarter. The R2 mix within deliveries has not been disclosed, and its disclosure, or continued non-disclosure, will matter for judging whether the second curve is broadening or narrowing. Automotive gross margin excluding regulatory credits, at negative 12.9 percent, will show whether vehicle economics are improving or whether the consolidated margin continues to depend on software and services at positive 40.1 percent. Cash consumption against the first-half free cash flow figure of minus 1,924 million dollars will show whether the runway of roughly six quarters is lengthening or shortening, and whether the company's stated need for additional fundraising is met from the July offering's proceeds, from operations, or from new fundraising. The conditional capital lines from Volkswagen, Uber, and the Department of Energy, totalling up to 6.95 billion dollars, will show which milestones are met and which slip, with the Department of Energy's first draw expected in early 2027. The chief financial officer transition effective October 30, 2026, the frequency of further recalls, tariff developments, and the demand effect of the expired 7,500-dollar credit are further markers, each recorded in the score file as an open item rather than a forecast.
For context only, and not as scoring evidence, the company's 2026 guidance also includes an adjusted EBITDA loss of 1.8 to 2.0 billion dollars and capital expenditure of 1.7 to 1.8 billion dollars. The score file states that guidance is an outlook, not a basis for scoring, and this draft preserves that distinction: guidance describes what the company expects, while the score describes what has already been demonstrated.
Rivian's score of 34 and grade of D therefore reads less as a verdict on ambition than as a measurement of proof. The second curve has shipped, set records, and kept its guidance, which is why both gates pass and why this scoring differs from the LCID precedent. The vehicles lose money before credits, the cash runway is around six quarters, and the fourth quarter must deliver 20 to 47 percent more than the third. A company at the prologue of its second act can earn a higher score only by converting those three facts: scaling R2 deliveries, demonstrating automotive gross margin without credits, and extending its runway on its own economics rather than on conditional capital. Until then, the score stands as a record of a recovery that has begun and a scale that has not yet been proven.
More Frontier companies
Other Frontier names on the Blitz Index, highest score first: Rocket Lab (62/B), Tesla (62/B), Illumina, Inc. (61/B).
Next earnings
Q4 2026 · Expected
Coverage
Rivian Automotive, Inc. · Q3 2026 due Oct 29, 2026 (AMC, confirmed) · Score 34 · Grade D
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.