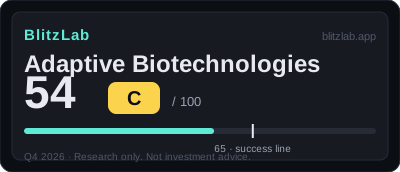
Adaptive Biotechnologies — Blitz Index 54 (C)
A+B+C = 59 clears nothing on its own — then D −5 leaves it at 54. Core MRD +36.8%, first profitable quarter, and the cleanest balance sheet among the diagnostics scored.
Last re-scored: November 4, 2026.
Confidence: High · Category: frontier
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 18 / 25 | MRD +45.9% in FY2025 and +36.8% in 9M 2026; MRD services +44.4% in Q3; clonoSEQ volume +46% |
| B · Moat | 30 / 60 | 5M+ TCR-antigen matches in the data flywheel; Medicare $2,007/test and 300M+ lives covered; 74–76% gross margin |
| C · Creative destruction | 11 / 15 | NGS MRD (10^-6) replacing flow cytometry (10^-4); NCCN maintenance-testing framework and IMWG cure definition lock MRD into myeloma care |
| D · BlitzFailing | −5 | Net cash ~+$55M vs $345M 0% converts due 2031; no material litigation; single-class stock, one vote per share |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 50 · Speed 72 · Creative 73.
Watch item
Gates: G1 ✓ · G2 ✓. 11 points below the threshold — first score. No FLAG: deductions of only 5 points. The Genentech exit hides the blitz — total revenue fell 10.7% in Q3 while the core grew 44%.
Strengths
- FY2026 MRD revenue guidance $276–286M (+30–35%) — the print that proves the blitz is intact
- Q3 2026 first profitable quarter: net income +$2.8M, adjusted EBITDA +$14.3M, FCF +$7.7M
- clonoSEQ volume +46% in Q3 (39,587 tests); NCCN maintenance-testing framework + IMWG cure definition lock MRD into myeloma care
- Gross margin 74–76% with operating leverage emerging — opex +1% in Q3 while MRD grew 28%
Concerns
- Genentech is gone — $41.3M/year of collaboration revenue vanished; MRD is ~90% of TTM revenue
- Immune Medicine shrinking (−69.5% in Q3) and being separated — no second engine yet
- Still loss-making on a 9M basis (−$57.2M net); the Q3 profit is one quarter of evidence
- Medicare/MolDX pricing is the whole distribution — a reimbursement cut hits revenue directly; milestone lumpiness ($0 in Q3 vs $6.5M a year ago)
Research notes
Q3 2026 first score
Q3 2026 first score (10-Q and earnings release, Nov 4, 2026; quarter ended September 30, 2026): total revenue $83.9M (−10.7% YoY) — the headline is a Genentech mirage, because the terminated collaboration cost $33.7M of year-ago revenue while core MRD revenue rose 28% (services +44.4%) to $72.6M; excluding Genentech, total revenue rose 39%. MRD revenue 9M 2026 $205.8M (+36.8% YoY); FY2025 MRD $212.3M (+45.9%). clonoSEQ volume 39,587 tests in Q3 (+46% YoY), 108,293 in 9M (+43%). Net income +$2.8M — the first profitable quarter — with adjusted EBITDA +$14.3M and free cash flow +$7.7M; operating loss was just −$0.5M. Gross margin 76.2% in Q3 (74.0% in 9M). Cash and marketable securities $400.2M against $345M of 0% convertible notes due 2031 (net cash ~+$55M). FY2026 MRD revenue guidance raised to $276–286M (+30–35%). NCCN guidelines strengthened MRD testing in multiple myeloma and the International Myeloma Working Group's new definition of cure requires sustained MRD negativity at 10^-6. Gates: G1 passes on organic growth plus repeat purchase (monitoring cadence, ~4 tests per Medicare episode); G2 passes as an estimate — company-stated MRD TAM ~$6.2B is ~2.1x the $2.98B bar (10x TTM revenue of $298.0M), and all three independent vendor extrapolations to 2036 (~$3.9–10.4B) clear the bar, though the narrowest clears it by only ~31%. Score 54/C — 11 points below the 65 line, no FLAG (deductions −5). Sources: 10-Q Q3 2026, https://www.sec.gov/Archives/edgar/data/1478320/000119312526447411/adpt-20260930.htm ; 8-K Ex-99.1, https://www.sec.gov/Archives/edgar/data/1478320/000119312526447290/adpt-ex99_1.htm ; 10-K FY2025, https://www.sec.gov/Archives/edgar/data/1478320/000119312526076902/adpt-20251231.htm
Thesis: a blitz hidden inside a shrinking headline
Adaptive's third quarter reads like two companies. The one in the headline shrank 10.7%, because the Genentech collaboration that contributed $33.7 million a year earlier is gone. The one underneath grew 44% — MRD services, the clonoSEQ test, the volume of 39,587 tests, up 46%. Strip out Genentech and revenue rose 39%. The quarter also produced the company's first profit: net income of $2.8 million, adjusted EBITDA of $14.3 million, free cash flow of $7.7 million, on an operating loss of just $0.5 million. That is the blitz, and it is why the speed score is 18 of 25 even though the headline growth rate is negative.
The moat is real but mid-sized, at 30 of 60. The data flywheel is the strongest piece: more than 5 million TCR-antigen matches in a clinical immunomics database that grows with every test, already monetized through data licensing and a target-discovery agreement carrying up to $877.5 million in potential milestones. Distribution runs on reimbursement — Medicare at $2,007 per test, an $8,029 episode, coverage past 300 million lives — plus EMR integrations and a biopharma channel. Gross margin sits at 74–76%, and operating leverage is appearing: total operating expenses rose 1% in the quarter while MRD grew 28%. What keeps the moat at 50 rather than higher is that physicians choose clonoSEQ for accuracy, reimbursement and guidelines, not because other users make it better — there is no platform lock-in, and the addressable market is single-digit billions.
What distinguishes Adaptive from the other diagnostics scored is what is missing: deductions of only 5 points. The balance sheet is net cash — $400.2 million against $345 million of zero-coupon converts due 2031 — equity is positive, there is no material litigation, and the stock is single-class with one vote per share. The 54 is therefore a clean 54: a business score of 59 that falls 11 points short of the 65 line on the moat alone, not a good business dragged down by its structure. The risk is concentration, not contamination. Genentech's exit leaves MRD as roughly 90% of trailing revenue, Immune Medicine is shrinking and being separated, and the whole distribution rests on Medicare and MolDX pricing decisions. If MRD keeps growing at 30–45% and the Q3 profit becomes a trend rather than a quarter, the score's constraint is the moat — and the moat's next test is whether the NCCN framework and the IMWG cure definition turn MRD testing from a growth product into the standard of care.
More Frontier companies
Other Frontier names on the Blitz Index, highest score first: Rocket Lab (62/B), Tesla (62/B), Illumina, Inc. (61/B).
Next earnings
Q4 2026 · Expected
Coverage
Adaptive Biotechnologies Corporation · Q3 2026 reported Nov 4, 2026 · Score 54 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.