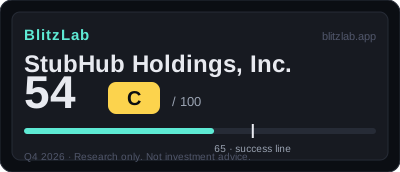
StubHub Holdings, Inc. — Blitz Index 54 (C)
StubHub scores 54 — the strongest moat in the batch (B 41) on two-sided ticket liquidity, held back by demerits of −13.
Last re-scored: October 25, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 16 / 25 | Q2 +33% and H1 +23.1% re-acceleration, but FY2025 revenue fell −1.4% and Q4 2025 fell −16% — only two quarters of reversal so far |
| B · Moat | 41 / 60 | Two-sided liquidity (B1 12) plus an 83% adjusted gross margin (company non-GAAP; no GAAP gross-profit tag) — but sales and marketing cost 54% of revenue |
| C · Creative destruction | 10 / 15 | Open resale and price discovery replace closed primary-only ordering for sold-out events — Ticketmaster's primary dominance caps displacement |
| D · BlitzFailing | −13 | Leverage 3.0× plus the FY2025 GAAP-vs-adjusted gap (SBC $1,447.7M incl. $1,400.7M IPO charge) plus Class B 100-vote shares and live regulatory risk |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 68.3 · Speed 64 · Creative 66.7.
Watch item
Gates: G1 ✓ (confirmed, with caveat — FY2025 revenue −1.4% masked GMS underlying +18%) · G2 ✓ (borderline estimate — take-rate-normalised, bar ≈ $19.4B). 11 points below the threshold — first score. Demerits −13, near the FLAG threshold (15).
Strengths
- Q2 2026 revenue +33% and H1 +23.1% — re-acceleration after the FY2025 −1.4% (take-rate cut plus Eras Tour base)
- Underlying GMS +18% in FY2025 and TTM GMS ~$10.0B — the marketplace, not the take rate, is growing
- Two-sided liquidity across 200+ countries and regions, with ~50% North America secondary share
- Primary Direct Issuance (MLB partnership) plus international GMS growing faster than North America
- IPO proceeds ~$1B funded $1.1B of debt reduction in 12 months; net leverage fell 4.5× → 3.0×
Concerns
- FY2025 GAAP net loss −$1.9B vs adjusted EBITDA $232M — a $1,400.7M IPO SBC charge plus a $479M valuation allowance
- Demerits −13 sit 2 points from the FLAG threshold (15) — any D-item deterioration triggers a watch
- Class B shares carry 100 votes each; founder Eric Baker holds >50% of votes (~88% computed)
- Sales and marketing was 54% of FY2025 revenue — distribution is bought, not viral
- FTC $10M settlement (Apr 2026) over all-in pricing, plus Q2 2026 fulfilment complaints and refund delays
Research notes
Thesis
StubHub Holdings, Inc. scores 54 out of 100, grade C, under the BlitzLab v1.0 model as of 25 October 2026. The arithmetic of that score tells the story before any narrative does: speed contributes 16 of 25, moat contributes 41 of 60, creative destruction contributes 10 of 15, and demerits subtract 13. The result sits 11 points below the 65-point threshold, so on this framework the company does not clear the bar. Yet the shape of the score matters more than the shortfall alone. This is not a company with a weak business and a clean record, nor a company with a brilliant business and a fatal flaw. It is a company whose strongest axis, the moat, is trailed closely by a demerit total that comes within two points of the FLAG threshold of 15. The score file's own summary phrase captures it well: a strong business with a heavy shadow.
StubHub, founded in 2000 and listed on the New York Stock Exchange in September 2025, operates a marketplace where fans buy and sell tickets to live events. Its revenue is the take it keeps from transactions, not the gross value of the tickets that change hands, and that distinction runs through almost every judgment in this assessment. Gross merchandise sales, the total value of tickets traded, can grow while reported revenue falls, and reported revenue can fall while the underlying trading activity strengthens. Anyone reading StubHub's recent results without that distinction will misread the company in both directions, first by overstating its decline and then by overstating its recovery. The scoring work here tries to keep the two apart.
The gate verdicts frame the rest of the analysis. Gate 1, product-market fit or a second growth curve, passes on a combination of evidence rather than on any single figure. Gate 2, a ten-year market ceiling at least ten times current revenue, passes only narrowly, on a press-reported and estimated basis, and with a warning attached that is as important as the pass itself. Both gates passing means the company earns a full scoring, but neither pass is comfortable, and the discomfort is informative. StubHub is a mature company, classified as such because its trailing-twelve-month revenue of $1,936.4 million exceeds $1 billion, and mature companies are judged here on whether their established position can still expand, not on whether they have found an initial audience. The question is not whether people want to resell tickets. They plainly do. The question is whether this particular marketplace can keep growing its trading activity, extend into primary issuance, and do so while carrying concentrated voting control, meaningful leverage, and live regulatory exposure.
The central tension of the StubHub story is a deliberate trade. In fiscal 2025 the company cut its take rate on purpose, accepting lower reported revenue in exchange for trading volume. Revenue fell 1.4 percent, from $1,770.6 million to $1,745.2 million, while headline gross merchandise sales rose 6 percent and, excluding the Eras Tour base, grew 18 percent on a company-reported basis. That is the kind of exchange that looks like failure in a revenue table and like strategy in a marketplace table, and the truth requires holding both tables at once. The reacceleration that followed gives the trade its retrospective justification: revenue rose 23.1 percent in the first half of 2026 and 33 percent in the second quarter of 2026 alone. Two quarters of reacceleration do not erase a year of decline, and the score reflects that restraint, but they do change the direction of the argument. StubHub enters this assessment as a company in a reacceleration phase, immediately after its initial public offering, with a second growth curve only just opening.
Moat: Two-Sided Liquidity Is the Business
The moat axis is StubHub's strongest, at 41 of 60, and its core is genuine two-sided liquidity. The marketplace operates across more than 200 countries and regions, and more than 40 million tickets were traded in 2024. Those two figures together describe something that is difficult to replicate by spending alone: a pool of buyers and sellers dense enough that a ticket listed here has a plausible chance of finding a buyer, and a buyer arriving here has a plausible chance of finding a ticket. For sold-out events in particular, liquidity concentrates, and concentration is itself the advantage. A fan holding a ticket to an event that cannot be bought elsewhere at the box office needs a place where other fans are already looking, and a fan looking for that ticket needs a place where other fans are already selling. Each side of the market makes the other side more valuable, and that mutual reinforcement is the classic network effect that the blitzscaling framework rewards most heavily. The network effect item scores 12 of 18, in the upper-middle of its range, which is a fair reflection of a real but bounded advantage.
The bound matters. Ticketmaster's dominance of primary ticketing sets a ceiling on StubHub's liquidity, because the primary channel controls the first sale of most tickets and therefore shapes what can ever reach the secondary market. Both buyers and sellers can also use multiple platforms, so neither side is locked in. A seller can list in more than one place, and a buyer can compare more than one place, which means StubHub's liquidity must be earned continuously rather than banked permanently. The score stops short of the top range for exactly this reason: the liquidity is real, it is deep for sold-out events, and it is not exclusive. It is a moat with open gates at both ends, and the company's task is to keep enough flow passing through its own gates that the network remains the most liquid option even when it is not the only option.
Distribution extends the moat without yet transforming it. The marketplace itself remains the primary channel, but the company is adding layers around it: Direct Issuance, its primary issuance offering developed with partners including Major League Baseball from the 2026 season; vivenu; and open distribution in university sports. Each of these is an attempt to move closer to the original sale rather than waiting for tickets to arrive on the secondary market, and each, if it scales, would change the character of the business from a resale venue into a fuller ticketing platform. The distribution item scores 10 of 18, held back by a single stubborn fact: adjusted sales and marketing expense in fiscal 2025 was $943 million, or 54 percent of revenue. That is paid acquisition, not viral distribution. A marketplace that must spend more than half its revenue to bring buyers and sellers to the venue has distribution that works, but it does not have distribution that spreads on its own. The distinction between buying traffic and earning traffic is the difference between a moat that deepens with scale and a cost line that grows with scale, and StubHub currently sits on the expensive side of that line.
Market size, the third moat item, scores 9 of 12, and it carries the same qualified character as the Gate 2 verdict it mirrors. The online event ticket market is estimated in market-research reporting at $88.33 billion in 2025, rising to $130.38 billion in 2030. Against a bar of approximately $19.4 billion, ten times trailing-twelve-month revenue, the 2030 total is roughly 6.7 times the bar, which on a gross-total basis would appear comfortable. But StubHub does not keep the gross total; it keeps a take of around 19 percent. Normalising for that take changes the picture sharply: reaching the bar would require gross merchandise sales of roughly $102 billion, or about 78 percent of the projected 2030 pool. That is why the score is 9 rather than higher, and why the pass is explicitly labelled as borderline. The market is large enough, but only if several things happen together: the market keeps growing beyond 2030, primary issuance contributes, and revenue beyond the ticket take, such as advertising and Direct Issuance, develops. No single one of those paths is sufficient on its own.
The final moat item is the economics of the take itself. Adjusted gross margin was 83 percent in fiscal 2025 on a company non-GAAP basis, up 200 basis points year on year, with the fourth quarter up 700 basis points against 76 percent in the prior-year period, an improvement the company attributes in part to the removal of minimum guarantees. An 83 percent margin is the signature of a marketplace that keeps a slice of each transaction without holding inventory or producing the underlying event, and it scores 10 of 12. The qualification attached to it must be preserved exactly: this is an adjusted, company non-GAAP figure, never a GAAP gross profit figure. Because revenue is recorded net of the ticket value, the GAAP gross-profit tags in the company's structured filings are empty, so there is no GAAP equivalent to quote. The margin describes a genuinely high-margin structure, but it describes it on the company's own adjusted basis, and any account of StubHub that drops that label overstates what the filings themselves confirm.
Speed: Reacceleration With a Short Track Record
Speed scores 16 of 25, and its internal pattern is uneven in a way that reflects the company's recent history. Growth itself scores 6 of 10. The second quarter of 2026 grew 33 percent and the first half grew 23.1 percent, which is real reacceleration by any reading, but fiscal 2025 fell 1.4 percent and the fourth quarter of 2025 fell 16 percent, reflecting the Eras Tour base effect and the removal of primary revenue. Those declines remain inside the recent twelve-month trajectory, so the growth score is deliberately restrained. A higher score would require more than two quarters of reversal, and the framework refuses to grant it early. The underlying gross merchandise sales base, up 18 percent in fiscal 2025 excluding Eras on a company-reported basis, supports the view that trading activity never truly stalled, but the score judges reported revenue momentum as well as underlying activity, and on that combined reading 6 is the honest number.
Capital velocity scores 4 of 5, the strongest speed item, and it is the clearest evidence that the public listing changed the company's financial posture. Net proceeds from the initial public offering were $758 million, and together with the Series O financing the total raised was approximately $1 billion. Over twelve months the company reduced debt by $1.1 billion, net leverage improved from 4.5 times to 3.0 times, first-half 2026 free cash flow reached $600.2 million, and second-quarter free cash flow reached $309.7 million. Fundraising, debt reduction, and cash generation arriving together is the triple demonstration the framework looks for, and it is present here. The single point withheld reflects the leverage that remains: at 3.0 times, the balance sheet is improved, not unburdened, and the capital story is one of repair in progress rather than repair complete.
Hiring and productivity scores only 2 of 5, and the low score is a statement about evidence rather than about performance. The company employed approximately 900 full-time staff at 31 December 2025, a figure confirmed in its annual filing, which implies trailing-twelve-month revenue per employee of $2.15 million on a calculated basis. That absolute productivity level is high. But only a single year of employment data is confirmed, so the pace of a hiring blitz cannot be established, and during the fiscal 2025 revenue decline there is little basis for claiming productivity improvement. The score stays conservative despite a strong confirmed headcount figure, because the framework rewards demonstrated hiring velocity, not a single attractive ratio, and the data does not yet support a stronger claim.
Share velocity scores 4 of 5 on a multi-layered set of observations. North American secondary share is approximately 50 percent on a press-reported basis from a fourth-quarter 2025 company call, overseas gross merchandise sales, approximately 15 percent of the total, are growing faster than North American sales, and primary share is beginning through Major League Baseball Direct Issuance. That is share momentum on three fronts at once: a leading secondary position at home, faster growth abroad, and an opening position in primary. The point withheld reflects the absence of a filing-confirmed absolute share figure; the leading share estimate rests on company remarks as reported in the press, not on a regulatory disclosure, and the score respects that boundary. Even with that restraint, the direction is clear: StubHub is not merely holding a position, it is extending the geography of its trading and the stage of the ticketing chain at which it participates.
Creative Destruction: Changing How Sold-Out Events Are Traded
Creative destruction scores 10 of 15, and its three items describe a genuine but incomplete transformation of an old order. The order being displaced scores 4 of 5. Before open resale marketplaces, a fan who could not buy from the primary seller faced a closed world: the box office, the authorised outlet, or informal brokers operating without transparent pricing. StubHub's model replaces that closed ordering with open resale between fans and with price discovery visible to both sides. For sold-out events above all, the way a ticket changes hands has changed, from a private arrangement to a public market. The point withheld reflects the fact that the displacement is not one-sided: Live Nation and Ticketmaster still dominate primary ticketing, so the old order survives alongside the new one and constrains it. This is transformation within a system the incumbent still largely controls, not replacement of that system.
Irreversible behaviour change scores 3 of 5. Resale has become the default expectation for sold-out events, and the shift toward full-price transparency is under way, meaning buyers increasingly expect to see the complete price rather than discovering additions late in the process. Both are real behavioural shifts, and both have the character of changes that are difficult to reverse once fans have experienced them. But the score holds back for two reasons grounded in recent reporting. Second-quarter 2026 fulfilment complaints and refund delays, on a press-reported basis, show friction in the very experience that is supposed to feel frictionless, and resale itself remains structurally reversible because it depends on regulation and platform policy. A marketplace whose existence depends on rules that can change, and on the policies of the primary platforms that feed it, cannot claim the same irreversibility as a technology that replaces its predecessor outright. Behaviour has changed, but the ground under that behaviour can still move.
Cost-structure change scores 3 of 5 on a similar split. The box office and broker distribution costs that once stood between a ticket holder and a buyer have been collapsed by the marketplace, and Direct Issuance takes the idea further by turning primary distribution itself into something delivered through an interface rather than through a proprietary channel. That is a genuine change in how distribution costs are structured for the participants. But StubHub's own sales and marketing cost, at 54 percent of revenue, means the collapse in its customers' distribution costs has not become a collapse in its own cost structure. The company has made trading cheaper for fans while remaining expensive to run as a business, and the score reflects that asymmetry rather than resolving it in either direction.
Deductions and Risks: Thirteen Points, Four Directions
The demerit total of negative 13 is the number that prevents this assessment from reading as a straightforward success story, and it arrives from four directions at once. No single deduction dominates; instead, four moderate deductions combine into a total that sits close to the FLAG threshold. That breadth is itself a risk signal, because it means deterioration in any one area, rather than a crisis in one, could push the company into FLAG territory.
Debt deducts 3 points. Total debt is approximately $1.4 to $1.5 billion, net leverage stands at 3.0 times trailing-twelve-month adjusted earnings before interest, taxes, depreciation and amortisation, improved from 4.5 times at 31 December 2025, and fiscal 2025 interest was approximately $140 million. The direction is favourable and the capital actions behind it are documented, but the level remains in leveraged territory. Alongside the debt, seller payables of $1.2 billion represent a working-capital burden that belongs in any honest picture of the balance sheet: money owed to sellers is part of operating a marketplace at scale, and it constrains flexibility even when it is not borrowed money in the conventional sense. The deduction is therefore not a judgment that the debt is unmanageable; it is a judgment that leverage remains a live constraint on a company still early in its post-listing deleveraging.
Revenue quality deducts 3 points, and here the numbers require careful handling because they invite misreading. Fiscal 2025 stock-based compensation was $1,447.7 million, including $1,400.7 million of one-time initial-public-offering expense, and a valuation allowance of $479 million contributed to a GAAP net loss of negative $1.9 billion, set against adjusted earnings before interest, taxes, depreciation and amortisation of $232 million. Those are disclosed distortions, not hidden ones, and the distinction matters: the company did not conceal the one-time items, and a reader of the filings can trace them. But the gap between the GAAP result and the adjusted result is extreme, and extreme gaps invite misreading by anyone who sees only one side. A reader who sees only the loss concludes the business is collapsing; a reader who sees only the adjusted figure concludes it is serene. Neither is accurate, and the deduction prices the gap itself rather than alleging misconduct. The score file is explicit that the one-time character of the items is clear, which is why the deduction stops at 3 rather than going further.
Governance deducts 4 points, the largest single deduction, and it is the item that most clearly separates StubHub from a conventional widely held public company. Class B shares carry 100 votes per share, and at 27 February 2026 there were 331,974,119 Class A shares and 24,750,000 Class B shares. The annual filing records Baker's voting power as greater than 50 percent and identifies the company as a controlled company, and a calculation assuming all Class B shares are held by one holder produces approximately 88 percent of votes, from 2,475 million votes out of 2,807 million, consistent with press-reported estimates of 88 to 90 percent. The scoring framework applies its highest observed anchor range, 74 to 85 percent, at negative 4, and deliberately does not extrapolate to negative 5 for a figure above that range. That restraint is noted as a candidate question for a future model version, but under the frozen model the deduction is 4. Whatever the precise percentage, the governance reality is concentration at a level where public shareholders hold an economic interest but not control, and that concentration colours every other judgment about the company's future, because strategic choices will be made by a controlling holder rather than by a contestable shareholder base.
Regulation and social cost deduct 3 points, and this is the deduction most likely to move first. A Federal Trade Commission settlement of $10 million in April 2026, on a press-reported basis, related to the failure to disclose all-in pricing, sits alongside state-by-state resale regulation, rules governing automated purchasing, second-quarter 2026 fulfilment complaints and refund delays on a press-reported basis, and the ever-present competitive and antitrust risk associated with Ticketmaster. None of these is a company-ending event, but together they describe a regulatory and trust environment that is active rather than settled. Resale marketplaces operate at the intersection of consumer protection, event policy, and competition law, and each of those fronts can produce costs, constraints, or reputational damage without warning. The deduction is set at 3 rather than 2 precisely because these risks are current, not hypothetical, and the fulfilment complaints show that trust is not an abstract concern but a reported operational issue.
The blitzscaling lens sharpens the risk picture into a single sentence from the score file: if governance and regulation erode liquidity, the network becomes a liability rather than a moat. Blitzscaling theory holds that speed creates the moat, but StubHub's speed is running on ground shadowed by concentrated voting control and regulatory exposure. Trust events that repeat, fulfilment failures that recur, or regulatory constraints that tighten could move liquidity to competitors, and because both sides of this market can use multiple platforms, liquidity that leaves is not easily recovered. That is the mechanism by which a strong network effect could weaken, and it is why the demerit total deserves more attention than its size alone suggests.
What to Watch
The calendar gives this assessment its next checkpoints without permitting any prediction about them. Third-quarter 2026 results are scheduled for 10 November 2026, a date announced by the company before the scoring date, and that quarter is the first in which Direct Issuance can be observed as an operating reality rather than an announced initiative. The score file identifies it as the first demonstration quarter for Direct Issuance and the first judgment date for the near-FLAG demerit position, and both framings are useful as markers. What matters is not any anticipated outcome, which this assessment does not offer, but which questions the quarter will put to the evidence: whether primary issuance contributes visibly, whether overseas growth continues to outpace North America, whether the reacceleration in reported revenue extends beyond two quarters, and whether any demerit item moves in either direction.
Beyond that quarter, the watch list follows directly from the scoring items. On the moat side, the development of revenue beyond the ticket take, including advertising and Direct Issuance, is the variable that determines whether the borderline market-size pass can ever become comfortable, since the take-normalised arithmetic leaves no room for a single-path success. On the speed side, the extension of the revenue recovery beyond the first half of 2026, and the emergence of a longer employment series that would allow hiring velocity to be judged on evidence rather than on a single year, are the two developments that could lift the most restrained speed scores. On the cost side, the trajectory of sales and marketing spending as a share of revenue will show whether distribution is becoming more efficient or remains a purchased advantage. And on the risk side, the governance question is structural rather than quarterly: concentrated voting control does not change with a single earnings release, so the relevant watch item is not a number but any change in how that control is exercised, alongside any further regulatory action or trust incident.
StubHub at 54 is therefore best understood as a company that has proved its marketplace works, is proving its revenue can reaccelerate, and has not yet proved that its growth can outrun the weight it carries. The liquidity is real, the margin structure is strong on its adjusted basis, the capital repair is under way, and the second curve has opened. The leverage is still material, the gap between reported and adjusted results still invites misreading, voting control remains concentrated at the highest observed level, and regulation and trust remain live exposures. Eleven points separate this score from the threshold, and the distance is not a rounding error to be wished away. It is the measured space between a marketplace that functions well and a blitzscaling company that has cleared every test the framework sets.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Nov 10, 2026 · After close · Confirmed
Coverage
StubHub Holdings, Inc. · Q3 2026 due Nov 10, 2026 (AMC, confirmed) · Score 54 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.