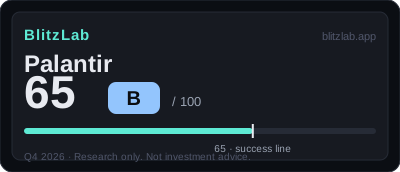
Palantir — Blitz Index 65 (B)
Exactly on the success threshold. A B-grade business, graded on moat, speed and risk.
Last re-scored: October 11, 2026.
Confidence: High · S&P 500 · Nasdaq-100 · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 21 / 25 | Q2 +92.8% YoY, 12 quarters accelerating; $1.7M revenue/employee; decision-intelligence #1 (reported) |
| B · Moat | 40 / 60 | In-customer lock-in is strong (NDR 157%) but cross-customer network effects are weak; 87% gross margin |
| C · Creative destruction | 10 / 15 | Replacing legacy IT procurement and SI consulting — in progress, concentrated in government/defense |
| D · BlitzFailing | −6 | Class F founder control (−3); NHS £330M break clause, France exit, global protests — structural, no revenue hit yet (−3) |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 67 · Speed 84 · Creative 67.
Watch item
Gates: G1 ✓ (sustained growth + second curve) · G2 ✓ (AI software spend dwarfs the 10× bar). No watch flag (demerits 6 < 15).
Strengths
- 12 quarters of accelerating growth + Rule of 40 at 155% — historic numbers
- NDR 157%: the ontology lock-in, quantified
- AIP as second growth curve, sovereign AI as a third front
- $1.7M revenue per employee — structural productivity vs traditional SI
Concerns
- Valuation: ~$475B ≈ 59× FY2026 revenue guidance — demands flawless execution
- 42% of revenue from the US government + European political risk (NHS break clause, Feb 2027)
- NDR 157% gets mathematically harder as the base grows
- $265M/quarter in stock comp — cash flow is brilliant, dilution is real
Research notes
1. Current Position
Current position: Palantir is the one company whose blitz is still underway — 12 consecutive quarters of growth acceleration, Q2 2026 revenue +92.8%, AIP as the second growth curve, sovereign AI as the third. But at exactly 65 — the threshold line — S-grade speed is held back by immature high ground (B 40/60) and D −6 (Class F founder control, European political risk). The verdict: in progress, rising.
2. Blitzscaling Lens
Blitzscaling lens: The fossil of Rule 6 — forward-deployed engineers and bootcamp selling as a business-model constant, not a tactic — and Rule 2 at its extreme (~$1.7M revenue per employee). The tension: Europe's political fires test Rule 5's judgment difficulty, and Rule 8 is inverted — the bottleneck is expectation excess (forward P/S 37×), not capital. The bootcamp's 5–9 anchor-band ceiling is the structural limit of the high ground.
3. Competitive Landscape
Competitive landscape: Explicit competitors (legacy SI, government legacy IT) are being replaced yet remain standing — pie-expansion, not disruption. The real threat is the quiet kin: the AI labs (OpenAI, Anthropic) solving the same enterprise-AI problem in a different language, plus hyperscaler AI stacks.
4. Inflection Points
Inflection points: (1) Q3 earnings (11/2 vs 11/9 — date unconfirmed) — whether the 13th consecutive quarter of acceleration holds against a +83% guidance, and whether FY2026 guidance is raised; (2) commercial penetration (U.S. commercial +149%, TCV +153%) cushioning the 42% government-revenue dependence; (3) delivering the "perfect execution" 37× forward P/S demands, and the progress of European risk toward the NHS break clause of February 2027.
5. One-Line Risk
One-line risk: The overlap of adjustment pressure on any expectations miss at forward P/S 37× with structural downside (42% government revenue + European political risk) is the largest downside variable.
Latest quarter — Q3 2026
Palantir's third quarter of 2026 was the first above $2 billion in revenue, reaching $2.313 billion, up 96% year over year (company Q3 2026 release). United States commercial revenue of $984 million grew 148% and passed government revenue of $953 million for the first time, while net dollar retention rose to 165%. The tension underneath is bookings: total contract value grew only 6%, and management blames shorter Sovereign AI contract terms for part of the gap.
Reference point: Q3 2026 as of now = Q2 2026 confirmed results + developments through T=2026-10-11. Q3 2026 results not yet released → awaiting Q3 results (11/2 expected (MarketBeat) vs 11/9 marked confirmed (TipRanks) — date conflict; re-verification needed in earnings week). - BlitzLab v1.0 score: 65/B (A 21 + B 40 + C 10 − D 6). Exactly the success threshold. Direction: rising (accelerating — quarterly estimates 63→65). - Confidence: High (listed company).
Current Position — In Progress
Palantir is the one company of the four whose blitz is still underway. Twelve consecutive quarters of growth acceleration, Q2 2026 revenue of $1.935B (+92.8% YoY), FY2026 guidance of $8.15B (+82%) — Section A at 21/25 is top-tier speed among measured companies. Rule of 40 at 155% (press-reported) is itself a historic figure; AIP is operating as the second growth curve (U.S. commercial +149%, customer count +35% YoY, TCV +153%), and sovereign AI (Nebius and Armada partnerships, press-reported) is opening as the third front. NDR of 157% — evidence of ontology lock-in, with existing customers spending 57% more each year — is the core basis of B1.
Yet the score is exactly 65 — on the threshold line. Speed is S-grade, but the high ground (B 40/60) cannot keep up, and D −6 (governance −3: the founder-control structure entrenched via Class F multi-class shares / regulatory and social costs −3: European political risk) holds it back. The pilot's one-line summary was accurate: "The business is S-grade; the price is debatable. The model placed Palantir exactly on the success/failure borderline (65 points)."
So the verdict is "in progress." It is in the middle of the blitz, and the direction is rising. A1's re-acceleration is pushing the score up, and the watch point is whether it breaks through the 65-point ceiling and settles in the 70s. And that verdict's inflection point is the Q3 earnings right ahead — the premise of this research batch being "a company whose quarter could decide its grade." With government budget cycles and European political risk also in play, it is the most dynamic observation target.
Blitzscaling Lens
The fossil of Rule 6 — "Do things that don't scale." Forward-deployed engineers and bootcamp selling are the large-scale operation of a high-cost, manual, inefficient method. Yet the result is U.S. commercial +149% and TCV +153%. To the point that the anchor table's B2 example is literally "the Palantir bootcamp (expensive but repeatable)," this company made Rule 6 a constant of its business model rather than a temporary tactic. The same grammar as the Airbnb founders visiting hosts' homes to take photos repeats, in enterprise AI's field, in the form of bootcamps.
Rule 2 — "Hire the people you need right now," at its extreme. Roughly 4,500 employees (press-reported) generate $7.7B in annualized revenue — about $1.7M per head (press-reported). The result of going for speed with a lean elite exactly fit for the current stage, not a perfect organization for future stages. Overwhelming productivity versus traditional SI grounds C3's 4 points ("the forward-deployed model is replacing the consulting cost structure"), and combined with a financial structure of D/E 2.14% and cash of $9.41B (confirmed), it is a blitz physique with zero capital constraint.
The breaking point and the tension — Rule 5's ("Let fires burn") judgment difficulty. Are Europe's political fires — the NHS £330M contract's February 2027 break clause, France's exit (ChapsVision replacement), Germany's replacement review, the Met Police £50M block, and the global protests of September–October 2026 (press-reported) — small fires that can be left burning, or big fires that can harm the company? The pilot recorded D4 −3 as "structural, but no revenue hit yet." For a company with 42% of revenue from government, political risk is an area where Rule 7 ("Ignore your customers") cannot be applied — ignoring government customers means losing contracts. If blitzscaling's rules presume commercial customers, Palantir fights in the rules' exception zone.
The Rule 8 paradox. Cash of $9.41B and effectively zero debt mean capital overflows, but the bottleneck is not capital — it is expectations. A market cap of ~$475B is about 58× the 2026 revenue guidance, and forward P/S of 37× (press-reported — estimated on a forward-12-month consensus basis; the calculation basis needs to be stated) is "a price demanding perfect execution." Where blitzscaling demanded capital excess (raise too much money), mature Palantir is fighting expectation excess. The quarterly stock-comp of $265M dilution debate is the same thread — cash flow is glittering, but dilution is real.
What B2's 9-point ceiling tells. The bootcamp is powerful but pinned to the top of the anchor 5–9 band ("expensive but repeatable," estimate). Because unlike SHOP-grade self-serve (12 points), it is not a structure where the product distributes itself. This is Palantir's structural high-ground limit — B 40/60 — and why the total stays at 65 despite S-grade speed. Unless the bootcamp is automated or productized, the high ground will not catch up with speed. In that AIP is the productization attempt, AIP's commercial penetration metrics should be read not merely as revenue growth rates but as leading indicators of high-ground expansion (B1, B2).
Competitive Landscape
The explicit competitors are the targets Palantir's replacement of is "in progress": legacy SI like IBM and Booz Allen, legacy IT procurement in defense and government, corporate legacy data stacks — as C1's 3 points say ("limited in scope, defense/government-centered"), replacement's scope is still limited. In the Ledger's 2×2 matrix, PLTR sits in the "thrived × thriving" cell, and the causality is pie-expansion. Legacy did not die; the pie grew.
The structural competitors take a fratricide form. The pilot recorded that the first-half 2026 share-price drop of −34% was caused by "competition fear with the AI labs." AI-native companies like OpenAI and Anthropic are solving the same problem (applying unstructured data to business work) in a different language on the enterprise AI stack, and the Ledger's insight — "disruptor-vs-disruptor configurations are often the real threat; fratricide is more fatal than external disruption" — appears for Palantir in the form of the AI labs. Hyperscaler AI stacks are structural competitors on the same layer.
Verdict: the loud enemies (legacy SI) are being replaced yet remain standing, and the real threat is the quiet kin (AI labs). If Palantir wobbles next, it is more likely to be the AI natives' front expansion than Booz Allen's counterattack.
Inflection Points
① The 13th quarter of growth acceleration — Q3 earnings (11/2 case vs 11/9 case; date needs re-verification) are the maximum judgment day. What to watch: whether quarterly revenue YoY maintains the acceleration trajectory after Q2's +92.8% — the company's Q3 guidance is $2.160–2.164B (confirmed), roughly +83% versus last year's Q3 of $1.18B, so "13 consecutive quarters of acceleration" would require a substantial upside surprise above guidance's upper end — and whether FY2026 guidance of $8.150–8.158B (+82%) is raised. Whether NDR of 157% is maintained must also be watched — it is a metric that becomes mathematically harder as the base grows, which the pilot flagged as a sustainability concern. This is why the quarter is "the quarter that could decide the grade" — continued acceleration would ground the case for breaking the 65-point ceiling (attempting to settle in the 70s), while a break would ground the case for remaining on the borderline.
② Sustained commercial penetration. What to watch: U.S. commercial growth (whether the +149% trend holds), customer count +35% YoY, TCV +153% — whether AIP bootcamp metrics are lowering the 42% government-revenue dependence. Whether "deepening ontology within customers," the basis of B1 (8 points), is also reproducing in the commercial segment is the crux of high-ground expansion. The reading point of this quarter is whether the commercial segment is building the structure to cushion the government budget cycle variable (flagged in the direction assessment).
③ Expectations vs. execution, and the progress of European risk. What to watch: whether "perfect execution" demanded by forward P/S of 37× (press-reported) is delivered — the question is not beating market expectations but not missing them. Simultaneously, the progress of European risk must be checked — developments toward the NHS break clause (February 2027) and whether additional exit signals emerge from France and Germany. The moment D4 −3 changes from "no revenue hit" to "hit occurring," the score's downside opens.
One-Line Risk
Forward P/S of 37× (press-reported) — "a price demanding perfect execution" — the point where adjustment pressure on any expectations miss overlaps with structural downside (42% government revenue plus European political risk, the NHS break clause of February 2027) is the largest downside variable.
Palantir reported third-quarter 2026 revenue of $2.313 billion, up 96% year over year and 20% sequentially, the first quarter above $2 billion (company Q3 2026 release). United States commercial revenue reached $984 million, up 148% year over year and 29% sequentially, while United States government revenue was $953 million, up 96% year over year. Chief executive Alex Karp said commercial revenue surpassed government revenue for the first time in the company's history, a $31 million gap that marks a shift in where growth now comes from. Total commercial revenue of $1.168 billion and total government revenue of $1.146 billion each crossed $1 billion for the first time, and international government revenue grew 31% to $192 million (company Q3 2026 earnings call).
Guidance moved up with the quarter. Palantir raised full-year 2026 revenue guidance to $8.530-$8.534 billion, about 91% growth, from $8.150-$8.158 billion (company Q3 2026 release). Fourth-quarter guidance calls for revenue of $2.649-$2.653 billion and adjusted operating income of $1.640-$1.644 billion, and United States commercial revenue is guided above $3.559 billion, growth of at least 143%. The company also guided full-year adjusted free cash flow to $4.8-$5.0 billion. The raised outlook rests on the same commercial momentum that drove the quarter: United States commercial customers reached 686, up 29% year over year and 5% sequentially, and the company closed 212 deals of $1 million or more, 107 of $5 million or more, and 64 of $10 million or more in the quarter (company Q3 2026 release and earnings call).
The counterweight to the quarter is bookings. Total contract value was $2.918 billion, up only 6% year over year, against 49% growth in the second quarter, and United States commercial contract value rose 11% after growing 153% the quarter before (company Q3 2026 release). Total contract value also fell about 13% sequentially from $3.373 billion. Remaining performance obligation was $4.9 billion, up 88% year over year but flat sequentially, the first flat quarter since the first quarter of 2023, and long-term remaining performance obligation slipped to $2.74 billion from $2.81 billion (company Q3 investor presentation). Management attributed part of the softness to shorter Sovereign AI contract durations, noting that contracts under twelve months are excluded from reported remaining performance obligation. Whether contract value and remaining performance obligation re-accelerate in the fourth quarter is the directly checkable next observation.
Profitability and cash sit on the other side of the bookings question. GAAP operating income reached $1.085 billion, a 47% margin and the first quarter above $1 billion, while adjusted operating income was $1.427 billion, a 62% margin, up from 51% a year earlier (company Q3 2026 release). GAAP net income was $1.128 billion, a 49% margin, up 137% from $475.6 million a year earlier, and adjusted earnings per share were $0.44, the same as GAAP earnings per share. Operating cash flow was $1.205 billion, a 52% margin, and adjusted free cash flow was $1.216 billion, a 53% margin, for a Rule of 40 figure of 158%. The quarter ended with $10.4 billion in cash, cash equivalents, and United States Treasuries. The combination of high margins and a large cash balance is the buffer the company carries into a quarter where bookings, not revenue, are the open question.
The demand quality underneath the quarter is visible in retention. Net dollar retention reached 165%, up from 157% in the second quarter, and United States commercial customers grew 29% year over year to 686 (company Q3 2026 earnings call). Growth came more from existing customers expanding than from new logos: United States commercial revenue per customer rose about 88% year over year, while the customer count grew only 5% sequentially. The company also signed a manufacturing partnership with Changshin in November, applying Foundry and AIP to footwear development and factory operations, though no contract value or term was disclosed (company press release, November 4, 2026). The next check is the fourth-quarter report: whether contract value growth and remaining performance obligation turn back up, and whether the commercial business keeps outpacing government.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Q4 2026 · Expected
Coverage
As of October 2026 · Model v1.0 (frozen) · Confidence: High (listed) · Not investment advice — a scholar's assessment.
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.