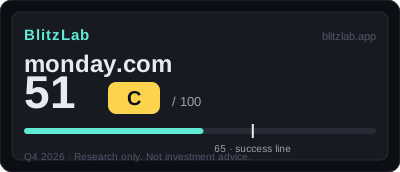
monday.com — Blitz Index 51 (C)
A clean product-led climb into the enterprise — $100K+ customers +37% — on a deceleration glide that has never missed a year: 68% → 27% → guided ~20%.
Last re-scored: October 21, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 14 / 25 | Growth glides down every year (68% → 41% → 33% → 27%); Q2 2026 +22% with FY2026 guided +19–20% |
| B · Moat | 35 / 60 | Work OS land-and-expand: $100K+ ARR customers 2,019 (+37%) and multi-product ARR above 10% — expansion moat, not network effect |
| C · Creative destruction | 8 / 15 | Turned the spreadsheet's job into a platform category; AI products doubled ARR in a quarter, from a small base |
| D · BlitzFailing | −6 | Israel-HQ geopolitical exposure (55% of staff) and FPI reporting exemptions — structural, disclosed, −6 |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 58.3 · Speed 56 · Creative 53.3.
Watch item
Gates: G1 ✓ · G2 ✓ (estimate — the 20-F discloses no quantified TAM). Bar ≈ $14.7B (FY2026E guidance × 10) vs a ~$3.95B market cap — price headroom is not the constraint; the glide path is.
Strengths
- Enterprise proof: $100K+ ARR customers +37% YoY to 2,019; their share of ARR rose 24% → 30%
- GAAP breakeven reached — 1H 2026 operating income +$18.2M
- AI product ARR doubled quarter over quarter in Q2 2026 and drove 17% of net new ARR
- SBC/revenue improved 14.4% → 9.8% — dilution discipline is tightening
Concerns
- The deceleration has never missed a year: 68% → ~20% guided in four years
- NRR slipped 111% → 109% as the base moves upmarket
- FY2025 net income includes a one-off $61.2M non-cash tax benefit — earnings quality needs the adjustment
- 55% of employees are in Israel; the 20-F spells out regional-conflict and FPI-governance risk
Research notes
Thesis: a high-quality business in the middle of a lever change
monday.com Ltd. (NASDAQ: MNDY) scores 51 out of 100, grade C, on BlitzLab v1.0: speed 14 out of 25, moat 35 out of 60, creative destruction 8 out of 15, less deductions of 6 points. The arithmetic is exact: 14 plus 35 plus 8 minus 6 equals 51, fourteen points below the 65-point line. On the radar conversion used in the score file, that is 56.0 for speed, 58.3 for moat, and 53.3 for creative destruction. There is no FLAG marker, because deductions of 6 sit well below the 15-point FLAG threshold. This is a first scoring, not a rescore, with no blind process. The as-of date, T, is October 20, 2026, the scoring date is October 21, 2026, and the latest results available at T are the second quarter of 2026, published on August 10, 2026. Third-quarter 2026 results, due on November 9, 2026, were confirmed before T as a date but fall after T, so they are excluded from the score and appear in this body only as a future marker, with no anticipated outcome attached.
The score file classifies monday.com as a mature company, because fiscal 2025 revenue of $1,232.0 million meets the $1 billion threshold at which the mature-company gate applies: continued growth or a second growth curve must be shown. Both gates pass, but they pass in different ways, and the difference matters for everything that follows. Gate 1, growth continuation or a second growth curve, passes on confirmed evidence. Gate 2, a ten-year ceiling for the new market at least ten times current revenue, passes only as an estimate. That split — a confirmed operating record on one side, an estimated market ceiling on the other — is a fair summary of the whole scorecard: much of what monday.com has already done is documented in filings, while much of what it still needs to become depends on a multi-category expansion whose size the company itself has not quantified.
The central tension in the score is stated plainly in the score file and should not be smoothed away here. On one side, growth is decelerating on a trajectory that has now run for four consecutive years, and the core self-serve customer base has essentially stopped growing in number. On the other side, the enterprise migration is accelerating in the numbers that matter most for a second growth curve: customers paying more than $100,000 in annual recurring revenue, customers paying more than $500,000, remaining performance obligations, and net revenue retention that remains higher for larger customers than for the base as a whole. Neither side cancels the other. The deceleration is real, the migration is real, and the score of 51 is best read as the present balance between them. The score file's own framing is that monday.com is a transitional blitzer: the first act, small and medium business product-led growth, is over, and the second act, enterprise direct sales plus multi-product expansion plus artificial intelligence pricing, has started but has not yet become the main growth engine. Whether the second act can outrun the deceleration of the first is the question on which the next fourteen points depend.
Speed: deceleration is the confirmed trajectory, migration is the counterweight
Speed scores 14 out of 25, from growth 5 out of 10, capital velocity 3 out of 5, hiring and productivity 3 out of 5, and share velocity 3 out of 5. The growth item carries the most important single fact in the score file, and it deserves to be stated in full. Revenue was $519.0 million in fiscal 2022, up 68.4 percent; $729.7 million in fiscal 2023, up 40.6 percent; $972.0 million in fiscal 2024, up 33.2 percent; and $1,232.0 million in fiscal 2025, up 26.7 percent. The first quarter of 2026 grew 24 percent to $351.3 million, the second quarter grew 22 percent to $364.6 million, including a favourable foreign-exchange effect of about 110 basis points, and guidance points further down: fiscal 2026 guidance of 19 to 20 percent growth, with third-quarter guidance of 16 to 17 percent. That is four years of monotonic deceleration, confirmed in the filings, and the score file is explicit that at a scale above $1.2 billion, growth in the twenties is solid but is not blitz speed. The growth score of 5 reflects both halves of that sentence: the absolute rate is still substantial, and the direction has not turned.
Two retention figures sharpen the deceleration story without changing its direction. Overall net revenue retention fell from 111 percent to 109 percent, and the cohort of customers above $100,000 in annual recurring revenue fell from 117 percent to 115 percent. The score file also records a decline for customers with ten or more seats, from 115 percent to 113 percent, as part of a broad-based softening across cohorts. Those declines are scored here, in speed, and the score file states explicitly that they are not double-counted later as a regulatory or social deduction. Against them stand two offsets that the growth item also records. Remaining performance obligations reached $937 million, up 34 percent year over year, which is a forward-looking stock of contracted revenue, and the number of customers above $100,000 in annual recurring revenue reached 2,019, up 37 percent year over year. The score file notes that a return to guidance re-acceleration or a rebound in net revenue retention would be grounds to revisit the growth score upward. Until such evidence appears, the score stays in the middle, and that conditionality is part of the score rather than an afterthought to it.
Capital velocity, at 3 out of 5, describes a company that generates its own capital rather than raising it. Operating cash flow was $333.6 million in fiscal 2025 and adjusted free cash flow was $322.7 million, a margin of 26 percent, achieved without borrowings. The speed of capital deployment itself was fast: a $870 million share repurchase programme was fully exhausted in three quarters, with $135.0 million in the fourth quarter of 2025, $553 million in the first quarter of 2026, and $182 million in the second quarter of 2026. The reason the score stops at 3 is what that deployment was for, and what the forward guidance implies. The repurchases offset dilution and returned cash to shareholders rather than funding growth investment, and fiscal 2026 adjusted free cash flow guidance of $280 to $290 million, at a margin of 19 to 20 percent, retreats from fiscal 2025 on both absolute amount and margin. Beyond that, the score file finds little demonstrated growth capital allocation besides the OneAI acquisition, whose price was not disclosed. A company that can fund itself from cash flow, spend $870 million in three quarters, and still guide to less free cash flow than the year before is demonstrating capital discipline and capital speed at the same time, but it is not demonstrating the aggressive reinvestment that the top of this item rewards.
Hiring and productivity score 3 out of 5, and the figures show a workforce growing at the same pace as revenue rather than ahead of or behind it. Headcount was 3,155 at December 31, 2025, up 26 percent year over year, against revenue growth of 26.7 percent, including 875 builders in research and development, product, and design. Revenue per employee in fiscal 2025 was about $390,000 on the score file's calculation, which it places in the middle range for software as a service, at a distance from top-tier productivity. Management declared in the first quarter of 2026 that artificial intelligence productivity would decouple headcount growth from revenue growth, but the score file records that declaration as not yet demonstrated. The second quarter of 2026 then supplied a counterpoint in the form of a $21.4 million restructuring charge, described in the score file as a non-cash impairment of Israel office space that had been secured on the assumption of headcount expansion — in other words, past hiring and space expansion, priced as over-expansion. Sales and marketing expense at 51.2 percent of fiscal 2025 revenue is a further productivity discount in this item. The score of 3 therefore describes a company whose hiring has kept pace with growth, whose productivity is respectable rather than exceptional, and whose claim to an artificial intelligence productivity break remains a statement to be tested rather than a result to be credited.
Share velocity, at 3 out of 5, is where the two stories of this company meet most directly. The upmarket share gain is fast. Customers above $100,000 in annual recurring revenue rose from 1,207 at the end of 2024 to 2,019 in the second quarter of 2026, with what the score file calls the largest net additions on record, and customers above $500,000 rose from 50 to 114, up 68 percent year over year. The share of annual recurring revenue from customers above $50,000 rose from 34 percent to 43 percent, and the share from customers above $100,000 rose to 30 percent. On the starting point for that last figure, the score file gives two numbers that this body reports without reconciling: the share-velocity item states 22 percent rising to 30 percent, while the key-drivers summary states 24 percent rising to 30 percent. The end point is the same; the starting point differs between the two passages, and a reader adding up the score file should be aware of the gap rather than have it quietly resolved here. The opposite side of the share story is stagnation in the core. Total paying customers rose from 245,000 at the end of 2024 to just over 250,000 at the end of 2025, growth of about 2 percent, and customers with ten or more seats grew only 6 percent year over year. The business that made monday.com, the small and medium business base, is barely adding customer numbers at all, while the enterprise tier is adding them rapidly. The score file also notes that the annual report names dispersed competitors, including Asana, Atlassian, and HubSpot, but discloses no quantified market share, so there is no filed figure for overall share velocity to rest on. The score of 3 is the midpoint of that split: fast upmarket penetration, stalled core penetration, and no quantified market share to arbitrate between them.
Moat: an excellent margin without a classic network effect
Moat scores 35 out of 60, from network effects 7 out of 18, distribution scalability 9 out of 18, market size 8 out of 12, and gross margin 11 out of 12. The shape of that split is the analytical core of the scorecard, and the score file states its conclusion in advance: financial quality is first-class, but the items that carry the most points in this model, network effects and distribution together worth 36 points, contribute only 16. That gap, more than any other single fact, explains why a company with an 89 percent gross margin and positive free cash flow scores 51 rather than 65.
Network effects score 7 out of 18, and the score file is candid that a classical direct network effect is absent on the disclosed evidence. There is no structure in the filings by which one user's adoption straightforwardly raises the value of the product for other users, so the top anchor band of 15 to 18, reserved for platform-type lock-in, does not apply. The score sits inside the 5 to 9 band for data and ecosystem effects instead. What supports that placement is switching cost built on accumulated workflows and data, plus multi-product standardisation, with a quantitative trace: larger customers retain at higher rates than the base as a whole, with overall net revenue retention of 109 percent against 115 percent for customers above $100,000, which the score file treats as quantitative evidence of land-and-expand. The ecosystem itself exists but is modest in disclosed scale: 869 marketplace applications and 300 channel partners across about 50 countries. The score file withholds the top of the band because the new product groups together exceed 10 percent of total annual recurring revenue, as of the third quarter of 2025, but product-level annual recurring revenue is not separately disclosed, so the ecosystem effect cannot be sized product by product. A reader should therefore understand the score of 7 as credit for a real but bounded effect: customers who build workflows and standardise on more than one product become harder to displace, but that is a switching-cost moat, not a network moat, and the filings do not support calling it more than that.
Distribution scalability scores 9 out of 18, and here the score file applies a deliberate conservatism that is worth understanding. The structure is product-led growth: a 14-day free trial leading into a free tier for teams of two or fewer and four paid self-serve tiers, run alongside direct sales under a chief revenue officer organisation and 300 partners. In the first quarter of 2026 the company added seats-plus-credits pricing, a hybrid of seat and consumption billing. That structure could, in principle, support a high distribution score. It does not, for two filed reasons. First, the top bands do not apply: this is not distribution in which the product itself is the channel with customer acquisition cost converging to zero, nor is it strong virality. Second, the actual distribution is sustained by paid selling: sales and marketing expense was $630.9 million in fiscal 2025, or 51.2 percent of revenue, and total paying customer growth of about 2 percent shows the limit of the self-serve funnel in numbers. The score file states its rule explicitly: where a company falls between two anchor bands, the lower band applies, and the score of 9 is the top of the 5 to 9 band for distribution that depends on paid selling but can be repeatedly expanded. Repeatability is credited on the strength of a base above 250,000 customers and demonstrated conversion into enterprise direct sales. But a funnel that adds customers at 2 percent while consuming more than half of revenue in sales and marketing is not a self-propelling distribution engine, and the score refuses to pretend otherwise.
Market size scores 8 out of 12, and this item must be read together with the Gate 2 verdict, because both rest on the same estimated foundation. The gate bar is about $14.7 billion, calculated as ten times estimated fiscal 2026 revenue of about $1,470 million at the guidance midpoint. The annual report, filed on March 13, 2026, contains no quantified total addressable market disclosure: its discussion of opportunity is qualitative, framed around the democratisation of software and artificial intelligence, and the score file states plainly that the market ceiling cannot be verified from company disclosure. The pass therefore rests on an external combined estimate covering work management plus customer relationship management plus service desk plus developer tools, and the score file treats the combined ceiling as estimated to exceed the bar by a large margin. No total addressable market figure is presented in this body, because the score file supports none: to invent one would be to upgrade an estimate into a fact. The market-size score of 8 applies two discounts to that estimated pass. First, under the score file's principle, an item resting on estimation starts one anchor band lower. Second, each category in the combined market already has an established leader, including Atlassian and HubSpot, and multi-product revenue, while above 10 percent of total annual recurring revenue, stops at aggregate disclosure without product-level breakdown, so penetration remains at an early, unproven stage. The market is plausibly large enough; the company's demonstrated penetration of it, beyond its original work management category, is not yet large enough to score higher.
Gross margin, at 11 out of 12, is the strongest moat item and the clearest evidence of business quality in the scorecard. Gross margin was 88.9 percent in fiscal 2023, 89.3 percent in fiscal 2024, and 89.2 percent in fiscal 2025, on gross profit of $1,098.9 million: three consecutive years around 89 percent, structurally stable at the top end for software as a service. Non-GAAP operating margin was 14 percent in fiscal 2025, with fiscal 2026 guidance of about 16 percent, which the score file reads as the beginning of operating leverage converting that gross margin into operating profit. The perfect score is withheld for two reasons that keep the item honest. Gross margin itself is flat rather than expanding, so the strength is stability rather than improvement, and the costs below gross profit remain heavy: sales and marketing at 51.2 percent of revenue leaves generally accepted accounting principles operating profit at essentially breakeven in fiscal 2025, a loss of $1.7 million. The quality of the margin is first-class, in the score file's phrase; the conversion of that margin into operating profit is only just beginning. That distinction, between a margin that is excellent and a conversion that is early, is exactly what the score of 11 is designed to capture.
Creative destruction: replacing packaged software, one category at a time
Creative destruction scores 8 out of 15, from replacing the existing order 3 out of 5, irreversible behaviour change 3 out of 5, and cost-structure change 2 out of 5. The company narrative, as recorded in the annual report, is clear and ambitious: departmental teams previously bought separate pre-packaged software for customer relationship management, project management, and service desks, and a no-code platform replaces those separate purchases with a single way of working. Beyond that, the narrative extends to a change in the order itself, from helping people manage work to helping do the work for them — the score file quotes that management phrasing, and this body preserves it as a management claim rather than as an established result. The score of 3 reflects the gap between the narrative and the demonstrated displacement. Replacement evidence is centred on the original work management business, while in customer relationship management, service, and developer tools the company is at a stage of coexistence and competition with the existing order rather than replacement of it. One element does add authenticity to the self-disruption claim: the company is converting its own billing model from seat-based pricing toward consumption-based pricing under seats-plus-credits, which means it is willing to disturb the very pricing mechanism that built its revenue. But the scale of that conversion is not yet demonstrated, so the score stops at the midpoint: displacement in progress, with a limited range so far.
Irreversible behaviour change also scores 3 out of 5, and the evidence here is stronger in the enterprise tier than in the business as a whole. Customers above $500,000 in annual recurring revenue rose from 50 at the end of 2024 to 114 in the second quarter of 2026, a 2.3-fold increase in eighteen months, which the score file treats as diffusion of a specific behaviour: large enterprises standardising mission-critical workflows on a single platform. Remaining performance obligations up 34 percent year over year support that reading at the contract level, because long commitments are a form of stickiness that outlasts a single quarter's usage. Artificial intelligence behaviour change is counted only as a beginning, and the score file is explicit that it must not be overstated. Artificial intelligence product annual recurring revenue doubled quarter over quarter in the second quarter of 2026 and accounted for 17 percent of net new annual recurring revenue, but the absolute amount was not disclosed, and the fastest $1 million in annual recurring revenue for the monday vibe product, reached 2.5 months after charging began, is early scale by any measure. Switching away from software as a service remains possible in principle, and net revenue retention is falling, so the top score for irreversibility does not apply. The score of 3 therefore describes a behaviour change that is genuinely spreading among large customers, with an artificial intelligence chapter that has opened but has not yet been measured in absolute terms.
Cost-structure change scores 2 out of 5, the weakest creative destruction item, and the reason is the absence of measurement rather than the absence of an argument. The customer-side argument exists in direction: a no-code platform replacing multiple departmental packages and custom development, and artificial intelligence agents lowering the cost of performing work, would change what customers spend to get work done. But the score file records that no unit cost measurement of that change has been disclosed, so the argument cannot be scored as a demonstrated result. The company's own cost structure, meanwhile, remains that of a traditional software-as-a-service business: sales and marketing at 51.2 percent and research and development at 26.0 percent of fiscal 2025 revenue, with generally accepted accounting principles operating profit only just entering positive territory at $18.2 million in the first half of 2026. Whether the seats-plus-credits conversion will demonstrate a cost-structure change is, in the score file's words, a question for the coming quarters. The score of 2 is therefore a holding judgement: direction without disclosed measurement, and a company cost structure that has not yet itself been transformed.
Deductions and risks: light in total, specific in composition
Deductions total only 6 points, which is why there is no FLAG marker, but the composition of those 6 points is specific and worth reading item by item, because each points to a different kind of risk. Debt deducts 2 points, revenue quality 1, governance 1, and regulatory and social costs 2. None of these is a crisis figure. Together they describe a company whose financial risks are modest, whose governance carries one unusual founder provision, and whose geographic and reporting profile carries a structural discount that will not disappear with a good quarter.
Debt, at negative 2 out of a possible negative 10, is notable mostly for what is absent. Borrowings and convertible notes are zero, and cash plus securities stood at $1,072.8 million at June 30, 2026, a net cash position. Operating lease liabilities of $168.8 million and purchase obligations of $73.2 million are small against the scale of operations. The deduction comes instead from dilution and earnings quality. Share-based compensation was $177.0 million in fiscal 2025, or 14.4 percent of revenue, which is a high level, even though it improved to 9.8 percent of revenue in the first half of 2026, and even though the $870 million repurchase programme reduced the share count by 17.4 percent, a reversal of dilution. The score file records the cost of that reversal plainly: more than half of the company's cash was spent to achieve it. Earnings quality adds a second element to the same item: of fiscal 2025 net income of $118.7 million, $61.2 million came from a one-time, non-cash tax benefit from a valuation allowance reversal, so more than half of reported net income in that year was not operating cash generation. The debt score of negative 2 is therefore not a judgement about leverage, which is minimal, but about the price paid to contain dilution and the portion of reported profit that does not recur.
Revenue quality deducts only 1 point, and the score file is clear that the revenue itself carries no quality issue: there is no restatement, no audit opinion problem, the base is subscription revenue, and remaining performance obligations of $937 million, up 34 percent, give revenue good visibility. The single point comes from litigation. On March 10, 2026, a shareholder class action was filed in the Southern District of New York under Securities Exchange Act sections 10(b) and 20(a), advancing claims related to forward-looking guidance. The action is at a preliminary stage, the company states that it is without merit and that it will defend itself vigorously, and no claim has been proven. The score file therefore limits the deduction to the minimum and notes that the item should be re-examined if the litigation develops. A reader should keep both halves together: the revenue base is clean on the disclosed evidence, and a guidance-related lawsuit exists at a preliminary stage, unproven, with its future course unknown.
Governance deducts 1 point, against a basic structure that the score file describes as clean. There is a single class of ordinary shares with one vote per share and no differential voting rights. Founder ownership is not concentrated in the usual sense: Roy Mann holds 9.6 percent, Eran Zinman holds 3.4 percent, and officers and directors together hold 13.9 percent. The deduction rests on a single unusual provision: one founder share held by Roy Mann carries a veto over three categories of transaction, namely a transaction in which a particular person would become a holder of 25 percent or more through a merger or share issuance, a sale of all assets, and a change to the foundation funding plan. The share carries no dividend or voting rights, and it extinguishes automatically on termination of employment, transfer, or dilution of the holding. The veto is therefore narrow in scope, but it is real where it applies: a founder individual holds a veto over change-of-control transactions. That is the whole of the governance deduction, and this body adds nothing beyond the score file's description of it. A single share with a narrow but real veto is a small deduction, but it is not a zero, because it places one person's consent between shareholders and certain fundamental transactions.
Regulatory and social costs deduct 2 points, and this is the deduction most tied to where and how the company is constituted. The headquarters are in Israel, and 55 percent of employees, 1,729 of 3,155, work in Israel. The annual report names regional conflict risk, including Israel-Iran tensions, as a disclosed risk, together with constraints under Israeli law on takeovers, capital gains tax exposure, and regulation under the General Data Protection Regulation and Israeli privacy law. As a foreign private issuer, the company is not subject to United States proxy rules and reports less frequently, so the investor protection apparatus available to holders is weaker than for a domestic issuer. The score file notes two things that are not deductions here: growth deceleration and net revenue retention decline are already reflected in speed and are not double-counted in this item, and the absence of a dividend is not a reason for a deduction. The score of negative 2 is therefore a structural charge for geographic concentration and for a reporting regime that gives investors less frequent and less proxy-governed oversight, not a judgement about any particular regulatory event.
What to watch: the race between the second act and the deceleration
The score file's three key drivers translate into a short list of tests, and the honest way to present them is as open questions with named evidence, not as predictions. The first test is whether the second growth curve can become the main growth driver rather than an offset. Financial quality is first-class, in the score file's assessment: an 89.2 percent gross margin, a 26 percent adjusted free cash flow margin in fiscal 2025, no borrowings, and net cash. But this scoring model rewards those strengths only through gross margin and light deductions, while the fourteen-point gap to the 65-point line sits mostly in network effects, distribution, and growth — that is, in the success or failure of the second act itself. The enterprise numbers will tell that story first: whether customers above $100,000 and above $500,000 continue to grow at rates that can compensate for a core customer count growing at about 2 percent, whether the share of annual recurring revenue from larger customers continues to rise from 30 percent for the $100,000 tier, and whether multi-product revenue moves beyond just above 10 percent of total annual recurring revenue into a disclosed, product-level expansion. The score file's own test for a mature re-blitz case is that the second act must move from demonstration to main engine, and the current score records that it has not yet done so.
The second test is the deceleration trajectory itself, and the score file names its confirmation conditions with unusual precision. A reversal would look like re-acceleration in quarterly guidance, an end to the decline in net revenue retention, and disclosure of artificial intelligence annual recurring revenue in absolute terms together with a rising share of new business. The absence of any one of those would not by itself settle the question, but the absence of all three across the next two to three quarters would confirm the score file's largest blitzscaling risk: that deceleration settles in the teens, monday.com remains an excellent software-as-a-service business with an 89 percent gross margin, and ceases to be a blitzscaling company, facing multi-category competition against platform companies such as Atlassian and Microsoft without a growth premium. That scenario is recorded here as the score file frames it, as a risk to be tested against guidance and retention figures, not as a forecast of what will happen. The third-quarter 2026 results due on November 9, 2026 are the next scheduled marker for that test, and this body attaches no anticipated outcome to them. They are simply the next filing in which guidance, retention, and any artificial intelligence disclosure can be checked against the conditions above.
The third test is the conversion of margin into cash and the durability of capital discipline. Fiscal 2026 adjusted free cash flow guidance of $280 to $290 million, below the $322.7 million of fiscal 2025 despite higher revenue, means the coming year is one in which revenue rises and cash generation falls on guidance, and the score file also records an upward revision in non-GAAP operating margin guidance from around 12 percent at the start of the year to about 16 percent. Those two guidance movements pull in opposite directions, and future filings will show which one describes the operating reality. The seats-plus-credits conversion belongs on the same watch list: if consumption pricing demonstrably changes customer cost structures or retention, it will supply the measurement that the cost-structure item currently lacks; if it does not, the creative destruction score will remain where it is. The shareholder class action filed on March 10, 2026 should be watched on the same basis as the score file states it: preliminary and unproven now, re-examinable if its course changes. Finally, a valuation note that is explicitly not reflected in the score should be kept separate from it. The share price was $93.42 and market capitalisation about $3.95 billion on October 19, 2026, on a press-reported basis, implying a price-to-sales ratio of about 3.2 times fiscal 2025 revenue and about 2.7 times fiscal 2026 guidance revenue, with a 52-week range of $57.50 to $210.49 and a one-year decline of 58 percent, also press-reported. The business score does not look at price, and the one-year decline does not change any item in it, but a reader interpreting the $118.7 million net income figure should remember that $61.2 million of it was the one-time tax benefit described above. The score of 51, grade C, fourteen points below the line, is the summary that holds all of this together: a company with a proven first act, a high-quality margin, and light deductions, whose second act is real in its early numbers and not yet sufficient in its total effect. The filings of the next few quarters, and nothing else, will show whether that balance moves.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Q4 2026 · Expected
Coverage
monday.com Ltd. · Q3 2026 due Nov 9, 2026 (confirmed) · Score 51 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.