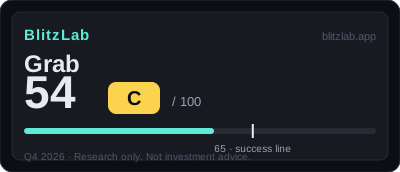
Grab — Blitz Index 54 (C)
Southeast Asia's super-app turned profitable — but a 2.6% non-performing loan ratio and 74.9% founder voting control take half the grade away.
Last re-scored: November 2, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 15 / 25 | On-demand GMV +21–22%; the lending book +197% is the steepest second curve in the scored set |
| B · Moat | 37 / 60 | Eight-country super-app density with take rates level with Sea — but incentives run at ~71% of revenue |
| C · Creative destruction | 11 / 15 | The cash-to-digital shift across Southeast Asia; three digital banks complete the platform |
| D · BlitzFailing | −9 | Loan quality disclosed at NPL 2.6% on a 4.3× lending book; founder voting power raised to ~74.9% after listing |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 61.7 · Speed 60 · Creative 73.3.
Watch item
Gates: G1 ✓ · G2 ✓ (IFRS 20-F). Bar ≈ $41.3B (FY2026E revenue × 10) vs a $135B Southeast-Asia digital-economy revenue pool (2025).
Strengths
- First full-year operating profit (+$65M FY2025) and 18 straight quarters of adjusted EBITDA growth
- FinServices slope: loans +197%, record quarterly disbursement of $1.2B, segment revenue +59% in Q2
- Mobility adjusted EBITDA margin of 56.6% — the profit engine is high quality
- FY2026 guidance raised again (revenue $4.15–4.20B); ~$6.8B of cash-like resources and buyback capacity
Concerns
- NPL 2.6% disclosed in Q3 2026 (allowance ratio 6.5%, ~2.4× coverage) — above Sea’s 1.0%, so credit quality is now visible but still a watch item
- Net income quality: FY2025 net finance income of $203M covers the entire $200M bottom line
- Founder voting power lifted to ~74.9% via a post-listing EGM (45 → 90 votes per share)
- $1,502M of convertible notes classified as current, and operating cash flow fell to $79M on loan growth
Research notes
Thesis
Grab scores 54 out of 100, grade C, under the BlitzLab v1.0 model as of 20 October 2026. The arithmetic is 15 for Speed, 37 for Moat, 11 for Creative Destruction, minus 9 in deductions. That total sits 11 points below the 65-point threshold, and it carries no FLAG, because total deductions of 9 fall short of the 15-point FLAG line. The score is best read as two stories running at different speeds inside one company. The first story, on-demand transport and delivery across eight Southeast Asian countries, has reached the harvest stage: it is profitable at the operating level, it keeps growing at a low-twenties percentage rate, and its largest segment earns an elite margin. The second story, financial services, is accelerating at a pace few scored companies match, yet the evidence that would let an outside reader judge the quality of that acceleration was only partly disclosed until Q3 2026 (NPL 2.6%). The gap between the slope of the second story and the visibility into it is the central tension of this page.
Grab was founded in 2012 as MyTeksi by Anthony Tan and Tan Hooi Ling, and it reached the NASDAQ on 1 December 2021 through a SPAC merger that valued the company at about $40 billion at the time. The scoring date, 2 November 2026, uses the third quarter of 2026 as the latest confirmed quarter, covering 1 July to 30 September 2026 and announced on 2 November 2026. All figures here are on an IFRS basis, because the company's 20-F financial statements are prepared under IFRS Accounting Standards, and share-price and market-size figures are press-reported rather than filing-confirmed. The third quarter of 2026, reported on 2 November 2026, is now the latest confirmed quarter: revenue $1,112M (+27% YoY), adjusted EBITDA $237M, and a first NPL disclosure of 2.6%.
The gate verdicts frame everything that follows. Gate 1, sustained growth or a second growth curve, passes on confirmed evidence. Gate 2, a ten-year market ceiling at least ten times current revenue, passes on an estimate built from segment sums, with lower confidence than a single-segment verdict would carry. The bar for Gate 2 is about $41.3 billion, set from the midpoint of raised full-year 2026 revenue guidance of $4.10 to $4.15 billion, or roughly $4,125 million. On an estimated trailing-twelve-month revenue base of about $3,730 million, built from first-half 2026 revenue of $1,952 million plus an estimated second-half 2025 figure of about $1,780 million, the bar would be about $37 billion instead. The verdict is the same under either base, which matters because it shows the gate conclusion does not hinge on choosing the friendlier denominator.
Revenue itself tells the first part of the story plainly. IFRS revenue rose from $2,359 million in fiscal 2023 to $2,797 million in fiscal 2024, growth of 18.6 percent, and then to $3,370 million in fiscal 2025, growth of 20.5 percent. The first quarter of 2026 added $955 million, up 24 percent, and the second quarter added $997 million, up 22 percent. Raised guidance for fiscal 2026 implies growth of about 22 to 23 percent. That is durable, double-digit growth at a revenue base above $3 billion, and it is also the reason the growth item scores 7 out of 10 rather than higher: the pace sits in the low-twenties band, alongside companies scored at the same level for similar growth, while faster peers in the same scoring round earned higher marks for growth in the high-thirties and near-fifty percent range. Grab is growing like a maturing platform, not like a company still in its first blitz.
Profitability is where the first story turns a corner. Fiscal 2025 produced the company's first annual operating profit, positive $65 million against a loss of $168 million the year before. Adjusted EBITDA has now grown for eighteen consecutive quarters. Those two facts together are the strongest single piece of evidence in the file that the on-demand business has moved from a subsidised land grab into a business that funds itself. The qualification matters as much as the headline, and it will return later in this draft: fiscal 2025 net income of positive $200 million sits alongside net finance income of $203 million, which is fair-value in nature, so the operating profit of $65 million is the more honest measure of what the core business earned. The same pattern repeated in the second quarter of 2026, when net income of $235 million exceeded adjusted EBITDA of $168 million. The business has turned profitable, and the profit deserves to be read at the operating line first.
Speed
Speed scores 15 out of 25, built from growth at 7, capital velocity at 3, hiring and productivity at 2, and share momentum at 3. Each item carries a distinct explanation, and together they describe a company whose operating engine is still moving while its capital engine has changed character.
Capital velocity, at 3 out of 5, captures that change. There is demonstrated fundraising ability: a $1.5 billion zero-coupon convertible bond maturing in 2030, issued in June 2025 at a conversion price of about $6.55, a 40 percent premium, confirmed in SEC filings. But no new mega-raise followed in 2026, and the share price fell 41.1 percent year to date and 47.9 percent over one year on a press-reported basis, which narrows the equity window. The centre of capital activity has instead become return of capital: a cumulative $1.75 billion share repurchase programme, with about $900 million remaining and scheduled for execution within twelve months, confirmed on 15 September 2026. The company that listed at about $40 billion through a SPAC is now, in capital terms, returning cash rather than raising it at scale. That is not a criticism in itself; it is a description of phase. Blitzscaling fuel has become harvest cash, and the score reflects the shift rather than punishing it outright.
Hiring and productivity, at 2 out of 5, is the weakest speed item, and the score file is careful about why. Full-time headcount stood at 12,012 at 31 December 2025, confirmed in SEC filings, alongside 1,242 fixed-term staff and 3,956 dispatched workers. Revenue per employee calculates to about $281,000, but the file warns that this is a structural figure, mixing supermarket retail staff at Jaya Grocer and Everrise with operating staff, and that drivers are partners rather than employees. The model therefore sits below peers with far higher revenue per employee and above a peer whose much larger workforce produced a lower figure, but the gap to the most productive platforms is clear and there is no evidence of a hiring surge. The score of 2 records a platform that is not labour-heavy in the way its headcount suggests, without claiming productivity it has not demonstrated.
Share momentum, at 3 out of 5, rests on demand and supply growing together without a disclosed market-share number to anchor the claim. Monthly transacting users reached 53.9 million, up 17 percent, in the second quarter of 2026. Monthly active driver partners rose 19 percent year on year to a record, and delivery merchants grew 8 percent in the same quarter, all confirmed in SEC filings. What is missing is a quantitative share figure: the company's description of itself as Southeast Asia's largest super-app is a company claim, not a disclosed measurement, and the 20-F names competition from GoTo and Gojek and ShopeeFood, plus the risk of Didi re-entering. The score therefore credits two-sided growth while withholding credit for share expansion that has not been evidenced. That discipline, crediting what is shown and not what is asserted, runs through the whole scoring file.
Moat
Moat scores 37 out of 60, from network effects at 11, distribution scalability at 10, market size at 8, and gross-margin proxy at 8. Converted to the radar scale, moat sits at 61.7 and speed at 60.0 out of 100, while creative destruction reaches 73.3. The moat is real, regionally bounded, and expensive to maintain. All three qualifiers matter.
Network effects, at 11 out of 18, sit in the two-sided marketplace liquidity band of 10 to 14. The platform has three sides: consumers at 53.9 million monthly transacting users, drivers, and merchants, with city-level cross-liquidity between them. The super-app adds a second loop on top of that liquidity, as mobility users extend into delivery, payments, and lending, and advertising adds a third: self-serve advertisers grew 21 percent and average advertiser spending rose 24 percent year on year, both confirmed in SEC filings. The discounts are equally specific. The scale is regional rather than global, which separates Grab from a global platform with a far larger active user base and from a peer with much denser single-country coverage. All three sides multi-home, meaning users, drivers, and merchants can and do use rivals in parallel. And liquidity is maintained at a cost: incentives of $706 million in the second quarter of 2026 alone, detailed below, mean part of the network is effectively rented each quarter rather than owned outright.
Distribution scalability, at 10 out of 18, follows the same logic. The super-app single entry point, the paid GrabUnlimited subscription, and the three-cornered digital bank network extend distribution from rides and deliveries into finance. Vertical integration into supermarkets, through Jaya Grocer and Everrise, contributed an additional $161 million to fiscal 2025 revenue. The proposed acquisition of foodpanda's Taiwan business, still awaiting closing with completion expected in the second half of 2026, would extend geographic reach for the first time beyond the existing eight-country footprint. The discount is structural and quantified: distribution here is not primarily viral, it is substantially purchased. Second-quarter 2026 incentives were $317 million to partners plus $389 million to consumers, totalling $706 million against quarterly revenue of $997 million, or about 71 percent of revenue. A distribution system that costs more than seven-tenths of a quarter's revenue in incentives cannot score alongside peers whose distribution efficiency is demonstrated through marketing ratios rather than incentive totals, and the file does not pretend otherwise.
Market size, at 8 out of 12, reflects the Gate 2 estimate with its caveats carried forward. Southeast Asia's digital economy exceeded $300 billion in gross merchandise value in 2025, with a revenue pool of $135 billion in 2025 on a press-reported basis from the Google, Temasek, and Bain e-Conomy SEA 2025 report, and gross merchandise value projected at $600 billion to $1 trillion by 2030. That pool is about 3.3 times the Gate 2 bar, which supports a pass. But Grab's participating slice is narrower than the whole pool: it does not participate in e-commerce, the largest segment, where Shopee and TikTok Shop operate, and its geography is limited to eight countries plus the pending Taiwan addition, with country-level regulation, including licensing and buy-now-pay-later rules, pressing on the ceiling. The score of 8, below a peer scored at 9 with a larger bar and three segments, records a large market entered through a narrower door.
The margin item, at 8 out of 12, requires the most careful reading in the moat section, because the file states plainly that IFRS consolidated gross margin is not separately disclosed. The score is therefore a proxy built from segment adjusted EBITDA, and it is labelled as such. Mobility earns an adjusted EBITDA margin of 56.6 percent, calculated as $690 million on $1,219 million, which the file calls elite-grade and which functions as the company's profit engine. Deliveries earn 15.9 percent, or $287 million on $1,800 million. Financial services lose 31.7 percent, or negative $110 million on $347 million. Company-wide adjusted EBITDA margin improved from 15.9 percent in fiscal 2023 through 23.7 percent to 25.8 percent in fiscal 2025, although the quarterly disclosure basis differs and the second quarter of 2026 printed at 16.9 percent on that basis, so the two series should not be spliced without noting the definitional difference. The discount is the disclosure limit itself: because the true gross margin cannot be directly verified, and because the fintech loss drags the blended figure, the item stops at 8. A reader who wants a cleaner margin story will not find it in the filings as currently presented, and this draft does not manufacture one.
Creative destruction
Creative destruction scores 11 out of 15, from displacement of the old order at 4, irreversible behaviour change at 4, and cost-structure change at 3. This is the strongest of the three radar axes, and it is the section where Grab's claim to be a blitzscaler is most intuitive, because the thing being replaced is visible in daily life.
Displacement, at 4 out of 5, names a clear incumbent set: traditional taxis, cash payment, and branch banking that never reached the unbanked. The super-app, combining mobility, delivery, payments, lending, and insurance in a single application, together with the three-cornered digital bank network, replaces those incumbents piece by piece. The loan book's growth from $536 million to $2,318 million in two years, confirmed in SEC filings, is the quantitative trace of that replacement in finance. The point withheld is that much of the displacement is digitisation of an existing order rather than creation of a new one, and on the largest front, e-commerce, Grab is absent rather than a displacer. The score of 4 credits a genuine replacement story while refusing the top mark for a company that does not contest the biggest battlefield in its own region.
Behaviour change, at 4 out of 5, rests on habit. Monthly transacting users of 53.9 million, up 17 percent, use the super-app as part of daily urban life; GrabUnlimited subscription creates lock-in; digital payments and digital bank accounts habituate; and eighteen consecutive quarters of adjusted EBITDA growth provide indirect evidence of persistence. The withheld point is again about breadth and exclusivity: multi-homing alongside Gojek and ShopeeFood persists, and the changed behaviour is concentrated in the urban areas of eight countries rather than universal in the way smartphone or search adoption is. Irreversible is therefore a relative claim here, strong within its geography, bounded outside it.
Cost-structure change, at 3 out of 5, is a work in progress rather than a completed transformation. Branchless digital banks in Singapore, Malaysia, and Indonesia, data-based underwriting, and advertising auctions as monetisation are all changing how costs and revenues are structured. But the file records no company-disclosed measurement of per-unit cost collapse, and the $706 million quarterly incentive bill remains part of the structure. The score sits in the same band as peers described as changing in progress without completed measurement. That is an honest middle mark: the direction is visible, the proof of a collapsed cost curve is not yet published.
Deductions and risks
Deductions total negative 10, from debt at negative 2, revenue quality at negative 3, governance at negative 4, and regulatory and social cost at negative 1. Governance is the largest single deduction, revenue quality is the most consequential for the future, and the two together explain half of the gap to the nearest comparable peer, as the score file's key-driver analysis notes.
Debt, at negative 2 out of a possible negative 10, is a study in offsetting facts. Total borrowings were $2,053 million at 31 December 2025, split into $1,680 million current and $373 million non-current, confirmed in SEC filings. The notable structural detail is that $1,502 million of the $1.5 billion zero-coupon convertible bond is classified as a current liability despite a 2030 maturity, because of an embedded derivative. Total liabilities jumped to $5,226 million from $2,944 million in 2024, including $1,629 million of digital bank customer deposits. Against that stands cash of $3,433 million plus other investments of $3,371 million, about $6.8 billion in net-cash-like position. Share-based compensation of $241 million, or 7.2 percent of revenue, is on a declining path from $304 million through $279 million to $241 million. The discounts are an accumulated deficit of negative $17,470 million, a legacy of the SPAC era, and operating cash flow of only $79 million in fiscal 2025, down sharply from $852 million in fiscal 2024, dragged by a $691 million increase in loan receivables. The combination is exactly what the score file's comparison intends: net cash alongside loan-book expansion, scored on the same yardstick as a peer in the same position. The balance sheet is not fragile, but the cash-flow statement shows what fast lending costs in cash terms.
Revenue quality, at negative 3, is the deduction to watch most closely, because it prices an absence. The loan book grew 4.3 times in two years and 197 percent year on year to $2,318 million in the second quarter of 2026, with quarterly disbursements of $1.2 billion at a record level, yet the non-performing loan ratio is not disclosed. Two scored peers disclose the equivalent figure: one reports a 90-day-plus non-performing loan ratio of 1.0 percent, the other a 90-day-plus delinquency rate of 6.9 percent. Grab offers only a loan loss allowance of $98 million against gross loans of $1,278 million, or 7.7 percent, from which quality must be inferred backwards, and that allowance rate is strikingly higher than the disclosed 1.0 percent peer figure. Expected credit losses rose by $63 million in fiscal 2025. The allowance could reflect conservative provisioning, or it could reflect riskier lending; the disclosure alone cannot distinguish the two readings, and that indistinguishability is precisely what the deduction charges for. The second revenue-quality issue is the composition of profit already noted: fiscal 2025 net income of $200 million against net finance income of $203 million, and second-quarter 2026 net income above adjusted EBITDA, mean the bottom line leans on fair-value-flavoured income. The score applies the same yardstick used for a peer that discloses delinquency and still received negative 3, reasoning that Grab's disclosure is worse and its growth faster, so the same deduction is, if anything, generous.
Governance, at negative 4 out of a possible negative 5, is the largest deduction and the most unusual fact in the file. Anthony Tan holds 131,835,048 Class B shares, an economic interest of 3.2 percent, carrying 59.9 percent of voting power on the basis of 45 votes per Class B share at 31 January 2026. An extraordinary general meeting on 24 March 2026 then raised Class B votes from 45 to 90 per share, lifting pro-forma voting power to about 74.9 percent, confirmed in SEC filings, with Class B directors retaining the right to appoint a majority of the board. The score places this in the same band as peers with voting power in the seventies percent range. The stated rationale for the change, meeting Singaporean control requirements for the MAS digital bank, is recorded in a 6-K filing, but the file explicitly does not offset the deduction for the rationale, because the deduction scores structure rather than motive. Major shareholders Uber at 13.1 percent with 5.5 percent of votes, SoftBank at 9.8 percent, and Toyota at 5.4 percent are, on a voting basis, a minor check. A founder who strengthened control after listing, from an already dominant position to roughly three-quarters of votes on a small economic stake, is a governance fact that any reader of this page should carry forward, whatever view they take of the operating business.
Regulatory and social cost, at negative 1 out of a possible negative 5, is broad but financially small so far. The Philippines Competition Commission fined the company PHP 56.5 million, about $1.0 million, for breaching conditions of the Uber Southeast Asia acquisition, with a further PHP 12 million possible and a third-party monitor reviewing compliance, with incentive limits and additional fines possible. Singapore's competition authority blocked the Trans-cab acquisition, withdrawn in July 2024, and imposed interim measures on food delivery. Thailand's Trade Competition Commission has an investigation open. Malaysia's Consumer Credit Act 2025 brings buy-now-pay-later formally into regulation. Digital bank licence cancellation and driver worker-classification risks are live in the 20-F. Set against that breadth, the money amounts are modest at about the $1.2 million level, the Malaysian MyCC matter ended in a company win when the Federal Court declined the appeal, and no licence cancellation has materialised. The deduction is therefore small, matching a peer scored the same way for real but modest multi-jurisdiction regulatory cost. Breadth without yet materialising into large cost is the accurate summary.
The peer mirror sharpens the whole picture. The score file's first key driver notes that the 11-point gap to a comparable Southeast Asian super-app, scored at 63 against Grab's 54, is fully explainable: revenue of $22.9 billion against $3.37 billion, growth of 48 percent against 22 percent, disclosed non-performing loans of 1.0 percent against undisclosed, and founder voting power of 57.6 percent against 74.9 percent. Grab is, in the file's phrase, the smaller mirror of that peer, and the differences that matter most are not size alone but transparency and concentration of control, which together account for half the deduction gap. A reader who understands that sentence understands most of the score.
What to watch
The score file's blitzscaling assessment gives this company's phase a compact label: the on-demand first act is in harvest, and the financial second act is in acceleration. The first act's report card has been submitted in the form of an operating profit and eighteen quarters of adjusted EBITDA growth. The second act is only now reaching scale, with a loan book of $2.3 billion and a three-cornered digital bank network complete. The comparable peer's trajectory, from marketplace profitability into a financial second act, overlaps with a time lag, which makes the comparison instructive without making it a prediction.
Several markers from the score file deserve a place on any watch list, stated here without anticipated outcomes. First, whether the newly disclosed non-performing loan figure of 2.6% rises or falls in coming quarters, since the level — not just the disclosure — now prices the revenue-quality deduction. Second, whether quarterly disbursements and the loan balance keep growing while the allowance rate moves, in either direction, since the allowance is currently the only public window into credit quality. Third, whether the incentive bill of $706 million per quarter begins to fall while gross merchandise value and monthly transacting users keep growing, which would complete the claimed transition to efficiency in the on-demand business. Fourth, whether the foodpanda Taiwan acquisition closes in the second half of 2026 as expected, which would test geographic extension beyond the eight-country base. Fifth, whether financial services narrows its quarterly deficit further from the improvement already recorded, from negative $26 million to negative $15 million on a quarterly basis, toward the point where the second curve funds itself the way the first now does. Sixth, whether operating cash flow recovers from $79 million as the loan book's cash drag is absorbed, and whether the remaining roughly $900 million of the repurchase programme is executed within the stated twelve months. Seventh, how the multi-jurisdiction regulatory items develop, particularly the Philippines monitor process and the Malaysian buy-now-pay-later regime, and whether the Uber non-compete expiry and Didi re-entry risks named in the 20-F materialise in any form. Finally, the reporting calendar itself: the third-quarter 2026 results, reported on 2 November 2026, have replaced estimates with confirmed figures, and this rescoring reads against that confirmed quarter.
Grab at 54 is therefore neither a failed blitz nor a completed one. The on-demand platform proved product-market fit across eight countries, turned its first act profitable, and built a moat that is regionally strong and incentive-expensive. The financial second act is growing at a pace that would, on slope alone, rank among the fastest in the scored set, but it is growing with credit quality now partly visible (NPL 2.6% disclosed in Q3 2026). The governance structure concentrates control more tightly than at listing, and the profit line still leans on finance income more than operating profit alone would suggest. Those are the facts the score file supports, and they are sufficient to explain every point of the 54 without reaching for anything the file does not contain.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Q4 2026 · Expected
Coverage
Grab Holdings Limited · Q3 2026 reported Nov 2, 2026 · Score 54 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.