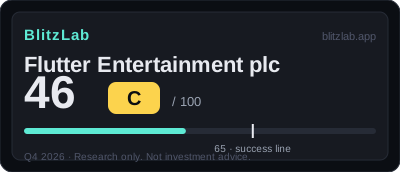
Flutter Entertainment plc — Blitz Index 46 (C)
Flutter scores 46 — the world's largest online betting operator, holding U.S. #1 share (39% sportsbook, 27% iGaming) while defense costs eat the margin.
Last re-scored: November 4, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 15 / 25 | TTM revenue $17,161M (+15.2%); FY2025 +17% — but Q2 2026 only +3% (organic +4%), U.S. −6%, guidance cut to $17.91B midpoint |
| B · Moat | 34 / 60 | Global #1 scale (14.3M AMP) + Flutter Edge pricing data + cross-brand sell; no true two-sided network effect (multihoming is routine), and distribution is paid (U.S. S&M +61% in Q2) |
| C · Creative destruction | 10 / 15 | Regulated online wallet replacing licensed retail and illegal/offshore operators; prediction-market bridge opens unopened states — replacement in progress, not complete |
| D · BlitzFailing | −13 | Net debt $10.48B, leverage 2.2x → 4.6x; FY2025 GAAP loss −$407M (India $556M impairment); Brazil closure + $873M impairment realized; four tax/regulatory fronts (UK, Illinois, Brazil, India) |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 56.7 · Speed 60 · Creative 66.7.
Watch item
Gates: G1 ✓ (weak pass — Q3 NFL season is the test) · G2 ✓ (tense pass on the global pool — bar ≈ $171.6B vs $293B 2024 global online GGR). 17 points below the threshold — first score.
Strengths
- World #1 at TTM $17.2B (+15.2%) — ~2.8x DKNG's $6.2B scale
- U.S. #1 held (sportsbook 39%, iGaming 27% GGR) + U.S. AMP +9%, direct-casino AMP +26%
- Second curve is real: FanDuel Predicts + market-making (~$50M expected in 2026), Brazil, Italy Snai integration, Alberta
- International +10% in Q2 — diversification offsetting U.S. weakness
- CEO transition executed as announced (Taylor took office 2026-10-01) — no governance gap
Concerns
- Q2 adjusted EBITDA −45%, U.S. −70% — defense costs overwhelming margin
- Leverage 4.3x (2x the end-2024 level) + net debt $10.48B — M&A debt aftermath
- Guidance cut (revenue −$395M, EBITDA −$210M at midpoint) — second cut in the sequence
- Four tax/regulatory fronts (UK, Illinois, Brazil, India) + federal-state clash over prediction markets
- Q2 group AMP −11% — management itself concedes market-growth slowdown
Research notes
Flutter Entertainment plc is the world's largest online sports-betting and iGaming operator, scored here at 46 out of 100, grade C, on BlitzLab v1.0 as of 25 October 2026. The section scores are A, Speed, 15 out of 25; B, Moat, 34 out of 60; C, Creative Destruction, 10 out of 15; and D, Demerits, minus 13. The arithmetic is 15 plus 34 plus 10 minus 13 equals 46. The score sits 19 points below the 65-point threshold, and no FLAG is attached, because demerits of 13 are below the 15-point FLAG line. That combination — a passing gate verdict, a mid-table grade, and no FLAG — is itself the story of this page. Flutter clears the bar to be scored, and then, on the evidence available at the as-of date, scores as a mature, defensive leader rather than as a company still blitzscaling its way to a new order.
The as-of date, T, is 25 October 2026. The latest results included are the second quarter of 2026, reported on 5 August 2026. The third-quarter 2026 update, expected in early November, is post-T and is therefore excluded from the scoring; it appears in this draft only as a future marker. The chief executive change is pre-T and is included: Dan Taylor took over from Peter Jackson on 1 October 2026, as previously announced. The classification in the score file is MATURE, and the revenue base makes that classification easy to understand. Trailing-twelve-month revenue was $17,161 million, up 15.2 percent on a calculated basis, after full-year 2025 revenue of $16,383 million, up 17 percent, and full-year 2024 revenue of $14,048 million. This is a first scoring for Flutter, with no blind test behind it, and it was nominated as an alternative candidate after DraftKings failed Gate 2 in an earlier batch. The contrast with that earlier case runs through the whole assessment, and it is worth stating plainly at the outset: Flutter and DraftKings compete in the same United States sports-betting market, but Flutter is scored on a global portfolio, and that global scope is what changes the gate verdict. It does not, by itself, produce a high score.
Thesis: the largest operator, defending rather than discovering
The thesis that the score file supports is narrower than the company's scale might suggest. Flutter is not, at T, a company proving a new market. It is a company defending a leading position in markets that are already regulated, already competitive, and increasingly taxed, while trying to open a second curve in prediction markets and in newly regulated geographies. The score file calls the Gate 1 pass a weak pass, and that qualifier matters more than the word pass. Growth is continuing, but the trajectory is decelerating, the most recent quarter is soft, and the file explicitly reserves the right to re-examine Gate 1 if the third quarter, which covers the National Football League season, shows no recovery in monthly active players or share. A reader who stops at "Gate 1 PASS, Gate 2 PASS" will misunderstand the assessment. Both gates pass, and both passes carry tension that the score file records rather than resolves.
Gate 1, sustained growth or a second growth curve, passes on confirmed evidence, with the weakness stated in the same breath. The trailing-twelve-month growth of 15.2 percent and the full-year 2025 growth of 17 percent are real, and the second curve is not merely a plan: FanDuel Predicts is operating, Brazil opened as a regulated market in January 2025, the Italian Snai business has been integrated, and Alberta has launched. At the same time, the second quarter of 2026 grew only 3 percent, with organic growth of 4 percent and United States revenue down 6 percent. The score file attributes that quarter to three overlapping pressures — a one-off regulatory shock from the closure of the business in India, which cost 17 percentage points of monthly active player growth, worse sports results in the United States, and deliberate reinvestment in promotion — and it treats the underlying demand signals as not extinguished, pointing to United States monthly active players up 9 percent and direct casino monthly active players up 26 percent. That is a defensible reading of the quarter, but it is not a strong one, and the file says so. The question it leaves open is whether the quarter was an investment or an erosion, and it assigns that question to the next reported quarter.
Gate 2, the requirement that a new market's ten-year ceiling be at least ten times current revenue, passes on an estimated basis, again with tension. The bar is $171.6 billion, ten times trailing-twelve-month revenue of $17,161 million. The comparison with DraftKings is instructive, and the score file draws it directly. DraftKings failed because its bar, $62.2 billion, exceeded a United States-only reachable ceiling of around $30 billion, with the United States sportsbook pool itself at more than $15.7 billion. Flutter is judged globally. Global online gross gaming revenue was $293 billion in 2024, according to H2 Gambling Capital figures cited via industry press in September 2026, with a forecast of $530 billion by 2030. Against those figures, the bar is 59 percent of the 2024 pool and 32 percent of the 2030 forecast. Extrapolated at around 10 percent compound annual growth, the pool would reach around $940 billion by 2036, which would require roughly 18 percent share for Flutter to reach the bar. Flutter's current global share is around 6 percent, calculated as $17.2 billion divided by $293 billion, so reaching the bar would require roughly tripling share. The score file's method, as it states it, is that a gate fails only if even an optimistic ceiling cannot be assembled to reach the bar; a requirement of roughly 18 to 32 percent share, as opposed to the 75 to 85 percent share requirement cited for the UPST-style case, is demanding but not impossible. That is a precise and limited claim. It is not a claim that the pool is large, and the file says so in terms: the argument is that the required share is not at an unattainable level. The same logic explains why the market-size item, B3, is scored 9 out of 12 rather than at the maximum. A full score would require demonstrated realisation of at least one of the structural openers that remain: expansion of United States iGaming, opening of California, Texas, or Florida, or a comparable step.
The structural openers are real, and they should not be dismissed. United States iGaming covers only around 11 percent of the population in the data pack cited by the score file, and California, Texas, and Florida remain unopened for sports betting. Brazil is maturing as a regulated market, and prediction markets are a further opener. But openers are not revenues, and the score file keeps that distinction. Flutter already holds leading shares in the United States, the United Kingdom, Italy, and Australia, which means further growth must come either from taking share in markets where it is already first, from opening markets that are currently closed, or from building a new vertical. Each of those paths is harder than the first wave of legalisation that built the current business.
Speed: growth that is decelerating, capital that is borrowed, share that is held
Speed, section A, is 15 out of 25, made up of A1 growth at 6 out of 10, A2 capital velocity at 3 out of 5, A3 hiring and productivity at 3 out of 5, and A4 share velocity at 3 out of 5. No item in this section reaches its maximum, and the pattern across the four items is consistent: the machinery of speed is present, but the headroom that once accompanied it has narrowed.
A1, growth, at 6, reflects a business that is still growing at scale but decelerating. Full-year 2025 growth of 17 percent and trailing-twelve-month growth of 15.2 percent are solid at a revenue base of around $17 billion, and the score file says so. The trajectory, however, points the other way: the second quarter grew 3 percent, organic growth was 4 percent, United States revenue fell 6 percent, and guidance was lowered, with the revenue midpoint moving from $18.4 billion to $17.91 billion. Acquisitions — Snai and Betnacional — explain part of the growth, so growth from organic operations alone cannot support a higher score. The cap the file places on this item is therefore not a judgement that growth has stopped; it is a judgement that, at this scale and with this mix of acquired and organic growth, the evidence does not support more than 6.
A2, capital velocity, at 3, captures a two-sided fact. Access to capital is demonstrated: the Snai and Betnacional acquisitions and the Boyd stake were all debt-funded, which proves that lenders will fund Flutter's expansion. The other side is heavier. Leverage rose from 2.2 times at the end of 2024 to 3.7 times at the end of 2025 and to 4.3 times at June 2026, net debt stood at $10.48 billion, and second-quarter interest expense rose $52 million year on year. Operating cash flow in the first half was positive at $693 million, but free cash flow on the company's own definition — which includes financing capital expenditure and excludes player funds — fell 56 percent in the second quarter. The score file's phrasing is blunt and accurate: there is speed in borrowing to acquire, but the cushion has thinned. A score of 3 records that the velocity exists and that the room to repeat it has shrunk.
A3, hiring and productivity, at 3, is scored at the midpoint largely because the evidence does not support a more precise judgement. Headcount was 28,518 at 31 December 2025, confirmed, including around 7,500 technology staff and around 3,500 software engineers. Revenue per employee was around $0.57 million on a calculated basis, but the score file warns that this figure includes retail and head-office staff and is therefore not a pure technology productivity measure. No year-by-year hiring series was available, so hiring speed could not be scored, and the midpoint follows. Turnover of 22 percent, with voluntary turnover of 11 percent, is recorded in the file, not as a demerit, but as a fact. A reader should not over-read this item: it says less about Flutter's engineering strength than about the limits of the disclosed data.
A4, share velocity, at 3, is the clearest expression of the defensive character of this business. Share was defended but not expanded in the second quarter. United States sportsbook share was 39 percent, down from 41 percent in the fourth quarter, and United States iGaming share was 27 percent, down from 28 percent in the fourth quarter. In both cases Flutter remains number one, and the score file stresses that point. But a quarter in which the leader's share falls in both of its two main United States verticals is not a quarter of share expansion, and the score reflects that. The positives that keep the item at 3 rather than lower are genuine: United States monthly active players rose 9 percent to 3.84 million, direct casino monthly active players rose 26 percent, and launches in Missouri and Alberta succeeded. The file's formulation is that defence plus entry into new markets supports 3, with demonstrated expansion required for 4. That is the right standard, and Flutter, at T, has not met the higher one.
Taken together, the Speed section describes a company that can still move — it launches, it acquires, it adds players in its core United States business — but whose movement is increasingly spent on holding ground. The distinction between speed that creates a lead and speed that preserves one is the central distinction of this assessment, and it recurs in every section that follows.
Moat: scale without a true network effect, distribution that is powerful and paid for
Moat, section B, is 34 out of 60, made up of B1 network effects at 8 out of 18, B2 distribution scalability at 11 out of 18, B3 market size at 9 out of 12, and B4 gross margin at 6 out of 12. The total is the largest section in the model, and Flutter's 34 is a middling result that reflects a real but limited moat. The most important thing to understand about this section is what Flutter's moat is not. It is not a network effect in the sense the Blitzscaling model means the term.
B1, network effects, at 8, is scored in the upper part of the 5 to 9 anchor band, and the reasoning is structural. Players do not increase the value of the product for other players in the way users of a marketplace or a social platform do, and multi-homing — holding accounts with several operators — is everyday behaviour. That caps the item well below its 18-point maximum, whatever the company's scale. What lifts the item to 8, above DraftKings, is scale of a different kind: the Flutter Edge pricing data operation across 14.3 million monthly active players, cross-selling between brands, a loyalty programme reaching 70 percent of United States customers, and the early construction of liquidity in prediction markets through market-making. Market-making revenue was $6 million in the quarter discussed in the file, with around $50 million expected for 2026. That last element is the only part of B1 that resembles a genuine network dynamic, because liquidity attracts further activity, but the file treats it as early-stage, and so should any reader. Prediction-market liquidity at this scale is a foothold, not a moat.
B2, distribution scalability, at 11, is the strongest item in the Moat section, and it is scored at the lower end of the 10 to 14 anchor band with the label "strong but paid for." The distribution model is app-centred, extended by state-by-state and country-by-country licences and by market-access partnerships. The launch playbook is demonstrated, not merely asserted: Missouri is described in the file as a record launch, Alberta outperformed Ontario, and the Italian and Brazilian integrations reached their milestones. That is a repeatable capability, and it is the closest thing Flutter has to a blitzscaling lever in its mature phase. The discount is equally concrete. Distribution is paid for, and its cost is rising fast: United States sales and marketing rose 61 percent in the second quarter, and international marketing rose 19 percent. A distribution system that scales only by spending more per unit of growth is scalable in the operational sense — Flutter can enter new jurisdictions — but not in the economic sense that the highest moat scores require. The score of 11 holds both halves of that sentence.
B3, market size, at 9, has been covered in the Gate 2 discussion above, and the item score follows the same logic. The global pool is large, Flutter is the world's largest operator, and yet its share is only around 6 percent. The market is more than three times the bar in the 2024 pool figure, but Flutter's reach depends on expanding share. The file reserves the maximum score for demonstrated realisation of one of the structural openers — United States iGaming expansion or the opening of California, Texas, or Florida — and none of those had been demonstrated at T. A score of 9 therefore records a large market without crediting Flutter for markets it has not yet entered.
B4, gross margin, at 6, is where the cost of defence becomes visible in the accounts. Gross margin was 45.2 percent in full-year 2025, confirmed, and 39.6 percent in the second quarter of 2026 on a calculated basis. The file warns that gaming taxes and the netting of promotions are embedded in cost, so the gross margin should not be read as a pure product margin. Adjusted EBITDA margin fell from 17.4 percent in full-year 2025 to 11.7 percent in the second quarter, a decline of 1,020 basis points, and the United States adjusted EBITDA margin fell from 22.3 percent to 7.1 percent. That collapse in the United States margin, in the same quarter in which United States sales and marketing rose 61 percent and United States revenue fell 6 percent, is the single most revealing combination of figures in the score file. Share-based compensation, at 1.5 percent, is small and is not the main cause of the gap between GAAP and adjusted results; depreciation and amortisation, impairments, and tax provisions are. The margin trajectory is downward, and the score of 6 records that direction rather than any single quarter's level.
The Moat section, read as a whole, describes a company whose advantages are real but expensive. It has the largest pricing-data scale in its industry, a proven licence-by-licence distribution playbook, and the largest revenue base. It does not have a network effect that compounds without spending, and its distribution costs are rising faster than its revenue. That is a moat, but it is a moat that must be continually repurchased.
Creative destruction: replacing an old order, incompletely and reversibly
Creative Destruction, section C, is 10 out of 15, made up of C1 order displaced at 4 out of 5, C2 irreversible behaviour change at 3 out of 5, and C3 cost-structure change at 3 out of 5. This is, proportionally, Flutter's strongest section — 66.7 on the 100-point radar conversion used in the score file, against 56.7 for Moat and 60.0 for Speed — and the ranking is informative. Flutter scores best where the question is whether it is changing how gambling is consumed, and worst where the question is whether that change is protected.
C1, order displaced, at 4, credits Flutter with replacing an older order: state-by-state licensing, retail counters, and illegal or offshore operators are being displaced by regulated online play in a single wallet. The prediction-market bridge is part of this story, because a federal structure allows customer acquisition in states that have not opened sports betting, and Flutter executes that bridge at number-one scale, as DraftKings does in its own way. The item stops at 4 rather than 5 because the displacement is not complete: online play is still growing as a share of the total gambling market, and the old order has not been fully replaced. That is a fair and important qualification. A company can be the agent of creative destruction in its sector without having finished the destruction.
C2, irreversible behaviour change, at 3, is scored in the "in progress" anchor band, and the evidence cuts both ways. Mobile in-play and parlay betting, and multi-vertical use within a single app, are established behaviours. But switching costs are low, and the file notes that a wave of customer churn after the fourth quarter of 2025 demonstrated that behaviour can reverse. Prediction-market trading as a new behaviour is at an early stage, with market-making of $6 million in the quarter. The score of 3 therefore records a change that has taken hold without claiming that it cannot be undone. In a market where every customer can hold several apps and where promotions move behaviour quarter to quarter, irreversibility is a strong claim, and the file does not make it.
C3, cost-structure change, at 3, records a claim that has not yet been demonstrated. The Flutter Edge pricing scale and a $500 million cost-saving target by 2029 are presented as a cost-structure improvement story, but the current cost trajectory runs in the opposite direction, with United States sales and marketing up 61 percent and United Kingdom taxes rising. Until savings are demonstrated, the score file holds the item at 3. This is consistent with the treatment of the same $500 million target elsewhere in the file: it is a management answer to the tax and cost front, not yet evidence that the front has been answered.
The Creative Destruction section thus gives Flutter credit for changing its industry's structure while withholding credit for making that change permanent or cheaper. That combination — real displacement, reversible behaviour, unproven cost improvement — is characteristic of a mature disruptor. The disruption has happened; the question is whether it endures on favourable economics.
Deductions and risks: debt, earnings quality, and a tax front on four sides
Demerits, section D, total minus 13, made up of D1 debt at minus 7 out of minus 10, D2 revenue quality at minus 2 out of minus 10, D3 governance at 0 out of minus 5, and D4 regulatory and social cost at minus 4 out of minus 5. The total is below the FLAG threshold, and the file is explicit that no FLAG attaches. But "no FLAG" should not be read as "no risk." The demerits are concentrated in exactly the two places a leveraged, regulated business would be expected to show strain: the balance sheet and the tax line.
D1, debt, at minus 6, is the largest single demerit, and the trajectory matters more than the level. Net debt of $10.48 billion is around 0.7 times trailing-twelve-month revenue, which by itself would not look extreme. Leverage of 4.3 times, having doubled from 2.2 times in eighteen months, is the concerning figure, and the score file draws the comparison with NBIS, scored at minus 7 on a pro forma debt load around ten times trailing-twelve-month revenue, to show that Flutter's demerit is lighter in level but steep in slope. The offsets are recorded: operating cash flow remains positive, free cash flow on the company's narrow definition remains positive, total assets are $28.2 billion, and equity is $8.75 billion. The demerit of minus 6 therefore says that the debt is serviceable and rising fast at the same time. Both halves are needed. A reader who cites only the asset base will miss the slope; a reader who cites only the slope will miss the cash generation.
D2, revenue quality, at minus 2, records no restatement and no audit issue, which is an important clearance. The demerit comes from volatility and judgement items rather than from accounting integrity. The full-year 2025 GAAP loss was minus $407 million, including the $556 million India impairment, and the second-quarter GAAP loss was minus $296 million, including a $95 million provision for past taxes. The gap between GAAP and adjusted results is therefore structural, not a one-off, and promotion dependence became explicit in the second quarter, when United States sales and marketing rose 61 percent while United States revenue fell 6 percent. The file is careful to say this is not accounting misconduct; it is volatility and judgement. The demerit of minus 2, small in absolute terms, is the right size for that distinction. It flags the earnings stream as noisy without impugning it.
D3, governance, at 0, records no trigger on the evidence reviewed. Flutter is a public limited company with a single class of ordinary shares, listed on both the New York Stock Exchange and the London Stock Exchange, and no controlling shareholder or differential voting rights were identified in the disclosures reviewed. The chief executive transition from Jackson to Taylor on 1 October 2026 was executed as announced, so there is no governance gap at T. The file notes, as a scope limitation, that Form 4 clusters were not reviewed, because they were outside the scope of this scoring. That limitation should be preserved when this draft is cited: a score of 0 on governance means no trigger was found in the material reviewed, not that every governance question has been examined.
D4, regulatory and social cost, at minus 3, is the item where the score file's language is most urgent, and it deserves the most careful reading. Four tax and regulatory fronts advanced at the same time. In the United Kingdom, a rise in remote gaming duty from 21 percent to 40 percent was reported in press coverage. In Illinois, a progressive gross gaming revenue tax reaching 40 percent was accompanied by a per-bet tax and a Chicago rate of 10.25 percent. In Brazil, the betting tax rose from 12 percent to 13 percent. In India, a ban on real-money games led to the closure of the Junglee business, a $556 million impairment, and a $62 million goods and services tax provision. Prediction markets add a further exposure: state attorneys general in Missouri and Ohio wrote letters in which FanDuel was not directly named, but the federal-versus-state tension applies to Flutter in the same way. The demerit is minus 3 rather than larger because no fine or penalty amount has been confirmed; the file states that a confirmed penalty would raise the demerit. The direction of the tax front, in other words, is adverse even though the accounting consequence is not yet fully determined. The score file's summary line on this point — that tax is a second business for Flutter — is not rhetorical flourish. It is a description of where management attention and margin are now going.
The three key drivers identified in the score file tie these sections together, and they are worth restating because they prevent a misreading of the total. First, passing the gates is a qualification to be scored, not a good score: the second quarter's deliberate reinvestment cut A1, B4, and D1 at the same time and left the company at 48. Second, the cost of defending number one is the centre of the score: United States sales and marketing up 61 percent against United States revenue down 6 percent, United States adjusted EBITDA down 70 percent, and a $270 million second-half EBITDA sacrifice announced by management as the price of shifting from margin growth to monthly active player growth. Third, tax is the second business, on four fronts at once, with India already realised as closure and impairment. A draft that reported only the 48 would miss all three; a draft that reported only the tax front would miss the scale and the defence.
What to watch: the quarter that judges the trade-off
The score file is unusually explicit about what would change its mind, and this section follows that explicitness rather than adding new predictions. The future markers are stated without anticipated outcomes, as the scoring rules require.
The first marker is the third-quarter 2026 update, expected in early November and therefore post-T. The score file names this quarter as the test of the investment thesis: it covers the National Football League season, and it is the quarter in which monthly active player and share recovery would show whether the second quarter's reinvestment was an investment or an erosion. Gate 1 is flagged for re-examination if that recovery does not appear. This draft records that marker and no more. It does not anticipate the quarter's result, and any future revision of this page should be grounded in the reported quarter rather than in an expectation formed before it.
The second marker is the tax front, and here the watch item is not news but absorption. The score file's own formulation is that the key variable after the third quarter is not tax news itself but whether tax increases are absorbed through pricing and promotion efficiency. That distinction is important. Tax rates are largely outside Flutter's control, as the file notes in its assessment of the largest blitzscaling risk: tax defeating the blitz by draining the cash flow that funds it. What is within the company's control is the efficiency with which it prices, promotes, and allocates marketing spend under higher taxes. The $500 million cost-saving target by 2029 is management's stated answer on this front, and its demonstration — or absence — belongs in the same watch list as the tax rates themselves.
The third marker is leverage and the acquisition model. Leverage doubled in eighteen months to 4.3 times on debt-funded acquisitions, and interest expense is rising. The watch item is whether operating cash flow, positive at $693 million in the first half, and free cash flow on the company's definition continue to support that leverage while the company also funds the defensive marketing spend described above. The score file does not present leverage as an imminent distress signal — assets and equity are recorded as offsets — but it presents the slope as the risk. A future assessment should therefore track the slope, not merely the level, and should distinguish between leverage that funds new regulated territory and leverage that funds defence of existing territory.
The fourth marker is prediction markets, where the watch item is scale and durability rather than existence. FanDuel Predicts is operating, market-making is expected to reach around $50 million for 2026, and the federal structure offers a route to customers in unopened states. The score file treats this as an early-stage second curve, and the relevant future evidence is whether liquidity and activity grow beyond the foothold, whether the federal-versus-state tension produces a confirmed consequence, and whether prediction-market customers convert into the broader Flutter wallet. None of that evidence was available at T, and none of it is anticipated here.
The fifth marker is the remaining structural openers: United States iGaming expansion beyond around 11 percent population coverage, and the opening of California, Texas, or Florida. The score file reserves a maximum market-size score for demonstrated realisation of one of these, and that reservation is itself a watch item. Until one of them is demonstrated, the Gate 2 pass remains a statement about required share rather than about realised reach.
Two notes on the score file itself should be preserved for any future editor of this page, because they concern how the file should be read rather than what it concludes. First, the file records conflicting reported share prices around 23 October 2026, around $80 on one report and around $102 on another, and records market capitalisation only as a range of around $14 billion to $18 billion, with a reported 52-week range of $72.56 to $255.26. The file explicitly does not use price in the score, and this draft follows that rule: no price, valuation, or market-capitalisation conclusion is drawn from those conflicting reports, and the tension is noted here rather than smoothed over. Second, the file contains a tension between its global and United States lenses that is intentional rather than erroneous: Flutter is scored globally for Gate 2 and as the United States number one for share, and the two lenses give different impressions of dominance — around 6 percent globally, 39 percent in United States sportsbook, 27 percent in United States iGaming. Quoting only the global figure would understate the United States position; quoting only the United States figures would overstate the global position. Both are preserved in this draft, with their scopes attached, and neither is adjusted to fit the other.
Flutter at 46/C is, in the end, a study in the difference between being the largest and being the fastest, and between passing a gate and earning a high score. The company has the largest revenue base in its industry, the leading share in its core market, a demonstrated licence-by-licence launch capability, and a second curve that exists in operating form. It also has decelerating growth, a margin that fell sharply in the quarter that mattered most, leverage that doubled in eighteen months, and a tax front advancing on four sides at once. The blitzscaling judgement that follows from those facts together is the one the score file reaches: a mature leader conducting a defensive blitz, spending margin to hold share, borrowing to widen territory, and waiting — with the rest of the market — for the next reported quarter to show whether the spending was an investment.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Q4 2026 · Expected
Coverage
Flutter Entertainment plc · Q3 2026 update Nov 4, 2026 (BMO) · Score 46 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.