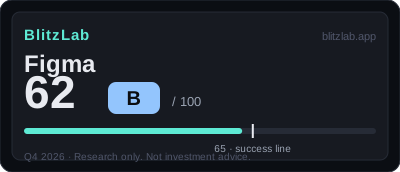
Figma — Blitz Index 62 (B)
3 straight quarters of acceleration at $1B+ scale — but the founder owns 72% of the votes.
Last re-scored: October 18, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 19 / 25 | Q2'26 revenue +48.3% — 3 straight accelerating quarters (38→48%); NDRR 136%; >$100K ARR +46% |
| B · Moat | 40 / 60 | Two-sided designer→developer network; 2/3 of MAU are non-designers; Fortune 500 95% use Figma |
| C · Creative destruction | 12 / 15 | AI credits as a second pricing engine — seats × usage; Make and Sites extend the canvas |
| D · BlitzFailing | −9 | Field 72.3% voting control + Nominating Agreement; recurring SBC ~50% of revenue; GM 91.2%→83.7% |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 66.7 · Speed 76 · Creative 80.
Watch item
Gates: G1 ✓ · G2 ✓ (borderline). 3 points below the threshold — the blitz is real, the governance discount is too.
Strengths
- Q2'26 revenue +48.3% — acceleration for 3 straight quarters at $1B+ scale (SEC)
- NDRR 136% + >$100K ARR +46% — enterprise expansion, quantified
- AI credit monetization's first full quarter — a second pricing engine running
- Fortune 500 at 95% adoption — the category definer's position
Concerns
- Recurring SBC ~50% of revenue + $2.1B unrecognized overhang — long dilution tail
- Field's 72.3% voting control + Nominating Agreement — founder-locked governance
- Gross margin 91.2%→83.7% — AI infrastructure cost pressure
- TAM $33B is company-commissioned research — biased ceiling
Research notes
1. Thesis: A Network Blitz, One Year Public, Three Points Short
Figma, Inc. enters this scoring period as a company still in the acceleration phase of its first blitz, and the most useful way to read its 62/B is as a portrait of a business whose operating evidence is stronger than its headline total suggests, with the gap explained almost entirely by two classic Silicon Valley discounts: stock-based compensation and founder control. The business score before demerits is 71 (Speed 19 + Moat 40 + Creative Destruction 12); demerits of 9 then bring it to 62, three points below the 65-point line that BlitzLab treats as success. No FLAG applies, because demerits of 9 sit below the 15-point FLAG line. The score therefore describes a company that is close to the success line but not across it, and the distance is measurable: normalisation of stock-based compensation and confirmation that the margin rebound is a trend rather than a single quarter are the two developments the score file names as conditions for crossing it.
The as-of discipline matters here, because Figma is a recently public company whose story moves quickly. This assessment is dated 18 October 2026. Its latest results are the second quarter of 2026, reported in the Form 10-Q filed on 5 August 2026 for the quarter ended 30 June 2026. Third-quarter 2026 results, due after the market close on 4 November 2026, fall after the as-of date and are excluded from the score. The company went public on 31 July 2025 at $33.00 per share, so at the as-of date it had been listed for less than fifteen months. Its classification in the model is GROWTH, with trailing-twelve-month revenue of approximately $1.28 billion and a market capitalisation of approximately $12.3 billion. Confidence in the scoring is rated high in the score file, resting on original filings reviewed directly through SEC EDGAR — the S-1, the 424B4 prospectus, the 10-K, the 10-Q, 8-K filings, and the DEF 14A proxy statement, together with inline XBRL — with some items explicitly marked as press-reported where the filing record does not carry them.
Figma's history already contains the single most legible piece of evidence in the whole file, and it predates the listing. In September 2022, Adobe agreed to acquire Figma for $20 billion, a figure the score file notes as approximately 50 times Figma's 2022 revenue. In December 2023, the two companies mutually terminated the agreement, and Figma received a $1 billion termination fee. That sequence does two kinds of work in this assessment. In the growth item, the $1 billion fee is treated strictly as 2023 non-operating revenue and excluded from the growth calculation, so it cannot flatter the operating trend. In the creative-destruction item, the attempted acquisition itself counts as evidence: an incumbent does not offer $20 billion for a company it regards as a minor irritant. The failed deal is therefore both a cleaned-up accounting item and a strategic datum, and the score file keeps those two treatments separate rather than letting one contaminate the other.
Both gates of the BlitzLab model pass, but they pass in different registers, and the difference sets the tone for everything that follows. Gate 1, which asks whether growth continues or a second growth curve exists, passes on confirmed figures. Gate 2, which asks whether the ten-year ceiling of the new market is at least ten times current revenue, passes on an estimate and is explicitly marked borderline, with the definition of the market itself flagged as the prior question. A reader who understands that asymmetry — a confirmed first gate and a borderline second gate — will understand why the moat subscore is the most debated part of this assessment, why the market-size item stops at 9 out of 12, and why the "what to watch" section returns repeatedly to whether the artificial-intelligence expansion of the market is real or definitional.
2. Speed: Acceleration at a Scale Above $1 Billion
Speed scores 19 out of 25, and on the score file's own radar conversion that is 76.0 on a 100-point scale, the second-strongest of the three axes. The composition is instructive: growth 8 out of 10, capital velocity 4 out of 5, hiring and productivity 3 out of 5, and share velocity 4 out of 5. Nothing in the speed subscore is weak; the points given up are the points of a company whose evidence is excellent but whose scale, measurement limits, and share-price history each impose a small, stated discount.
Growth itself earns 8 out of 10, and the quarterly sequence is the reason. Revenue grew 38.0 percent year on year in the third quarter of 2025, then 40.0 percent in the fourth quarter of 2025, then 46.1 percent in the first quarter of 2026, then 48.3 percent in the second quarter of 2026 — acceleration for three consecutive quarters, all on confirmed SEC figures. Second-quarter 2026 revenue was $370.1 million, up 48.3 percent. Fiscal 2025 revenue was $1,055.8 million, up 41.0 percent, and trailing-twelve-month revenue at the as-of date was $1,281.5 million. Fiscal 2026 guidance of $1.463 billion to $1.467 billion, whose midpoint implies growth of approximately 39 percent and which the score file records as raised, points to continued expansion rather than a plateau. The score file is explicit about why the mark stops at 8 rather than 9: growth of 48 percent at a scale above $1 billion is among the best in the measured set, but a base effect still applies, so the 9-point mark was kept back. That restraint is worth noting because it shows the model's conservatism operating in Figma's favour in one place and against it in another: the same acceleration that earns the high mark is not allowed to earn the top mark on a single print, however striking.
Capital velocity earns 4 out of 5, and the balance-sheet facts behind it are straightforward. Cash of $445.8 million plus marketable securities of $1,221.3 million gives total liquid resources of $1,667.1 million, all on confirmed SEC figures. A $500 million revolving credit facility stood undrawn, with a balance of zero. The initial public offering raised approximately $411.6 million in new-share proceeds, and operating cash flow for the first six months of 2026 was positive at $158.2 million. Access to capital, on that evidence, is sound: a company with $1.67 billion of liquid resources, an undrawn revolver, and positive operating cash flow is not capital-constrained in any near-term sense. The single point given up records the other side of the listing story. The share price at the as-of window was $21.49 on 16 October 2026 on a press-reported basis, down 35 percent from the $33.00 offering price, which means any further equity raise would be struck from a lower price and would carry greater dilution sensitivity. The score file keeps those two judgments distinct — capital access itself is good, so the mark is 4, while the dilution sensitivity of a future raise is the reason it is not 5 — and the distinction matters for reading the demerit section later, where dilution reappears in a different form.
Hiring and productivity earn 3 out of 5, the most middling item in the speed subscore. Headcount was 1,886 at December 2025 on confirmed SEC figures, up steadily from 1,014 in 2022. Revenue per employee for fiscal 2025, calculated from those figures, was approximately $560,000. The score file's judgment is compact: hiring is in blitz mode, but productivity indicators sit at the level of the software-as-a-service average rather than above it, so the mark is 3. That is a useful corrective to any reading of Figma as a company firing on every cylinder at once. The top line is accelerating, the customer counts are expanding, and the workforce has nearly doubled since 2022, yet the revenue generated per employee does not yet distinguish the company from its peers. If the artificial-intelligence products now being monetised raise output per employee, this item has room to move; on the evidence available at the as-of date, it has not yet done so.
Share velocity earns 4 out of 5, and its reasoning rests on a category-definer claim rather than a measured market share. On confirmed S-1 figures, 95 percent of the Fortune 500 and 78 percent of the Forbes Global 2000 use Figma. Against the Morgan Stanley estimate of the addressable market, penetration is approximately 4 percent on a press-reported basis — but the score file immediately qualifies that figure, noting that penetration is measured on a user-count basis while conversion of those users into revenue is still in progress. The top ten customers account for less than 10 percent of the total on a press-reported basis, indicating a dispersed customer base rather than concentration in a few large accounts. No quantified market-share figure is confirmed in the file, and the score is honest about that gap; the 4 points rest on the judgment that a product used by 95 percent of the Fortune 500 is, in substance, the standard of its category, even though the share itself cannot yet be expressed as a verified percentage. The point not awarded is the price of that missing quantification.
3. Moat: A Two-Sided Network Acquiring a Second Billing Engine
Moat scores 40 out of 60, or 66.7 on the 100-point radar conversion — the lowest of the three axes in converted terms, and the subscore where the assessment is most interesting. Its items are network effects 11 out of 18, distribution scalability 13 out of 18, market size 9 out of 12, and gross margin 7 out of 12. Read together, they describe a moat that is real and demonstrable in its first half — the network and the distribution — and still contested in its second half, where the size of the market and the cost of serving it with artificial intelligence are both under active negotiation with reality.
Network effects earn 11 out of 18. The mechanism is two-sided: designers enter, and developers, product managers, and marketers follow, so that the product spreads across job functions inside a customer rather than remaining confined to a single team. The quantitative anchor is confirmed in SEC filings: approximately two-thirds of monthly active users are non-designers. That single proportion does more work than any slogan about collaboration, because it shows the network crossing the boundary of its original profession. The annual report directly links the launch of Dev Mode, the product that connects design to code handoff, to the expansion of net dollar retention in 2024, giving the network claim a documented causal link rather than a merely asserted one. Net dollar retention itself was 136 percent in the second quarter of 2026 on confirmed SEC figures, but the score file attaches a methodology caution that any careful reader must carry forward: the retention denominator covers only customers with more than $10,000 in annual recurring revenue, so the 136 percent figure describes expansion inside the larger-customer cohort, not across the entire base. A community and plug-in ecosystem adds a further layer of reinforcement. Against all of that, the score file records the central risk in the company's own annual report: the generalisation of artificial-intelligence generation tools could bypass the moat rather than confront it. If creation itself becomes a commodity capability embedded in tools that every team already uses, the network's defensibility is tested not by a rival design tool but by a change in what "design" means as an activity. The mark of 11 reflects both halves of that picture: a demonstrated two-sided network, and a bypass risk stated in the company's own disclosure.
Distribution scalability earns 13 out of 18, the highest moat item, and it is where the second growth curve becomes concrete. The billing model now has two engines. The first is the established per-seat subscription, whose expansion is visible in the customer counts: customers above $100,000 in annual recurring revenue numbered 1,635, up 46 percent year on year on confirmed SEC figures, and deferred revenue reached $626.8 million, up 64 percent from $381.4 million in December 2024. The second engine is artificial-intelligence credit monetisation. The transition to enforced credit limits took place in March 2026, and the second quarter of 2026 was the first full quarter of monetisation on that basis, a timing point attributed to the chief financial officer and recorded on SEC and press-reported sources. Approximately 75 percent of customers above $10,000 in annual recurring revenue consumed artificial-intelligence credits weekly, on a press-reported basis, and weekly active users of Figma Make rose 70 percent quarter on quarter, also press-reported. Seat expansion and usage-based add-ons are therefore operating together: the seat count widens the base, and credit consumption deepens revenue inside the base. The score file's judgment that this dual engine "is working" is deliberately present-tense and deliberately narrow — it is a claim about the second quarter of 2026, not a forecast about the durability of credit pricing, and the margin section below explains why that narrowness is appropriate.
Market size earns 9 out of 12, and this is where Gate 2's borderline status enters the item scores. The gate arithmetic is as follows. Ten times trailing-twelve-month revenue of $1,281.5 million sets a bar of approximately $12.8 billion; on fiscal 2026 guidance of approximately $1.465 billion, the bar is approximately $14.7 billion, marked as an estimate. Against a static addressable market, the bar demands a great deal: the company's own estimate of $33 billion, drawn from its S-1 and based on research it commissioned from IDC, and the external Morgan Stanley estimate of approximately $26 billion on a press-reported basis, imply that the bar requires 39 to 57 percent share of the market as currently defined. The score file flags the bias caution on the company-commissioned figure explicitly, and the pass rests on three arguments rather than on the static arithmetic. First, ten times current revenue corresponds to a compound annual growth rate of 25.9 percent over ten years, which leaves headroom against a current trajectory of 48 percent growth. Second, the market is not static: credit monetisation, with approximately 75 percent of larger customers consuming credits weekly on a press-reported basis, together with Make, Sites, and Weave, is expanding the category toward what the file calls "AI-native creation," and under an assumed artificial-intelligence-expanded market of approximately $40 billion to $50 billion the bar falls to 26 to 37 percent share. Third, a category definer used by 95 percent of the Fortune 500 faces a different share ceiling from a late entrant. The pass is granted, but the file insists that the definition of the market is itself the prior question, and the item mark of 9 reflects that tightness: the ceiling is reachable under the optimistic scenario, but the assumptions about market definition and share are demanding. The file also draws a useful contrast with another scored company, ARM, whose case failed differently: there the company's own revenue goal fell short of the bar, whereas here the question is the ceiling of the market, with an expansion path that is being demonstrated in real quarters rather than merely asserted.
Gross margin earns 7 out of 12, and its trajectory is the most watched line in the whole assessment. Gross margin was 91.2 percent in fiscal 2023, passed through 88.3 percent, and reached 82.4 percent in fiscal 2025, then fell further to 79.4 percent in the first quarter of 2026 before rebounding to 83.7 percent in the second quarter of 2026, all on confirmed SEC figures. The cause of the decline is identified precisely in the quarterly filing: of the $81.8 million increase in cost of revenue in the first six months of 2026, $60.8 million was artificial-intelligence infrastructure and hosting cost. Non-GAAP operating margin in the second quarter of 2026 was 10 percent on confirmed SEC figures. The score file's judgment is balanced to the point of symmetry: the cause of the margin pressure is clearly growth spending on artificial intelligence rather than pricing collapse or competitive discounting, which is the benign form of margin pressure, but the reversal has only one quarter behind it, so it cannot yet be called a trend. Two further quarters of evidence are the stated test, and the mark of 7 records exactly that position — credit for a rebound whose cause is understood, without yet granting the higher mark that a confirmed reversal would earn.
4. Creative Destruction: From Files to Links, and From a Tool to a Workflow
Creative destruction scores 12 out of 15, or 80.0 on the radar conversion — the strongest axis, and the one where Figma's case is least contestable. Its items are the order being displaced 5 out of 5, irreversible behaviour change 4 out of 5, and cost-structure change 3 out of 5. The full mark on the first item is rare in this scoring set, and the file earns it with a story that is unusually clean.
The order being displaced earns 5 out of 5. The old order is the desktop, file-based design workflow — the world of Adobe XD, Sketch, and InVision-type tools, in which a design lived in a file, on a machine, passed between people by sending copies. The replacement is browser-based multiplayer collaboration in which the design lives at a web address rather than in a file, and in which many people can work in the same artifact at the same time. Dev Mode then integrates the handoff from design to code, extending the displacement from the design step into the adjacent engineering step. The score file treats Adobe's $20 billion defensive acquisition attempt as itself evidence of destruction: an incumbent does not attempt to acquire, at approximately 50 times the target's 2022 revenue, a company that has not already displaced something it values. The second act is then named: Make, Sites, and Weave extend the span from "idea to launch," moving the company from the design step toward the full span of bringing a product into existence, on confirmed SEC sources. A full mark here does not claim that the second act is complete; it claims that the first displacement is complete and standard-setting, and that the second act is underway on the same architectural logic.
Irreversible behaviour change earns 4 out of 5. The evidence is the composition of usage rather than any single product launch. Non-designers are approximately two-thirds of monthly active users on confirmed SEC figures, which means the product has crossed from being "a design tool" to being the workflow of the whole product organisation. Customers above $10,000 in annual recurring revenue grew from 7,233 in 2023 to 15,964 by June 2026 on confirmed SEC figures, a more-than-doubling that shows the behaviour spreading inside larger organisations, not merely accumulating free or small users. The first full quarter of artificial-intelligence credit monetisation, on SEC and press-reported sources, adds a usage-based behaviour on top of the seat-based one. The point not awarded records the difference between a collaboration standard that is hard to reverse and a transformation that is fully locked in: the lock-in of a shared working artifact is strong, but the artificial-intelligence layer that would deepen it is one quarter old as a monetised behaviour, and the file does not award the final point for a habit still forming.
Cost-structure change earns 3 out of 5, and its reasoning is the most two-sided in the creative-destruction subscore. For users, the change is a genuine removal of cost: a browser-based product eliminates installation and licence-management expense, the friction that desktop software imposed on every seat. For the company, however, the same transition creates a new cost: artificial-intelligence inference expense, including the cost of beta products whose usage is not yet deducted from credits and is therefore borne by the company, on a press-reported basis. The beneficiary and the bearer of the cost-structure change are therefore different parties pulling in opposite directions — users gain a collapsed cost structure while the company absorbs a new one — and the mark of 3 records that split rather than resolving it in either direction. Whether the company's new inference cost can be converted, through credit pricing, into a cost structure that users bear willingly is the same question the margin section poses, and it is no accident that the two items point at each other.
5. Deductions and Risks: The Two Bills Attached to the Blitz
Demerits total −9, composed of debt −4, revenue quality 0, governance −4, and regulation and social cost −1. The shape of that total is more informative than its size. Figma carries no debt problem and no accounting problem; its two bills are dilution and control, and both are structural rather than episodic. A reader who wants the short version of why a company with 48 percent growth and a 136 percent retention print sits at 62 rather than 71 can stop here: $2.1 billion of unrecognised stock compensation overhang, recurring stock compensation near half of revenue, and a founder who controls 72.3 percent of the vote.
Debt earns −4 out of a possible −10, and the apparent paradox — a company with no borrowings receiving a debt-item demerit — is resolved once the item's actual substance is stated. The revolving facility balance is zero on confirmed SEC figures, so there is no leverage problem in the ordinary sense. The demerit is stock-based compensation treated as the economic equivalent of a claim on future cash flows and ownership. Fiscal 2025 stock-based compensation was $1,364.1 million, equal to 129 percent of revenue, but that figure includes a $975.7 million one-off charge connected with the offering, and the score file separates the one-off from the recurring level rather than penalising the company twice for a single event. The recurring level is what matters: $169.0 million in the first quarter of 2026 and $147.6 million in the second quarter of 2026, together described in the file as roughly 40 to 51 percent of revenue on confirmed SEC figures. For scale, the file notes that this recurring rate is approximately double the 24.5 percent rate recorded for another scored company, ZS, which drew a −3. On top of the recurring flow sits the stock: approximately $2.1 billion of unrecognised stock-based compensation remains, comprising $1.4 billion of restricted stock units plus $652.8 million across two chief-executive awards plus restricted stock awards, all on confirmed SEC figures. Class A shares also diluted by 3.2 percent over the half year on confirmed SEC figures. The −4 therefore records a long overhang, not a single quarter's expense: even if the recurring rate falls, the $2.1 billion already promised will work its way through the share count in future periods. This is the price, in the score file's framing, of the blitz's fuel — talent acquired with equity — and it is a price paid by existing owners of the stock over time rather than by the company in cash today.
Revenue quality earns 0, the no-trigger mark, and its cleanliness is worth stating plainly because it narrows the risk story. On the disclosure history reviewed, there is no revenue restatement, no auditor change, and no mention of a material weakness in internal control over financial reporting. The Adobe termination fee was disclosed cleanly as non-operating revenue, separated from operating results rather than blended into them. Artificial-intelligence-related reputational and legal risks appear as risk factors, but the file records them as risk factors rather than accounting issues, and they do not trigger this item. A zero here does not mean the company is risk-free; it means the risks it carries are not of the kind this item measures, which is precisely why the governance and dilution items carry the weight they do.
Governance earns −4 out of a possible −5, the joint-largest demerit, and the facts behind it are confirmed in the definitive proxy statement. Founder Dylan Field controls 72.3 percent of the vote, through the Class B 15:1 structure together with the Wallace proxy. The score file places that figure against its own anchor line for differential voting: TOST at 51 percent drew −3, RBLX at 58.8 percent drew −3, and DUOL at approximately 76 percent drew −4, so 72.3 percent sits in the DUOL band. But the vote share alone is not the whole item. A nominating agreement requires Field to be included as a candidate at every annual meeting, a board-control device confirmed in the S-1 and characterised in the file as being of the long-term-board type, and after the Trigger Date only the board itself fills vacancies. Absolute voting control combined with a device that entrenches board candidacy is the combination that earns −4 rather than −3: the vote decides outcomes, and the agreement constrains who can even contest them. The score file's blitzscaling analysis names this as the single largest failure point of the company's blitz, in a sentence worth quoting in substance: the speed of the blitz is tied to one person's judgment, and in a structure the board cannot check, if the direction of the artificial-intelligence transition is wrong, there is no correction mechanism. That is a governance risk stated at its maximum clarity, and it is the reason the governance item, not the margin item, is the risk a reader of this assessment should carry forward most seriously.
Regulation and social cost earn −1 out of a possible −5, the lightest demerit, and its narrowness is deliberate. The core business is a single product, Figma Design, while Make, Sites, and Weave — the 2025 additions — have not yet had their revenue contribution separately disclosed on confirmed SEC sources. The deduction is limited to that single-product concentration. Artificial-intelligence competition risk, stated in the company's own annual report, is recorded as a concern rather than as an additional deduction, keeping the item's scope tight. The overall risk picture is therefore concentrated rather than diffuse: no debt distress, no accounting trigger, a light single-product deduction, and two heavy structural items — dilution and control — that together account for 8 of the 9 demerit points.
Two further risks sit outside the demerit total but inside a complete reading of the file. The first is the bypass risk already noted under network effects: general-purpose artificial-intelligence generation tools could go around the moat rather than through it, a risk the annual report itself raises. The second is the margin question: artificial-intelligence infrastructure cost has already moved gross margin from 91.2 percent to the low eighties, and the second-quarter rebound to 83.7 percent is a single data point. Neither risk is scored as a separate demerit, but both belong in the watch list, because either one, if it develops adversely, would reach the scored items through the network, distribution, or margin channels.
6. What to Watch
Several observable markers will decide whether this 62/B rises toward and across the 65-point line, stays level, or falls, and each of them is already named in the score file's evidence rather than invented for this section. The first is the third-quarter 2026 result due after the market close on 4 November 2026, which falls outside this assessment and will be the first new evidence on every marker below. It should be read against the second-quarter baseline recorded here — revenue of $370.1 million growing 48.3 percent, net dollar retention of 136 percent on the larger-customer cohort, gross margin of 83.7 percent — rather than against expectations formed after the fact.
The second marker is the margin trend. The file's stated test is two further quarters: if gross margin stabilises or rises from the second-quarter level of 83.7 percent, the rebound begins to look like a trend reversal, and the margin item has room to move above 7; if it resumes falling toward the first-quarter level of 79.4 percent, the pressure looks structural and the question becomes whether credit pricing can carry the inference cost. The composition of cost growth is the detail to follow inside that headline: in the first six months of 2026, $60.8 million of the $81.8 million increase in cost of revenue was artificial-intelligence infrastructure and hosting, so the margin story and the artificial-intelligence spending story are the same story told in two places.
The third marker is the normalisation of stock-based compensation. The recurring quarterly figures of $169.0 million and $147.6 million, at roughly 40 to 51 percent of revenue, are the baseline; a sustained decline in that rate, and a reduction in the approximately $2.1 billion unrecognised balance as awards vest, would ease the debt item's −4. The file's v1.1 candidate notes record this as a model question for the future — finer bands for recurring compensation rates, separating offering one-offs from recurring levels — but the underlying company fact to observe needs no model change: whether equity paid to talent falls as a share of revenue as the revenue base grows.
The fourth marker is the breadth and durability of the second billing engine. The second quarter of 2026 was the first full quarter of credit monetisation; the questions now are whether weekly credit consumption by approximately 75 percent of larger customers, on a press-reported basis, persists beyond the novelty of the new products, whether Figma Make's weekly active user growth of 70 percent quarter on quarter, also press-reported, continues, and whether Make, Sites, and Weave acquire separately disclosed revenue so that their contribution can be verified rather than inferred from usage anecdotes. Until that separation appears, the single-product concentration deduction and the distribution item's reliance on usage evidence both remain as they are.
The fifth marker is retention quality. Net dollar retention of 136 percent is a strong print, but its denominator covers only customers above $10,000 in annual recurring revenue, so the figure to watch alongside it is the broadening of the customer counts: customers above $100,000 in annual recurring revenue, at 1,635 and growing 46 percent year on year, and customers above $10,000, at 15,964 by June 2026, up from 7,233 in 2023. If the larger-customer cohorts keep expanding at those rates while deferred revenue, at $626.8 million, keeps growing, the network story gains a second and third confirming line; if cohort growth slows while the headline retention print stays high, the methodology caution in the file becomes the more important part of the story.
The sixth marker is the Gate 2 question in its empirical form: does the artificial-intelligence expansion of the market materialise as revenue, or does it remain a definitional argument? The gate passed on the combination of a 25.9 percent required growth rate against a 48 percent current trajectory, an assumed expanded market of approximately $40 billion to $50 billion, and the category-definer position of 95 percent Fortune 500 usage. Each leg of that argument now has an observable counterpart: the growth rate in the next two quarters, the credit revenue that would validate the expanded market, and the penetration of the Morgan Stanley estimated market beyond the current approximately 4 percent on a press-reported, user-count basis. The valuation note, which the model deliberately excludes from the score, records the price facts separately for readers who track them: a share price of $21.49 on 16 October 2026, a market capitalisation of approximately $12.3 billion, and an enterprise-value-to-trailing-revenue multiple of 8.1 times, all on a press-reported basis, with the price down 35 percent from the $33.00 offering price and down 81 percent from the first-day closing price of $115.50, also press-reported. The business score does not look at price, and this draft follows that rule: the price facts are recorded here, labelled as press-reported, and kept apart from the score.
Figma at 62/B is, in the end, a portrait of a network blitz in its first public year: a product that replaced the file with the link and became the standard of its category, now acquiring a second billing engine in artificial-intelligence credits while its margin absorbs the cost of that transition, and carrying two structural bills — equity dilution and founder control — that explain nearly the whole distance between its operating evidence and its headline score. The business before demerits scores 71; the demerits take 9 points; three points separate the company from the 65-point line. Whether those three points close will be decided less by whether the network keeps growing — on the current evidence, it is — than by whether compensation normalises, whether the margin rebound becomes a trend, and whether the second billing engine proves durable enough to expand the market it is now being asked to define.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Q4 2026 · Expected
Coverage
Figma, Inc. · Q3 2026 due Nov 4, 2026 (AMC, confirmed) · Score 62 · Grade B
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.