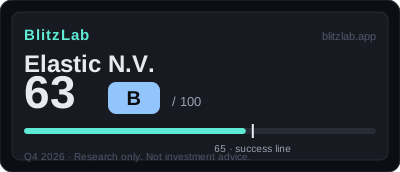
Elastic N.V. — Blitz Index 63 (B)
Elastic scores 63 — a re-accelerating search platform two points below the 65 line, with record enterprise customer adds and a margin guide to prove.
Last re-scored: October 25, 2026.
Confidence: High · Category: platforms
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 18 / 25 | FY2026 +17.3% → TTM +16.2%, Q1 FY2027 +15.1% (constant-currency acceleration); $100k+ customers +80 net adds (record quarter) |
| B · Moat | 39 / 60 | One search/data foundation under search, observability, security; 76.1% FY2026 gross margin; $100k+ AI usage 37% — but AI revenue undisclosed, S&M 40.8% of revenue |
| C · Creative destruction | 11 / 15 | Fragmented legacy (keyword search, APM/log tools, legacy SIEM) consolidating onto one platform; CISA SIEM-as-a-service expansion as proof |
| D · BlitzFailing | −5 | SBC $298.4M (17.2% of revenue) outruns buybacks; FY2026 GAAP profit depends on a $434.9M one-off tax valuation-allowance release (GAAP operating loss −$33.5M) |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 65 · Speed 72 · Creative 73.3.
Watch item
Gates: G1 ✓ · G2 ✓ (estimate — bar ≈ $18.0B vs $100B+ search/observability/security TAM). 2 points below the threshold — first score.
Strengths
- Revenue +17% (FY2026) → TTM +16.2% with constant-currency acceleration — re-acceleration, not decline
- Sales-led subscription +18–20%, cloud +22% — 94% subscription mix
- cRPO +21%, RPO +27%, non-current RPO +43% — sold future rising
- $100k+ customers +80 net adds (record quarter); $1M+ cohort >240; $5M+ cohort +30%
- Net cash ~$890M + 20% adjusted FCF margin — self-funded growth
- AI penetration 37% among $100k+ customers (670+ customers) — embedding as the retrieval layer
Concerns
- Net revenue retention 112% → 111% — existing-customer expansion cooling
- Gross margin 76.7% → 74.5% in Q1 — serverless and inference costs biting
- SBC $298M (17.2% of revenue) — buybacks do not offset dilution
- FY2026 GAAP profit rests on a $434.9M one-off tax release — headline overstates the operating picture
- AI revenue undisclosed — the AI thesis has no revenue proof yet
- OpenSearch fork (AWS-backed) as a standing competitive overhang
Research notes
1. Current Position
Elastic N.V. (NYSE: ESTC, CIK 1707753) scores 63 out of 100, Grade B, on the BlitzLab v1.0 model in the 2026Q4 scoring round, assessed as of 25 October 2026. The arithmetic is worth stating first, because the rest of this assessment is an attempt to explain how the parts add up and why the total stops two points short of the line that matters most in this model. Speed contributes 18 of 25 points, Moat contributes 39 of 60, Creative Destruction contributes 11 of 15, and Demerits subtract 5, so 18 plus 39 plus 11 minus 5 equals 63. On the radar axes that BlitzLab derives from those sections, Moat converts to 65.0 on a 100-point scale, Speed to 72.0, and Creative Destruction to 73.3. The company is classified as mature, with trailing-twelve-month revenue of about 1.80 billion dollars, precisely 1,802.1 million dollars in the score file, and it clears both gates. It carries no FLAG, since demerits of 5 sit well below the 15-point FLAG trigger. But it does not clear the 65-point threshold that BlitzLab uses as its success line: at 63, it falls short by two points. In the score file's own language, this is a "near-club" company, a phrase that captures the whole assessment in miniature. The moat and the creative-destruction sections are already at club standard; the speed section is what keeps the total below the line.
That framing matters because it changes how the growth figures should be read. Elastic is not a company whose growth has disappeared, and it is not a company still waiting for a second growth curve to arrive. Its fiscal year ends on 30 April, so the latest results inside the assessment window are the first quarter of fiscal 2027, announced on 27 August 2026, with the quarterly filing dated 28 August 2026. The fiscal 2026 annual filing is dated 8 June 2026. Revenue grew 17.3 percent in fiscal 2026, then 16.2 percent on a trailing-twelve-month basis by calculation, and 15.1 percent in the first quarter of fiscal 2027, with acceleration on a constant-currency basis according to the company. The score file treats that sequence as re-acceleration rather than deceleration, and the distinction is important. A company growing at 15 to 17 percent after passing 1.8 billion dollars in trailing revenue is not coasting on a small base, but it is also not growing at the 30 percent-plus pace that the model associates with hypergrowth. The growth item, A1, scores 7 of 10 for exactly that reason: the pace sits in a 15 to 20 percent band of re-acceleration, and a higher score would require the score file's stated evidence of a return to growth in the 20 percent range together with a recovery in net expansion.
Gate G1, which asks whether growth is sustained or a second growth curve exists, is marked as a confirmed pass, and the evidence is broader than the headline revenue line. The second curve is demonstrated, in the score file's words, by customer counts rather than by assertion. The share of larger customers using artificial intelligence rose from 21 percent to 37 percent over one year, reaching more than 670 customers, with a quarterly net addition of 70. Committed revenue also points forward: current remaining performance obligations rose 21 percent, total remaining performance obligations rose 27 percent, and non-current remaining performance obligations rose 43 percent in fiscal 2026. The score file calls this "sold future" growth, and the phrase is apt. Revenue already booked as future obligation is not yet revenue, but it is a contract, and contracts are harder to dismiss than narratives. The largest-customer cohort added 80 net customers in a single quarter, described in the score file as a record, which the file reads as accelerating sales execution. There are deceleration signals too, and the score file does not hide them: net expansion fell from 112 percent to 111 percent, and gross margin fell from 76.7 percent to 74.5 percent. The file's judgement is that these are declines in lagging indicators rather than the disappearance of growth, and that judgement is what carries the confirmed pass.
Gate G2, which asks whether the ten-year ceiling of a new market reaches at least ten times current revenue, is marked as a pass on estimates, and the arithmetic behind it is unusually transparent. The bar is trailing revenue of 1,802.1 million dollars multiplied by ten, which gives 18.0 billion dollars. The new market is defined as the enterprise artificial-intelligence search and retrieval layer, together with observability and the security platform. The combined enterprise total addressable market of those three solution areas is described, on a press-reported frame, as well above 100 billion dollars, and far larger still once artificial-intelligence infrastructure spending is included. The bar is therefore only 18 percent of a 100 billion dollar market, and the share Elastic would need to reach it is in the single digits to low double digits. The score file contrasts this with two kinds of failure it has seen elsewhere: a bar larger than the entire market, and a bar requiring a dominant share of three-quarters or more. Elastic's case is neither. The binding constraint, in the file's judgement, is not market size but execution, above all whether the fiscal 2027 operating-margin guidance of 19.4 percent is achieved. Total remaining performance obligations of 1,854 million dollars already amount to 10.3 percent of the bar, and current remaining performance obligations stand at 1,153 million dollars, so the company is not starting from zero against that ceiling.
One further figure belongs in this opening section, clearly labelled so that it is not mistaken for part of the score. The score file carries a valuation note that is explicitly not reflected in the score, because the business score does not look at price. On a press-reported, unconfirmed basis, a share price of about 84 dollars in late August 2026 multiplied by about 105 million shares implies a market capitalisation of about 8.8 billion dollars, and a price-to-sales multiple of about 4.9 times on trailing revenue. That note is included here only for context, with the same labels the score file applies, and it plays no part in any of the item scores that follow.
2. Moat
The Moat section, at 39 of 60, is the largest block of the score, and it is also the most layered, because Elastic's defensibility does not come from a single source. It comes from a platform foundation, from a large addressable market, and from a gross margin structure that is, by enterprise software standards, at the top end. The weakest of the four moat items is also the most conceptually interesting, because it forces a distinction between a true network effect and something that behaves like one without being one.
The first item, B1 on network effects, scores 9 of 18. Elastic has no genuine two-sided network effect, and the score file says so plainly. More customers do not directly make another customer's product better in the way that more users make a marketplace or a social platform better. What Elastic has instead is a data and ecosystem effect built on a single foundation. Search, observability, and security all sit on one search and data foundation, and the artificial-intelligence additions — a vector database, embeddings, a reranker, and an Agent Builder — widen that stack rather than replacing it. The company reports, on a press-reported basis, that customers using artificial intelligence show a higher propensity to expand, and the count of such customers, more than 670, representing 37 percent of larger customers, is the quantitative anchor for that claim. The score sits at the top of the 5 to 9 anchor band rather than higher, and the reason is a fork. The existence of OpenSearch, a fork of the underlying technology, prevents entry into the 10-point range and above, because a customer that wants the same core technology without Elastic always has a free alternative in principle. That single fact caps the network-effect score even as the ecosystem around the foundation deepens.
The second item, B2 on distribution scalability, scores 12 of 18, and the tension inside that score is the central tension of Elastic's commercial model. Distribution runs through sales-led enterprise selling, a consumption model on Elastic Cloud, and cloud marketplaces. Sales-led subscription revenue grew 18 to 20 percent, and the score file records annual cloud growth of 26 percent alongside monthly cloud growth of only 3 percent, reading the contrast as evidence that the sales-led motion, rather than self-serve monthly consumption, is the direction of distribution. That is a scalable motion in the sense that it reaches the largest enterprises and lands multi-year contracts, and the customer counts in the speed section are the proof that it works. The discount factor is cost. Sales and marketing expense absorbed 40.8 percent of revenue in fiscal 2026, amounting to 710 million dollars. Distribution that depends on high-cost enterprise selling is distribution that scales with headcount and compensation, not distribution that compounds on its own. The score therefore sits in the middle of the 10 to 14 anchor band: the machine reaches the right customers, but it does so expensively, and that expense is a permanent feature of the model rather than a temporary investment.
The third item, B3 on market size, scores 10 of 12, and it follows directly from the Gate G2 analysis. The combined market for search, observability, and security is described, on a press-reported frame, as above 100 billion dollars, with an artificial-intelligence retrieval layer added on top of it. Total remaining performance obligations of 1,854 million dollars already represent 10.3 percent of the 18.0 billion dollar bar. A full score is withheld for two specific reasons the score file names: artificial-intelligence revenue is not disclosed separately, and market share in the retrieval layer itself is not yet demonstrated. Both are evidence problems rather than market-size problems. The market is large enough; what is missing is the separate disclosure that would let an outside observer measure Elastic's slice of its newest part.
The fourth item, B4 on gross margin, scores 8 of 12, and it is the moat item with the clearest near-term path upward or downward. The fiscal 2026 gross margin of 76.1 percent is confirmed from the filings, and the score file calls it top-tier for software-as-a-service businesses. Subscription non-GAAP margin reached 81 percent in the first quarter of fiscal 2027. The discount factor is the direction of travel: the first-quarter gross margin fell to 74.5 percent from 76.7 percent, which the score file attributes to serverless capacity and inference service costs eating into margin. Non-GAAP operating margin moved in the same direction, from 16.4 percent in fiscal 2026 to 16.2 percent in the first quarter, while guidance for fiscal 2027 stands at 19.4 percent and remains unproven. The gap between 16.2 percent achieved and 19.4 percent guided is, in effect, the whole margin story. Closing it would support an upward revision of this item; failing to close it would confirm that the cost pressures visible in the first quarter are structural rather than transitional.
3. Speed
The Speed section, at 18 of 25, is the section that keeps Elastic below the 65-point line, and it is worth examining item by item, because the shortfall is not evenly spread. Two items are strong, one is middling, and one is constrained by a measurement gap. The section's radar conversion of 72.0 looks respectable in isolation; it only becomes a problem when set against the two points the total still needs.
The first item, A1 on growth, scores 7 of 10, and its evidence has already been set out in the discussion of Gate G1. Fiscal 2026 growth of 17.3 percent, trailing growth of 16.2 percent by calculation, and first-quarter fiscal 2027 growth of 15.1 percent, with constant-currency acceleration according to the company, describe a company re-accelerating inside a 15 to 20 percent band rather than breaking out of it. The quality of that growth supports the score: sales-led subscription growth of 18 to 20 percent, cloud growth of 22 percent in fiscal 2026, and committed-revenue growth of 21 percent for current obligations and 27 percent for total obligations all point the same way. What would lift the item above 7, according to the score file, is concrete: a recovery in net expansion together with a demonstrated return to growth in the 20 percent range. Neither has happened yet inside the assessment window, so the score stays at 7, and the two points Elastic needs must therefore come from somewhere else or wait for that evidence.
The second item, A2 on capital velocity, scores 4 of 5, and it is the cleanest item in the section. Capital is not a constraint on Elastic. Cash and securities of 1,461 million dollars stand against convertible notes of 571 million dollars, giving net cash of about 890 million dollars by calculation. Fiscal 2026 operating cash flow was 327 million dollars and adjusted free cash flow was 346 million dollars, a margin of 20 percent. Share repurchases of 40 million dollars per quarter continued through the period. The single point withheld is not about cash at all. It is about dilution, and it belongs properly to the deductions section: stock-based compensation of 298 million dollars overwhelms repurchases, so the share count does not fall. Capital velocity scores 4 because the company can fund its own growth from cash flow, and it stops short of 5 because the equity base is still expanding underneath that cash generation.
The third item, A3 on hiring and productivity, scores 3 of 5, and it is the item most constrained by missing evidence. Headcount stood at 4,019 employees as of 30 April 2026, a confirmed figure from the annual filing. Revenue per employee was about 0.43 million dollars in fiscal 2026 and about 0.45 million dollars on a trailing basis by calculation, which the score file describes as middling for enterprise software. The deeper problem is that a year-by-year hiring series was not secured for the assessment, and the first quarter brought a restructuring costing about 20 million dollars, of which 13 million dollars was cash, which the file reads as an efficiency phase rather than an expansion phase. In such a phase, there is no basis for scoring hiring speed upward. The item therefore sits at the middle of its range, held there by an absence of evidence and by a restructuring that points toward efficiency rather than toward rapid team growth.
The fourth item, A4 on share-gain velocity, scores 4 of 5, and it contains the single cleanest evidence of market-share movement in the entire assessment. Customers spending more than 100,000 dollars numbered over 1,800, after a net addition of 80 in one quarter, described as the largest such quarter on record, and up 16 percent year on year. Customers spending more than 1 million dollars numbered over 240, after 30 net additions in fiscal 2026, and the cohort spending more than 5 million dollars grew 30 percent in fiscal 2026. Public-sector displacement victories, including the expansion of the Cybersecurity and Infrastructure Security Agency's security-information-and-event-management-as-a-service deployment, provide qualitative evidence that legacy incumbents are being replaced rather than merely competed against. The discount factor is the same one that appears in the growth item: net expansion fell from 112 percent to 111 percent. New-customer acquisition is accelerating while expansion inside the existing base is softening in the trailing window, so the item scores 4 rather than 5. The distinction matters. Elastic is winning new logos faster than it is expanding old ones, and the next scoring round will show which of those two motions dominates.
4. Creative Destruction
The Creative Destruction section, at 11 of 15, converts to 73.3 on the radar, the highest of the three axes, and it is the section that most clearly describes what kind of blitz Elastic is attempting. This is not a blitz built on a new consumer behaviour or on a price collapse. It is a blitz built on consolidation: replacing several fragmented legacy tools with one platform, and then embedding that platform so deeply in the customer's artificial-intelligence stack that removal becomes expensive. Each of the three items captures a different facet of that consolidation.
The first item, C1 on the order being displaced, scores 4 of 5. The fragmented legacy order consists of keyword search, application-performance-monitoring and log tools, and legacy security information and event management systems, each historically bought and operated separately. Elastic's claim, supported in the score file by public-sector displacement victories, is that one high-performance platform replaces all of them. The expansion of the Cybersecurity and Infrastructure Security Agency deployment is the named example, and it matters precisely because public-sector displacements are competitive, documented, and difficult to win on narrative alone. The point withheld reflects scope. The displacement is confined inside enterprise software, and native alternatives from the hyperscalers remain available, so the order being replaced is a software category rather than an economy-wide way of doing things. A score of 4 records a real displacement with a defined boundary.
The second item, C2 on irreversible behaviour change, scores 4 of 5, and it is where the artificial-intelligence story becomes a lock-in story. Once an artificial-intelligence application is built on Elastic as its retrieval layer, the costs of switching rise sharply, because the data pipelines, the embeddings, and the permission model become intertwined with the application itself. Removing the layer would mean rebuilding how the application finds, ranks, and governs its own data, not merely swapping a vendor. The quantitative support for that claim is the 43 percent growth in non-current remaining performance obligations in fiscal 2026, which shows customers committing to multi-year contracts rather than renewing quarter by quarter. Price increases for fiscal 2027, of 3 percent for cloud and 5 percent for self-managed deployments, were also carried through, which the score file records as having been done without attrition. A full score is withheld for the same reason that caps several other items: artificial-intelligence revenue is not separately demonstrated, so the depth of the artificial-intelligence lock-in can be inferred from contracts and customer counts but not yet measured in revenue.
The third item, C3 on cost-structure change, scores 3 of 5, and it is the most cautious item in the section. Claims are made for serverless and inference cost efficiency, but the first-quarter margin moved in the opposite direction, falling to 74.5 percent, which the score file reads as a cost pass-through phase rather than a cost collapse. A genuine change in cost structure would show up as a falling cost of serving each additional customer, and the evidence inside the window shows the opposite: serving costs rose faster than prices, at least in the first quarter. Whether the fiscal 2027 price increases of 3 percent and 5 percent offset that cost rise will be judged, in the score file's framing, by whether the 19.4 percent operating-margin guidance is achieved. Until that evidence arrives, the item stays at 3, a score that records a claim made but not yet proven.
5. Deductions and Risks
Total demerits are 5 points, which is why Elastic carries no FLAG, but the composition of those 5 points is more informative than the total. The deductions describe a company whose balance sheet is clean and whose risks sit in compensation, in the quality of a single year's headline profit, and in a structural competitive overhang that never quite goes away. None of them individually threatens the assessment, and together they still fall ten points short of the FLAG trigger. Their importance lies in what they reveal about the distance between reported figures and underlying economics.
The largest deduction, D1 on debt, is 3 points, and it is not really about debt at all. Debt itself is light: convertible notes of 571 million dollars against net cash of about 890 million dollars. The real deduction is stock-based compensation, which reached 298.4 million dollars in fiscal 2026, equal to 17.2 percent of revenue, and which has risen steadily from 239.1 million dollars in fiscal 2024 and 257.8 million dollars in fiscal 2025. Share repurchases of 40 million dollars per quarter do not offset that compensation, and the share count rose from 101.7 million to 105.0 million over two years. The score file folds the first-quarter restructuring cost of about 20 million dollars into this item as well. The picture is therefore one of a company that generates real cash flow and then returns a substantial part of its economics to employees in equity, diluting the very shareholders whose capital the cash flow is meant to serve. That is a cost of the business model, and the deduction records it as such, even though no lender is at risk.
The second deduction, D2 on revenue quality, is 1 point, and it concerns a single distortion in an otherwise clean set of accounts. There were no restatements and no audit issues. But fiscal 2026 GAAP net income of positive 367.8 million dollars depended on a 434.9 million dollar valuation-allowance reversal related to tax positions in the Netherlands, the United Kingdom, and Canada, a one-time tax benefit. GAAP operating loss for the same year was negative 33.5 million dollars. The headline profit therefore overstates the operating reality of the year, and the small deduction records that overstatement without suggesting anything improper. A reader who looked only at the net income line would conclude that Elastic had become solidly profitable in fiscal 2026; a reader who looked at the operating line and the tax note would conclude that the underlying business was still close to breakeven on a GAAP basis, with profitability visible instead in the non-GAAP operating margin of 16.4 percent and the adjusted free cash flow margin of 20 percent. Both readings are in the filings; only the second survives contact with the tax note.
The third item, D3 on governance, scores 0, which in this model means no trigger rather than a positive endorsement. In the fiscal 2026 annual filing excerpts reviewed, no dual-class voting structure and no controlling-shareholder flag was identified. The founder, Shay Banon, is no longer chief executive, with the Kulkarni leadership in place since 2022 on a press-reported basis, and no management dispute or insider-selling issue was identified in the material reviewed. One explicit limitation applies: Form 4 filing clusters were not reviewed, being outside the scope of the assessment, so the item is recorded as "no-trigger" rather than as a fully confirmed clean bill. That label is preserved here exactly as the score file uses it, because the difference between "no trigger found in the material reviewed" and "no trigger exists" is the difference between honest scoring and overclaiming.
The fourth item, D4 on regulatory and social cost, is 1 point, and it follows the same pattern of a small deduction for a structural overhang rather than a confirmed event. No confirmed fines or litigation issues were identified in the disclosures reviewed. The recorded overhang is the OpenSearch fork, backed by Amazon Web Services, which provides a permanent free alternative to the core technology and therefore caps pricing power and moat scores alike. Data-sovereignty requirements are recorded as both an opportunity and a compliance surface, with on-premises and air-gapped embedding offered as the response. The licence history, from the 2021 move to the Server Side Public License to the 2024 return to the Affero General Public License, is noted as a trust variable but is explicitly not treated as a deduction reason. The single point therefore records a competitive structure, not a penalty for a past event.
Beyond the scored deductions, the score file names one further risk that belongs in any honest account of Elastic, because it is the risk that would matter most if it materialised. The file calls it, in its blitzscaling-fit analysis, the risk that the owner of the artificial-intelligence layer turns out to be someone else. Elastic is attempting to occupy the retrieval layer of its customers' artificial-intelligence applications, but hyperscalers, model providers, and specialist vector-database companies are pursuing the same layer. The OpenSearch fork adds a second version of the same threat: even if the layer is valuable, it may be available without Elastic. The score file's judgement is that Elastic's defence is the depth of its data foundation rather than the Elasticsearch name alone, because a name that denotes a standard can be forked, while a foundation embedded in pipelines, permissions, and multi-year contracts is harder to replicate. Whether that defence stands is, in the file's framing, the central question for the next phase of the assessment.
6. What to Watch
The score file names its own triggers for the next round, and this section reports them without adding predictions of its own. The most immediate is the second quarter of fiscal 2027, which ended on 31 October 2026 and is due for announcement in late November 2026, after the assessment date. The score file identifies that quarter as the judgement quarter for the 65-point question, and the logic is straightforward. Two points are needed, and the file names two routes to them: growth returning to the 20 percent range, which would lift the growth item from 7 toward 8, or demonstrated evidence in one of the moat items, above all the network-effect item or the gross-margin item. Either route runs through the same underlying evidence: net expansion recovering from 111 percent, artificial-intelligence customers expanding rather than merely adopting, and the operating margin moving toward the guided 19.4 percent.
The margin guidance deserves separate attention because the score file treats it, in its own words, as close to a score guidance. Fiscal 2027 non-GAAP operating-margin guidance of 19.4 percent, against 16.4 percent achieved in fiscal 2026 and 16.2 percent in the first quarter, represents an improvement of 3.0 percentage points that must be delivered through some combination of the fiscal 2027 price increases, the first-quarter restructuring, and serverless efficiency. The first quarter moved the wrong way on gross margin, so the burden of proof sits with the coming quarters. If the margin recovers, the gross-margin item has room to move from 8 toward 9 or 10, and that movement alone could close the two-point gap. If it does not, the cost-structure item's cautious score of 3 will look prescient rather than pessimistic.
Two disclosure questions will also shape the next assessment, and both are matters of evidence rather than performance. The first is whether artificial-intelligence revenue is disclosed separately. Until it is, the artificial-intelligence thesis can only be read indirectly, through customer counts, committed revenue, and net expansion, and the network-effect and behaviour-change items will remain capped for that reason. The second is whether artificial-intelligence customers expand at a rate that restores net expansion to its earlier level. Adoption without expansion would suggest that the retrieval layer is being tried but not yet depended upon; adoption with expansion would suggest the embedding the score file describes is actually happening. Subscription quality is the quieter variable underneath both questions: subscription revenue already represents 94 percent of the total in the score file's summary, so the business is not dependent on one-time licence sales, and the question is whether that subscription base deepens or merely widens.
In the score file's blitzscaling language, Elastic is a mature company's second blitz, an "embed blitz" won by becoming buried inside the customer's artificial-intelligence stack rather than by spreading quickly across a new population. Its main lever is the platform, a single data foundation carrying search, observability, and security; its secondary lever is the artificial-intelligence retrieval layer; its weak levers are network effects and viral distribution, the latter replaced by high-cost enterprise selling. That description is consistent with everything in the scored sections: a platform company whose moat is depth, whose speed is constrained by the cost of its own distribution and by dilution, and whose creative destruction is real but bounded inside enterprise software. At 63, two points below the line, Elastic is close enough to the club that the next quarter's evidence matters, and far enough below it that no single favourable data point should be treated as decisive. The assessment, as of 25 October 2026, is that of a company whose second curve is demonstrated in customers and contracts, not yet in separately disclosed revenue, and whose margin story is stated in guidance, not yet in results.
More Platforms companies
Other Platforms names on the Blitz Index, highest score first: Alphabet (83/A), Meta (78/B), Airbnb (76/B).
Next earnings
Nov 19, 2026 · After close · Confirmed
Coverage
Elastic N.V. · Q2 FY2027 due Nov 19, 2026 (expected) · Score 63 · Grade B
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.